Feds accuse nine top banks of de-banking — denying accounts due to ideology, religion, and more


After President Trump made it a point to declare banking rights as guaranteed and fair for Americans, the government actually went to work.

Now, a federal agency has revealed that major U.S. banks were guilty of limiting or denying access to financial services to citizens based on their beliefs or business activities, and the evidence is shocking.

A payment processor owned by one bank closed the account of a merchant that sold Make America Great Again merchandise.

The Office of the Comptroller of the Currency released a scathing report detailing its intention to review potential de-banking activities at the nine largest banks in the country and whether or not they had been improperly limiting access. This was in direct response to President Trump's executive order to guarantee fair banking for all Americans.

The report declared that between 2020 and September 2025, all nine banks had policies in place that do so.

The OCC identified two categories that presented an "elevated risk of 'encouraging' or 'otherwise influencing'" institutions to deny access to financial services: reputation risk practices and industry specific practices.

The first can be summarized as a potential for "adverse" brand impact resulting from negative public perception, while the latter is an alleged bias toward certain industries or sectors unrelated to financial or operational concerns.

The practices affected both sides of the political aisle. For example, in February 2023, one bank declined to provide public services to an educational organization because it solely endorses Democrat candidates.

In February 2021, a payment processor owned by one bank closed the account of a merchant that sold Make America Great Again merchandise.

These policies reportedly negatively affected industries like firearms, oil and gas, coal mining, prisons, and tobacco.

RELATED: The fight over prediction markets is hitting the Supreme Court — and dragging in the NFL
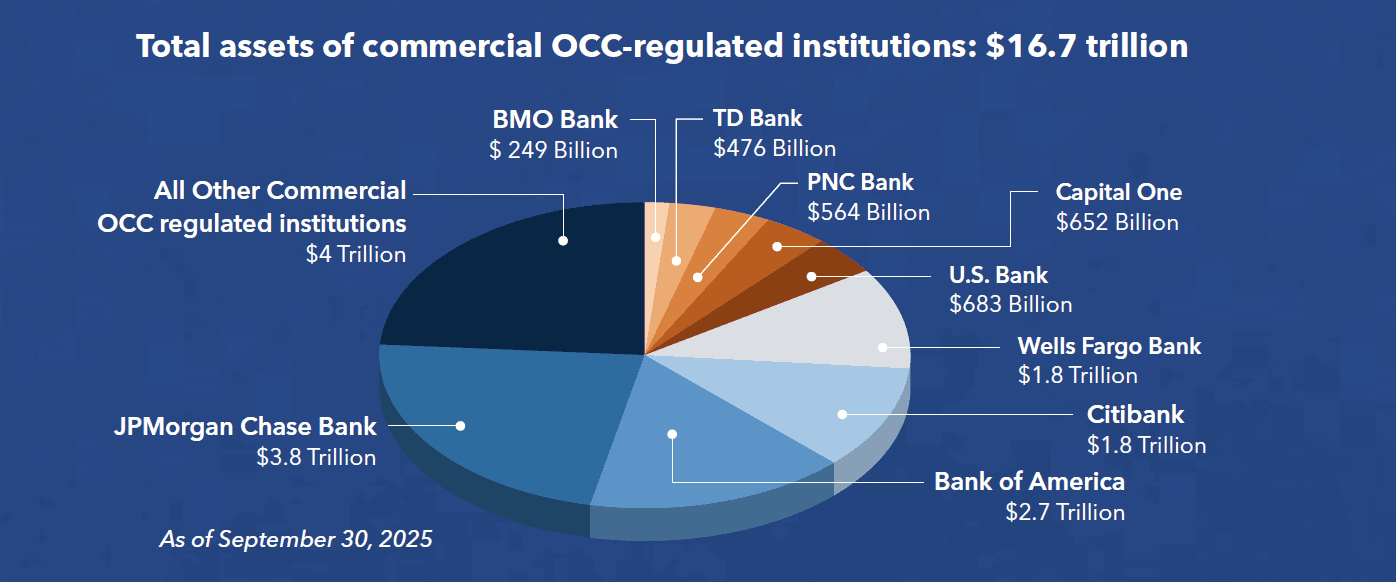
Image courtesy Office of the Comptroller of the Currency

In the report, the OCC said it observed Citibank using an "environmental and social risk management policy" that restricted it from entering into a business relationship with customers that did not have policies that align with Citibank's firearm standards.

"This included, for example, limitations on the sale of high-capacity magazines and restrictions on firearm sales to individuals under the age of 21."

In February 2021, TD Bank was making decisions regarding a Paycheck Protection Program loan based on its own reputation risks, the report claimed.

"TD's decision is based on public statements about immigrants made by [the organization] or people affiliated with your organization, including social media activity, leading up to and following the November 2020 election. These statements are inconsistent with TD's values," the bank wrote, per the federal government.

All nine banks were cited in the report as having conducted biased practices based on their perceived reputational risk or simply their policy regarding whether or not they wanted to do business with people based on their industry or their activities.

RELATED: Guess which secretive former president has big ideas about how AI should control you

Another example included Capital One flagging a religious organization, in multiple client reviews, for stances on abortion, LGBTQ rights, and "ties to the world of conservative politics."

The OCC has suggested making changes to the client complaint process, forcing increased transparency, and redefining how it considers politicized or unlawful de-banking.

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

How The Trump Administration Should Reform SBA Lending To Empower Entrepreneurs

It would only take a few small changes to help make the American dream achievable for more small business owners.

5 Ways The Right Can Start Fixing The Student Loan Crisis Without Punishing Taxpayers

We need to do something to bridge the gap back to the American dream for college grads.

How To Fuel An Entrepreneurship Revival To Save America From AI-Driven Job Loss

Why there will be a groundswell of new small businesses and how the Trump administration can help them flourish.
Labor Dept. Has Done Nothing To Recover Half-A-Billion Dollars In Suspected Covid Fraud

Congress has created a Leviathan too big to manage, giving fraudsters an easy opportunity to pick taxpayers’ pockets by the millions and billions.

'Assets of fear': BlackRock CEO Larry Fink FLIPS on crypto


BlackRock's CEO has seemingly changed his mind about the future of Bitcoin and cryptocurrency.

Investor Larry Fink famously criticized Bitcoin in 2017 when he called it an "index of money laundering" that simply showed how much demand there was in the world to launder funds.

'I do see more and more of a future of having more and more financial assets being digitized.'

Now, during a sit-down with the CEO of hedge fund Citadel, Ken Griffin, Fink said he sees cryptocurrency wallets being used to make stock moves en masse in the near future.

Fink revealed during the conference that if he could "tokenize" all ETFs and provide them in a digital wallet, users would be able to seamlessly make trades.

"You could seamlessly, without fees, ... buy bond or stocks, and I believe that is going to be the future," Fink said. "I do believe more transactions [are] going to be done digitally with authentication of ownership."

He added, "I do see more and more of a future of having more and more financial assets being digitized, sitting in a singularity of a blockchain and going from cash to stocks to bonds, back and forth, doing that seamlessly, and I do believe that is going to happen sooner, not later."

During the same event, Fink described Bitcoin as an investment made out of fear, but not in the way one might think.

RELATED: Bitcoin billionaire will serve time after British police broke down her door and arrested her in bed

Fink described Bitcoin and gold along similar lines, calling them "assets of fear" that investors scoop up when they are "frightened of the debasement of your currency."

"You own it if you have financial insecurities, or you own it if you have physical insecurities and worries. So, that's one of the foundational issues of my journey in understanding crypto more."

Fink has confused audiences over the years with his remarks on digital currency, both in his evolving stance on the asset and, of course, his — along with other major institutions — apparent inability to recognize that it is in fact being used as he prophesies it will be used in the future.

Fink's pontifications about the future of crypto, fiat, ETFs, and stocks/bonds being traded seamlessly on apps are already a reality. Countless companies allow direct deposit of paychecks to digital wallets, the same as any bank, while also providing the ability to trade stocks and cryptocurrency in-house.

RELATED: Almost HALF of Gen Z wants AI to run the government

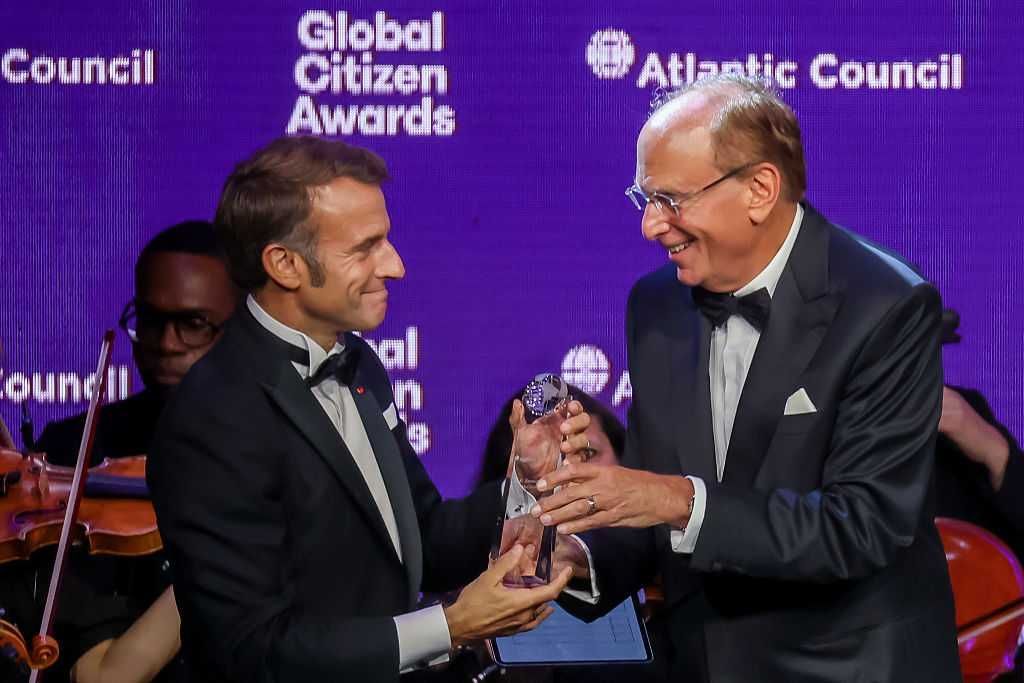
French President Emmanuel Macron, left, and Larry Fink. Photographer: Michael Nagle/Bloomberg via Getty Images
It is unclear if BlackRock's plan was to slow-walk its investors into cryptocurrency cautiously, but its CEO has certainly made gradual strides in the direction of acceptance, hallmarked by his most recent comments.

In 2024, Fink seemed to turn a new leaf when he admitted he was wrong about Bitcoin and told CNBC he thought it had become a legitimate asset.

"It is a legitimate financial instrument that allows you to maybe have uncorrelated type of returns. I believe it is an instrument that you invest in when you're more frightened, though. It is an instrument when you believe countries are debasing their currency by excess deficits, and some countries are," Fink explained.

Moreover, the CEO even referred to Bitcoin as "digital gold," which is now in step with his recent description of the asset.

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

‘A billion dollars' worth of exceptions’ — Glenn Beck: The REAL Epstein story isn’t the black book, it’s the bank


Jeffrey Epstein’s name is yet again dominating headlines as the American people await a third major handover of Epstein-related documents. President Trump signed the Epstein Files Transparency Act into law, mandating the Department of Justice’s public release of all unclassified files related to Jeffrey Epstein and Ghislaine Maxwell. Once again, everyone’s holding their breath for the flight logs, communications, and investigative records slated for release on December 19, 2025.

But Glenn Beck says “the real story” about Epstein isn’t the clients; it’s “the money.”

Per newly unsealed JPMorgan court documents from a 2023 U.S. Virgin Islands lawsuit, between 2002 and 2019 — despite ending Epstein's accounts in 2013 amid red flags — JP Morgan Chase filed just seven Suspicious Activity Reports on Epstein. It flagged only $4.3 million, while overlooking roughly 5,000 more suspicious transactions totaling over $1.3 billion, which were linked to potential sex trafficking, massive cash withdrawals, wires to Russian banks, and payments to or from high-profile Epstein associates.

“Let me just say this clearly so nobody really misses the gravity of this,” says Glenn. “You do not accidentally forget to report 5,000 suspicious wires. ... You don't misplace a billion dollars in wires to foreign banks and shell companies connected to a convicted sex offender under federal investigation. It doesn't happen.”

“It doesn't happen because a junior banker made a mistake. It doesn't happen because the compliance officer was sleepy. It doesn't happen because somebody's inbox was full. ... At a minimum: multiple officers, multiple departments, multiple sign-offs [chose] not to look.”

Why? Because “the bank decided, ‘Well, we want to continue to work with Epstein. He's valuable; he's connected; he's a referral engine to some of the richest people in the world,”’ says Glenn, arguing that somebody turned off the alarm bells on Epstein’s account.

“I'd like to know who turned those off. I'd like to know why they were turned off. I would like to know if it was just the leadership of the bank. I'd like to know that every single one of those bank officers all the way to the top go to prison,” he says.

“If you or I did this — if we had sent just a handful of suspicious wires — the bank would freeze your account, notify the Treasury before you could blink. But Jeffrey Epstein? A billion dollars' worth of exceptions.”

The most “terrifying question” we should all be asking ourselves right now, Glenn says, is this: “If a bank can look the other way on $1.3 billion for a sex trafficker, what else have the banks learned to ignore?”

“This story isn't just about Epstein. This is about the machinery that allowed him to operate — all of the middlemen, all of the financial networks, all of the institutions that treated him like an asset instead of a criminal,” he says.

To hear more of Glenn’s analysis and his Epstein theories, watch the clip above.

Want more from Glenn Beck?

To enjoy more of Glenn’s masterful storytelling, thought-provoking analysis, and uncanny ability to make sense of the chaos, subscribe to BlazeTV — the largest multi-platform network of voices who love America, defend the Constitution, and live the American dream.

Analysis: How diversity dogma and H-1B visas sank a proud American brand


The United Services Automobile Association is one of the most venerable names in banking and insurance, a company that prides itself on its service to members of the military and their families. In recent years, however, USAA has run into serious financial trouble due to a combination of mismanagement, fashionable diversity, equity, and inclusion policies, and the firm’s increasing reliance on incompetent and untrustworthy H-1B workers, most of whom are from India.

A significant number of current and former USAA employees have come forward to discuss what they describe as a toxic workplace culture, which has led to an alarming number of employee suicides, and the company's outsourcing of critical functions to H-1Bs and Indian consultancies, putting at risk the financial data of its customers, which include high-ranking members of the U.S. armed forces.

What began as a cost-cutting strategy in the early 2000s now threatens the stability of an institution long trusted by veterans.

Insiders granted anonymity to avoid retaliation say USAA’s decline began in the 2000s under then-CEO Robert G. Davis, who outsourced IT and other core functions to H-1B contracting firms such as Tata Consultancy Services. Those firms imposed contracts requiring USAA to maintain minimum staffing levels, creating chronic overstaffing. Idle contractors were reportedly assigned “busywork” to meet quotas, with conference rooms converted into laptop farms where workers sat “packed like sardines.”

One insider described the result as “incredibly incompetent” operations. Projects that U.S.-based employees could complete on time were instead handed to H-1B contractors who often lacked the necessary skills and required retraining.

From cost-cutting to collapse

At the same time, USAA repeatedly laid off American staff and replaced them with foreign workers, driving labor costs higher and eroding institutional knowledge. Davis retired abruptly in 2007, but his successors continued his policies, expanding USAA’s offshore footprint with new IT centers in Guadalajara, Mexico, and Chennai, India.

Insiders say H-1B contractors at USAA often lack basic programming skills, compounding inefficiency. In one case, a credit card processing problem baffled contractors for six months until the company brought back a retired American employee, who solved the problem in a matter of days. The constant visa turnover worsens the issue. Skilled H-1Bs leave after six years, draining institutional knowledge. Turnover is even higher at USAA’s Guadalajara facility, where Indian employees reportedly fear cartel violence.

Bureaucratic bloat magnifies these problems. Each team has dual directors, and many systems rely on outdated software. That dysfunction has drawn scrutiny from federal regulators, who fined USAA for failed audits and violations of anti-money-laundering laws. Those failures forced the company to sell off divisions, including real estate, and pushed USAA into persistent losses through much of the decade.

Customers have also felt the effects. Many complain that poorly trained H-1B staff struggle to handle basic service requests. One customer said resolving a fraud alert took hours — and that he now contacts USAA’s top executives directly to get results.

Security risks and cultural decay

USAA’s growing dependence on H-1B contractors and overseas labor has created potential security and compliance risks, according to multiple insiders. The company has outsourced anti-money laundering work to Tata Consultancy Services, which reportedly performs much of that work in India. As a result, the personal financial data of U.S. service members and veterans may be stored or processed abroad.

USAA also shares customer data — including names, addresses, and birth dates — with LexisNexis, with no option for customers to opt out. One customer said he only discovered this practice after receiving a notice in the mail.

RELATED: The visa that ate America’s tech jobs

subodhsathe via iStock/Getty Images
Inside the company, these policies have coincided with a marked decline in morale. Mass layoffs of veteran employees have preceded at least three suicides, including one who shot himself in a company parking lot. A former director described intervening to stop another potential suicide. Tensions intensified during the COVID-19 pandemic, when USAA defied Texas Republican Gov. Greg Abbott’s executive order banning vaccine mandates.

Employees describe a sharp cultural shift away from USAA’s traditional military ethos toward a mishmash of corporate diversity programming. The company has hosted Diwali celebrations and mandatory DEI events while facing allegations of religious discrimination against Christian employees. One former employee has taken a case to arbitration. Internal surveys reportedly show employee satisfaction at just 33%.

An institution on the brink

Analysts say the company’s reliance on foreign labor and internal instability have eroded its reputation for customer service and financial stewardship. What began as a cost-cutting strategy in the early 2000s now threatens the stability of an institution long trusted by veterans.

Whether USAA can recover will depend on its ability to restore confidence — both among employees and the members it was established to serve.

Conservatives can lead the charge on clean crypto rules


Many assume conservative principles belong to the past. They don’t. The debate over cryptocurrency regulation — including the House GOP’s Clarity Act — offers a chance to apply those principles to a 21st-century frontier.

Cryptocurrency and decentralized finance reflect core American values: free speech, free markets, and innovation from the ground up. Across the country, developers are building protocols that move money in microseconds, create new investment tools, and expand access to capital like never before.

With a Republican-led Congress considering landmark cryptocurrency legislation, we have a historic opportunity to apply time-tested conservative values to the cutting edge of financial innovation.

Blockchain technology provides a means to secure property rights in the digital era. The most transformative products likely haven’t even launched yet.

The potential benefits are massive. In 2024 alone, decentralized finance grew to more than $114 billion. Even more capital — billions of dollars — stands ready to enter the space through pension funds and institutional investors.

But that money won’t move without guardrails.

Institutional investors need transparency. That means audit requirements they can trust, legally accountable custodians, clear reporting on asset health, and safeguards against manipulation.

They also need legal certainty. Defined rules give investors confidence. Without them, they’ll stay away — or invest elsewhere.

That’s where Washington plays a role.

The Trump administration shifted U.S. regulatory policy toward digital assets, elevating crypto to a national priority through executive order. Now, with a Republican-led Congress weighing landmark crypto legislation, conservatives have a real opportunity.

This moment demands more than slogans. It calls for applying time-tested conservative principles — rule of law, market discipline, and individual liberty — to the future of finance.

Don’t be afraid

Some treat cryptocurrency as a threat. Fair enough — the collapse of FTX still casts a long shadow over the current debate in Congress.

Sam Bankman-Fried, a Democratic megadonor, didn’t just run a failed company. He ran a cautionary tale — a playbook for what lawmakers must never allow again.

The FTX scandal highlights two enduring conservative truths:

  1. Human nature is flawed. Left unchecked, individuals will act out of greed and self-interest. Conservatives have never pretended otherwise — and that’s why we build systems of accountability.
  2. The rule of law matters. Pre-established standards prevent chaos. Waiting for disaster or making policy on the fly only magnifies the damage.

FTX didn’t collapse because of cryptocurrency. It failed because no one held Bankman-Fried accountable. He amassed influence through backroom politics and ran a tangled network of private firms without meaningful oversight. The result: billions vaporized and public trust shattered.

Thoughtful legislation can prevent the next meltdown — not by stifling innovation, but by setting clear, enforceable rules rooted in transparency, responsibility, and the rule of law.

A remedy with room to improve

The bill now before Congress offers a rare chance to get crypto regulation right.

It tackles the custodial vulnerabilities exposed by the FTX collapse and establishes a framework that allows digital asset projects to integrate into the broader financial system. Just as important, it does so under a unified set of rules.

The bill follows conservative logic. It exempts infrastructure providers — such as blockchain validators and payment processors — from regulatory burdens that don’t apply. These actors don’t make governance decisions, and the law should reflect that.

It also classifies participants based on their actions, rather than the extent of their political influence.

But the bill still needs one critical fix.

Lawmakers need to include decentralized autonomous organizations as eligible cryptocurrency issuers. These DAOs, the opposite of central banks, operate through user-led governance. Crypto users vote on the rules of the system they help create.

DAOs have become common in decentralized finance. Yet the current bill overlooks them. That omission could block the very groups driving innovation from entering the regulated space.

RELATED: Trump’s Bitcoin masterstroke puts America ahead in digital assets

Photo by Anna Moneymaker/Getty Images

If a project follows the rules, discloses information, and acts responsibly, it should qualify, regardless of how it governs itself. Whether the issuer is a DAO, a startup, or a traditional bank, one standard should apply.

That’s the conservative way: equal rules, fair enforcement, and space for innovation to thrive.

What if we get it wrong?

Leaving the bill unamended carries real risks:

  • Overreaching compliance rules could smother the best of American innovation — now and in the future.
  • Narrow legal definitions might force decentralized finance into the hands of a few massive exchanges, recreating the same “too big to fail” system that burned taxpayers in 2008.
  • Ongoing regulatory ambiguity could drive developers and infrastructure providers offshore, into the arms of authoritarian regimes eager to benefit from America’s hesitation.

The biggest danger? Watching capital and talent flee to countries that welcome decentralized commerce while the United States — its origin point — falls behind.

Decentralized finance leaders aren’t calling for lawlessness. They want smart policy.

Joe Sticco, co-founder of Cryptex and a White House Crypto Summit participant, put it this way: “In DeFi, it’s not about evading rules — it’s about building better ones.”

Sticco believes today’s innovators want a seat at the table. “We believe open financial systems can coexist with responsible oversight,” he told me. “We have to show up, we have to explain the tech, and we have to help shape the rules.”

Congress still has time to get this right. But the window is closing.

The path forward

Republicans now hold both chambers of Congress. That means the window to act is wide open.

This isn’t about growing government. It’s about setting the rules so innovation can thrive, fraud gets stopped, and people are held accountable. Here's what that looks like:

  • Clear rules that apply fairly to both traditional companies and decentralized projects;
  • Basic protections like audits, secure custody of funds, and anti-fraud measures;
  • Freedom for developers to build new tools without unfair roadblocks;
  • And clear standards for when crypto projects are considered stable enough to ease up on oversight.

With these fixes, the Clarity Act can do what no other crypto bill has: protect investors, promote innovation, and keep America in the lead.

We can build the future of finance right here — on American terms, with American values. But we have to act now.

New Laws Restrict Indiana Treasurer Who Protects Americans From Debanking

The banking industry is attempting to take programs from Indiana's state treasurer because he works to protect Christians and conservatives.