This coast-to-coast rail merger could cut your expenses
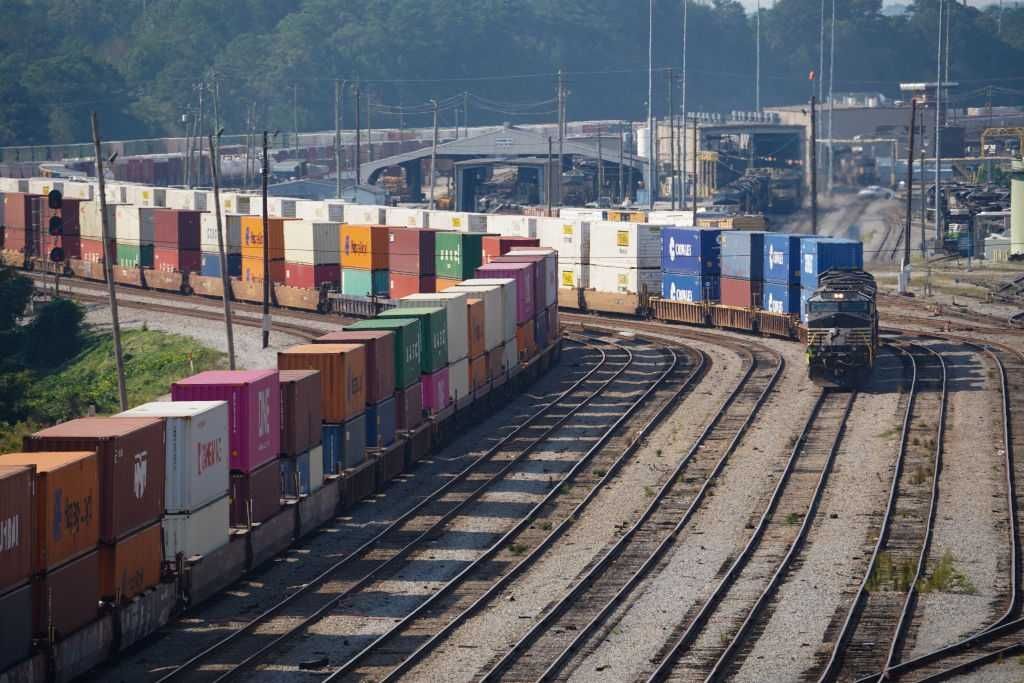


Government micromanagement has throttled economic growth for decades. The latest example came when the Surface Transportation Board deemed the Norfolk Southern-Union Pacific merger application incomplete and rejected it without prejudice. That decision delays what would be the first uninterrupted transcontinental railroad in American history — a privately financed project that could strengthen supply chains, boost growth, and improve American competitiveness without costing taxpayers a dime.

For now, that vision sits on hold.

A stronger rail network would help stabilize the supply chain while lowering costs for producers and consumers alike.

The STB said the 7,000-page filing lacked several key materials, including a full market-impact analysis with traffic projections. Norfolk Southern and Union Pacific now must fill in the gaps and refile.

That setback does not decide the larger question. Rail mergers have recovered from early regulatory obstacles before, and the STB’s ruling on completeness says nothing definitive about the underlying merits of this merger.

In May 2021, for example, the STB rejected CSX’s application to acquire Pan Am Railways as incomplete. Two months later, CSX resubmitted the application, and the board accepted it. The combined railroad later expanded shipping options, lowered freight costs for shippers, and supported regional growth.

Opponents of the present merger nevertheless treat the incomplete ruling as a final victory. It is not. It is a procedural delay, not a substantive rejection. And history shows that rail mergers of this kind can generate real economic benefits.

Today, shipping goods across the country by rail often means navigating a patchwork system of freight lines, transfer points, and carriers. Businesses must coordinate among multiple operators just to move a product from one coast to the other.

That fragmentation imposes real costs. It slows delivery, raises uncertainty, and forces businesses to protect themselves with larger inventory buffers and wider shipping windows. Those costs do not disappear. Businesses absorb some of them, and consumers pay the rest.

Farmers, manufacturers, and other suppliers feel that pressure most acutely. Many already operate on thin margins. Add shipping delays and higher freight costs, and those businesses face hard choices: eat the loss, cut investment, or raise prices.

That is why the Union Pacific-Norfolk Southern merger matters.

A stronger rail network would help stabilize the supply chain while lowering costs for producers and consumers alike. It also would mark the first time companies attempted to create a true transcontinental rail line without asking taxpayers to foot the bill.

RELATED: The railroad that could unite — and revive — America
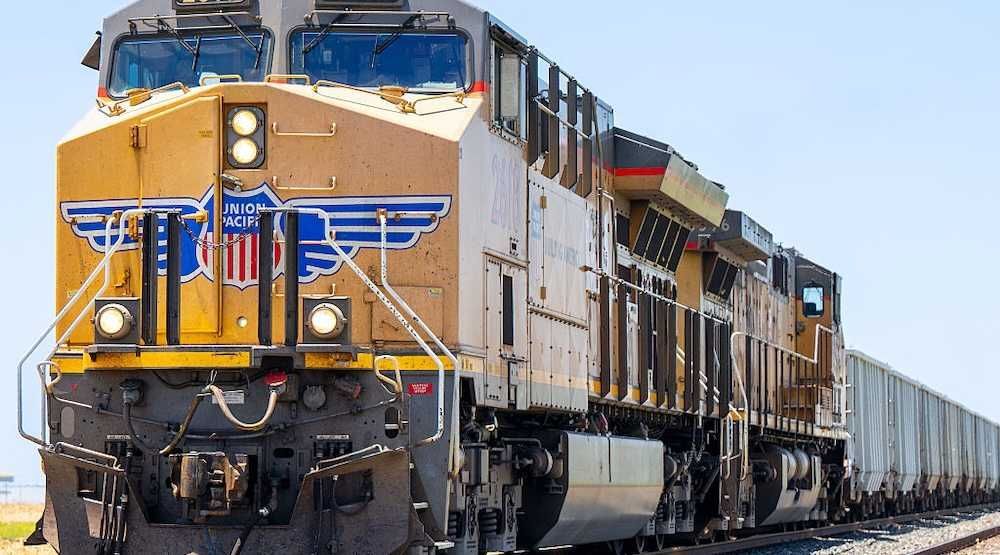
Photo by Brandon Bell/Getty Images

The competitiveness argument matters too. A USDA study found that wheat grown in 2022 cost more to ship by rail to western ports in the United States than in Canada, even across comparable distances. Canada produces far less wheat than the United States, but its less fragmented rail network gives its exporters an advantage. American farmers, by contrast, compete from a structurally weaker position because the U.S. rail system remains broken into discontinuous lines.

That disadvantage carries real consequences. When uninterrupted, rail can move freight at costs up to 60% lower per ton than other transportation modes. A more seamless coast-to-coast rail network would narrow the gap between American producers and their foreign competitors.

Critics argue that the merger would reduce competition in shipping. That view is too narrow. Freight competition does not occur only within rail. Shippers compare rail with trucking, barges, pipelines, and air cargo. A stronger rail network would not eliminate those alternatives. It would complement them. In a resilient supply chain, businesses need multiple transportation options, not fewer.

An efficient rail system would make the entire freight market stronger by giving shippers another dependable, lower-cost tool for moving goods.

The task now is straightforward: Norfolk Southern and Union Pacific should complete the review process quickly and responsibly. The precedent exists for a successful resubmission after an incomplete ruling. If that happens here, Americans will gain the kind of privately financed infrastructure upgrade the country badly needs.
Tariffs Aren’t Raising Prices, CNN Admits After 5 Articles Insisting Tariffs Were Raising Prices

“Prices would rise — sharply — they said, reigniting an inflation crisis that tens of millions of Americans had elected [President Donald Trump] to solve,” CNN’s David Goldman wrote on Friday. “But that massive, tariff-induced inflation spike hasn’t materialized. Not even close.” Indeed, it hasn’t. But who exactly is Goldman referring to when he says, […]
Americans' top concern is now inflation, but Psaki blames 'people's psychology' for pessimism about Biden's economy


There is no shortage of data points that illustrate major worries about the U.S. economy — especially when it comes to inflation. A new poll finds that inflation is now the top concern of Americans. However, White House press secretary Jen Psaki claims that Americans who have pessimism about Biden's economy are because of "people's psychology" about the pandemic.

Inflation in November was 6.8% — the highest in nearly 40 years.

Gas prices skyrocketed 58.1% over the past year, and heating oil spiked 34.3%. Besides soaring energy costs, Americans are also paying way more for food. The cost of bacon shot up 21%, beef and veal prices have swelled 20.9%, pork chops are up 12.7%, chicken rose 9.2%, fish and eggs climbed 8%, coffee increased by 7.5%, and cereal was up 5.7%.

Prices for consumer goods also increased from last November. Furniture rose 12%, laundry equipment jumped 9.2%, bikes are up 9%, and tools and other outdoor equipment increased 6.9%.

The U.S. Department of Labor reported that used car and truck prices soared 31.4% year-over-year, and rental cars jumped 37.2%.

Another month of rising prices under Biden:\n\nGas: +58.1% since last year \nBacon: +21%\nEggs: +8%\nSteak: +24.6%\nPropane & Firewood: +34.3%\nFurniture: 11.8%\nUsed Cars & Trucks: +31.4% \nCoffee: +7.5%\nCigarettes: +9.4%\nHotels & Motels: +25.5%\nCar & Truck Rentals: +37.2%\nBikes: +9.4%
— Jacki Kotkiewicz (@Jacki Kotkiewicz) 1639144241

A CNBC All-America Economic survey released on Friday found that inflation has "firmly eclipsed" coronavirus as the No. 1 concern.

Nearly half of Americans say that inflation has caused them "financial hardship," according to a Gallup poll released earlier this month.

A Yahoo News/YouGov survey released last month said that 77% of Americans say inflation has personally affected them. A clear majority — 57% — blame President Joe Biden for the high prices caused by inflation.

The White House attempted to deflect blame for inflation. Psaki blamed "people's psychology" for negativity regarding the current economy.

During Friday's White House press briefing, a reporter cited a recent NPR/Marist poll that stated 61% of Americans say the country is moving in the wrong direction. The reporter then asked Psaki, "What’s the White House’s big-picture view on why so many Americans are so pessimistic about the economy and about the direction of the country?"

Psaki replied, "Why are people experiencing things or why — because — and I — we’ve talked about this a little bit before. But, you know, a lot of it — what we’re seeing in our data is people’s psychology on the economy, on how they’re experiencing things in the country right now is related to COVID and the fact that COVID — we’re still in a fight against this virus."

"People expected it to be over sooner," she added. "We have new variants that have come up. And people are looking to get back to a normal version of life."

Psaki blames Covid for why people are so pessimistic about the economy:\n\n\u201cPeople\u2019s psychology on the economy, on how they\u2019re experiencing things in the country right now, is related to Covid.\u201dpic.twitter.com/szzkr96hYo
— The First (@The First) 1639167633

Psaki was also asked if Biden will "acknowledge that inflation is more entrenched and not transitory?"

Psaki responded, "But I think part of the point here is that it doesn’t really matter what you call it." She added that the White House and Federal Reserve view is that "inflation will ease over time."

In July, Biden said that price increases from inflation were temporary, Reuters reported.

In recent weeks, both Federal Reserve Chairman Jerome Powell and Treasury Secretary Janet Yellen said it was time to retire the term "transitory" when characterizing inflation.

REPORTER: "Does the president acknowledge that inflation is more entrenched and not transitory?"\n\nPSAKI: "Doesn't really matter what you call it"pic.twitter.com/FaM6XQxMKb
— RNC Research (@RNC Research) 1639166580

Inflation shot up even higher than expected in November, on fastest climb in 40 years


Inflation jumped to its highest levels in almost 40 years last month, slightly outpacing already negative expectations, new data from the U.S. Department of Labor showed.

The Department's Bureau of Labor Statistics reported on Friday that the consumer price index, which measures the cost of goods and services in America, "rose 6.8% for the 12 months ending October, the largest 12-month increase since the period ending June 1982."

The disastrous numbers marked the sixth consecutive month of a year-over-year inflation increase of higher than 5%. In November alone, consumer prices jumped 0.8%. The month before, they increased 0.9%.

Food and energy prices once again led the way.

Energy prices shot up another 3.5% in November, making it a 33.5% surge since November 2020. Gasoline prices alone have skyrocketed 58.1% in that time period, while food prices have gone up 6.1% over the past year.

But even putting food and energy aside, the economic situation still looked bleak, as prices are up across the board.

CNBC reported that "excluding food and energy prices, so-called core CPI was up 0.5% for the month and 4.9% from a year ago, which itself was the sharpest pickup since mid-1991."

The Dow Jones estimate for the month was a 6.7% year-over-year increase.

The New York Times reported that "the rising costs spell trouble for officials at the Federal Reserve and the White House, who are trying to calibrate policy at a moment when the labor market has yet to completely heal from the pandemic, but the risk that price increases could become more lasting is increasing."

The White House and Federal Reserve officials have consistently blamed rising inflation numbers on the persistence of the COVID-19 pandemic, but critics point to supply chain and labor shortage crises under way since the start of President Joe Biden's term.

“There’s no question, no matter how you look at it, even if you take out the extremes caused by the pandemic, it’s still very high inflation,” Randy Frederick, managing director of trading and derivatives at Charles Schwab, told CNBC. “This is still supply chain disruption, semiconductor-related inflation.”

In October, Biden said in a statement that "inflation hurts Americans' pocketbooks, and reversing this trend is a top priority for me."

But a month later, the situation has only gotten worse. The bad news will likely result in more bad polling for the president, who is already under water with voters. Last month, Biden's approval rating sank to just 38%, with many voters citing the economic downturn as a major reason for their disapproval.