Jerome Powell is out — for good reason. Here are 4 of his top blunders.
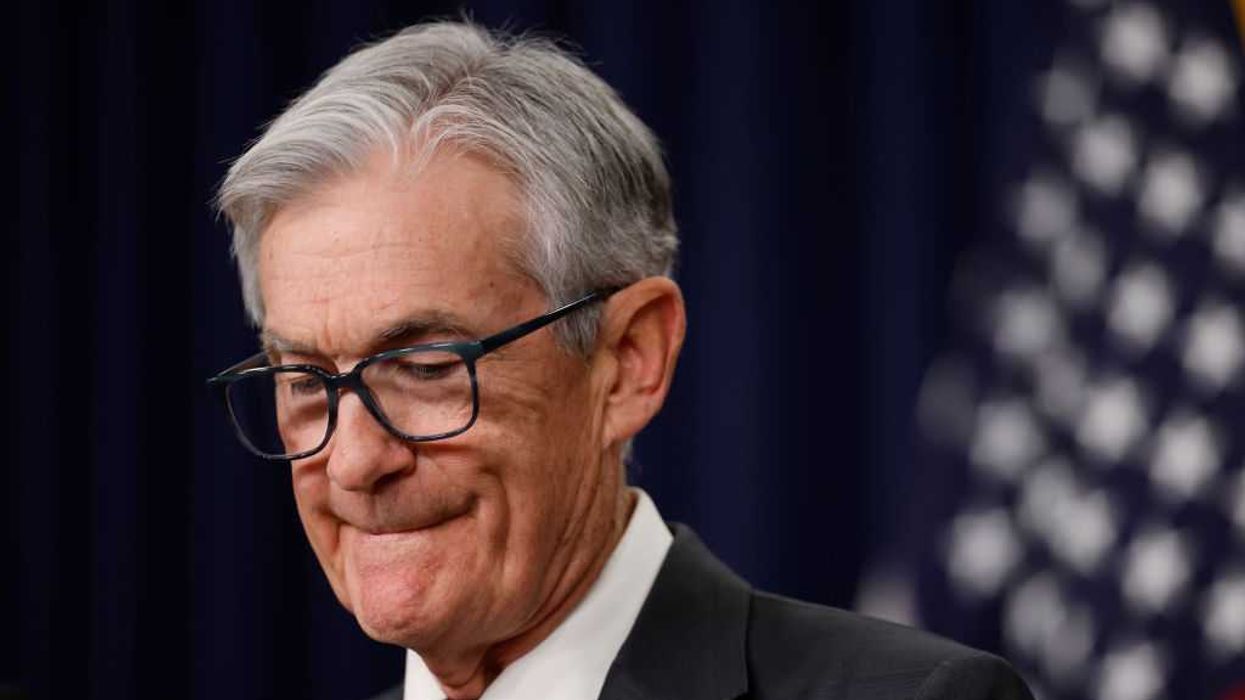


Kevin Warsh, the primary intermediary between the Federal Reserve and Wall Street during the 2008 financial crisis, was confirmed on Tuesday to a 14-year term as Federal Reserve governor and confirmed on Wednesday as Jerome Powell's successor as chairman of the U.S. central bank.

Powell, who was first nominated to the Federal Board of Governors by former President Barack Obama and whose term as chair ends on Friday, wished Warsh well. However, he also provided his replacement with something more valuable than a nice sentiment: examples of what not to do, or at least, what to avoid doing.

Powell has, after all, dropped the ball on numerous occasions — sometimes with catastrophic consequences for the country. Here are just four examples.

1. Don't worry, it's 'transitory.'

Powell stated on March 4, 2021, in the second year of the pandemic, that inflation might increase but that it would likely be "transitory" and not enough for the central bank to raise record-low interest rates — a decision some suspect was geared toward pleasing then-President Joe Biden and thereby securing Powell's reappointment.

'Most of the expected GDP slowdown — from over 3% to 1.5% — was due to Powell's blunder.'

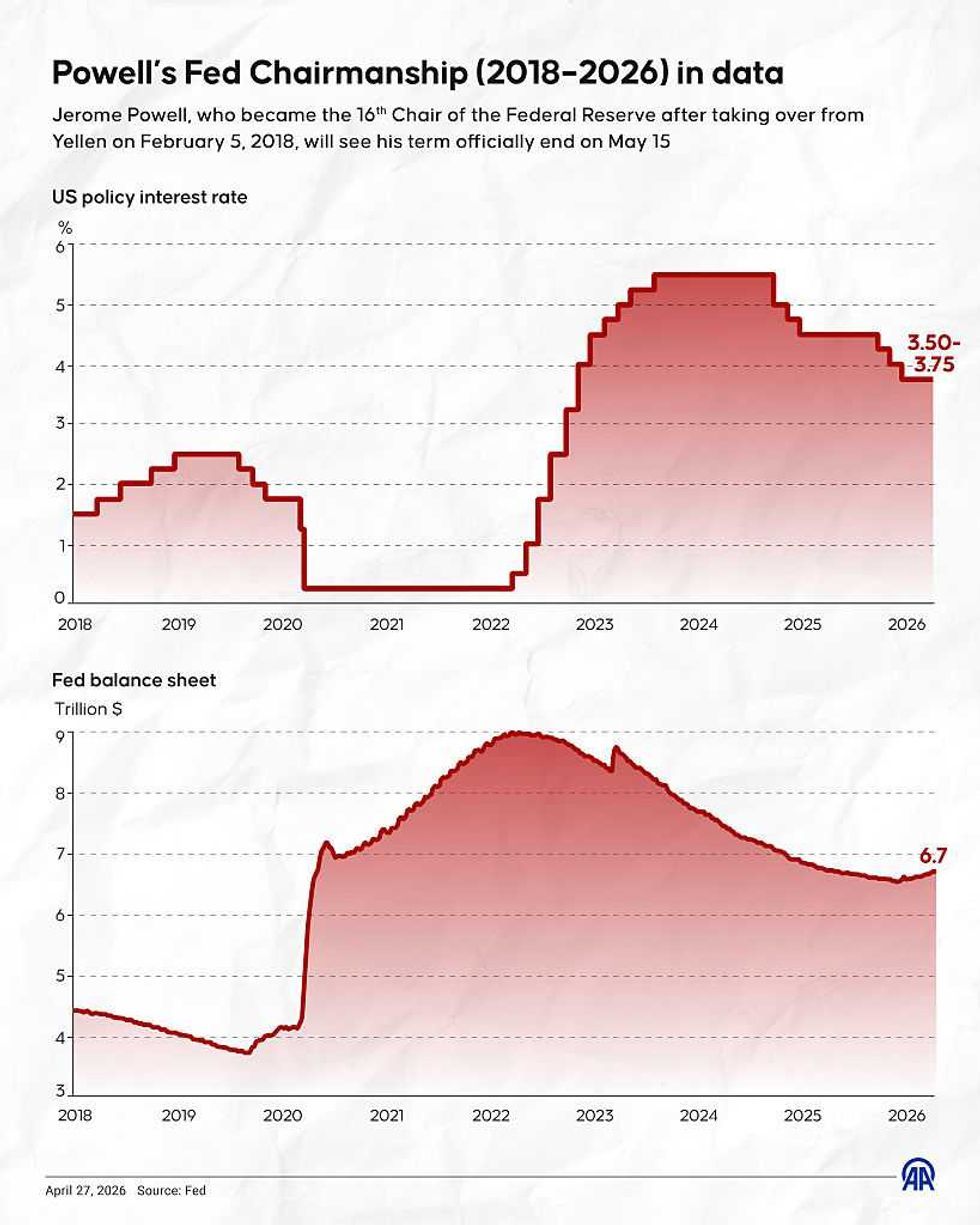
MarketWatch's Greg Robb noted that Powell's wrong-headed "transitory" view of inflation — one that would define his eight years as Fed chair — precluded the Fed from raising interest rates until 2022 while the Fed was also buying up bonds "and swelling its balance sheet."

Thanks to Powell's mistake — which economist Mohamed El-Erian, former PIMCO chief executive, said was "probably the worst inflation call in the history of the Federal Reserve" — the Fed was consistently on the back foot.

RELATED: Your bank can shut you down overnight — here’s how to protect yourself
Elif Acar/Anadolu/Getty Images

Facing the highest inflation Americans had seen in 40 years — inflation that no longer appeared to be "transitory" — Powell ended up raising interest rates 11 times between March 2022 and July 2023, when its benchmark rate reached a range of 5.25% to 5.5%.

Powell told "60 Minutes" in a Feb. 1, 2024, interview:

In hindsight, it would've been better to have tightened policy earlier. I'm happy to say that. Really, it was this. We saw what we thought was that this inflation, which seemed to be mostly limited to the goods sector and to the supply chain story. We thought that the economy was so dynamic that it would fix itself fairly quickly. And we thought that inflation would go away fairly quickly without an intervention by us. That it would be transitory.

Powell leaves office with inflation well above the Fed's 2% target for five consecutive years.

2. Betting against Trump's tariffs, tax cuts

While reluctant initially to raise interest rates when Biden was in office, Powell previously demonstrated an eagerness to raise rates in 2018 when President Donald Trump was in office and the economy was booming.

"Every time we do something great, he raises the interest rates," Trump said at the time. Powell "almost looks like he's happy raising interest rates."

The repeated hikes, which Trump blamed for coinciding stock market turmoil, were supposedly prompted by concerns that the Republican president's tariffs and tax cuts, the latter of which were framed as a $1.5 trillion fiscal stimulus, might together contribute to inflation.

Powell stated that "fiscal policy is becoming more stimulative. In this environment, we anticipate that inflation ... will move up this year."

Economist Donald Luskin, chief investment officer for Trand Macrolytics LLC, recently noted that "there is no evidence that Mr. Trump’s tariffs in 2018 and 2019 led to any inflation at all."

Economist and Trump trade adviser Peter Navarro wrote last year, "Powell's audition for 'worst Fed chair' began shortly after his February 2018 appointment. Promising President Trump in the Oval Office a supportive posture to secure his nomination, Powell instead aggressively raised rates into the low-inflation, high-growth Trump economy. Powell wrongly believed Trump's tax cuts and tariffs would spark inflation — they didn't."

Powell's bet against Trump's tariffs and tax cuts proved consequential.

"As Powell's Fed hiked interest rates four times in 2018 — despite muted inflation and strong labor market gains — economic momentum slowed sharply," wrote Navarro. "According to the Fed's own September Tealbook, most of the expected GDP slowdown — from over 3% to 1.5% — was due to Powell's blunder."

"It would cost the American economy hundreds of thousands of jobs and hundreds of billions of dollars in lost economic output and tax revenues," added the trade adviser.

3. Fed renovation scandal

Powell reportedly greenlit luxury renovations to the Fed's Washington, D.C, headquarters that exceeded the original budget by roughly $700 million and is set to cost around $2.5 billion.

Controversy over the renovations — which include a rooftop terrace with gardens, VIP dining rooms, "premium" marble, and water features — came to a head in January, several months after U.S. Federal Housing Finance Agency Director William Pulte called for an investigation into Powell and his removal as Fed chair.

RELATED: Debit card company promises to pay your bill ... sometimes: 'Buy now, pay maybe'
Sophie Park/Getty Images

Powell said in a Jan. 11 statement that "the Department of Justice served the Federal Reserve with grand jury subpoenas, threatening a criminal indictment related to my testimony before the Senate Banking Committee last June. That testimony concerned in part a multiyear project to renovate historic Federal Reserve office buildings."

An activist Biden-appointed judge quashed the grand jury subpoenas in March.

"Jerome Powell today is now bathed in immunity, preventing my office from investigating the Federal Reserve," Jeanine Pirro, the U.S. attorney in Washington, said in response to U.S. District Court Judge James Boasberg's rulings. "This is wrong, and it is without legal authority."

Last month, the Trump administration dropped the criminal investigation into Powell over his luxury renovation project.

While apparently off the hook, the controversy nevertheless hangs over Powell as another example of costly mismanagement.

4. Bank failures

Powell and his underlings also failed to prevent the March 2023 collapses of Silicon Valley Bank and Signature Bank — the third- and fourth-largest bank failures in American history, respectively.

Powell acknowledged weeks after the bank failures that the Fed's efforts to intervene were too little, too late.

"It does kind of suggest there's a need for ... regulatory and supervisory changes, just because supervision and regulation need to keep up with what's happening," said Powell. "My only interest is that we identify what went wrong here ... make an assessment of what are the right policies to put in place so that doesn't happen again, and then implement those policies."

One of Powell's lieutenants, then-Vice Chair Michael Barr, admitted that the "Federal Reserve supervisors failed to take forceful enough action."

A damning April 28, 2023, report on the Fed's bungled supervision and regulation of Silicon Valley Bank — the conclusions of which Powell ultimately accepted — said that:

  • "Federal Reserve supervisors did not fully appreciate the extent of the vulnerabilities as Silicon Valley Bank grew in size and complexity";
  • "When supervisors did identify vulnerabilities, they did not take sufficient steps to ensure that Silicon Valley Bank fixed those problems quickly enough"; and
  • "The Board's tailoring approach in response to the Economic Growth, Regulatory Relief, and Consumer Protection Act and a shift in the stance of supervisory policy impeded effective supervision by reducing standards, increasing complexity, and promoting a less assertive supervisory approach."
Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

Lloyd Blankfein's Hard Knock Wall Street Life

From a very young age, Lloyd Blankfein, the former chairman and CEO of Goldman Sachs from 2006 through 2018, was destined to work on Wall Street. His commercial instincts first began to show at the age of six when he became the neighborhood market maker for used comic books. By 13, he was selling concession food on commission in the stands at Yankee Stadium. By his formative teenage years, he had developed a transactional approach to life—"sizing up different kinds of people quickly" to see how they could be useful to him and then adjusting his outward persona like a chameleon to get what he wanted.

The post Lloyd Blankfein's Hard Knock Wall Street Life appeared first on .

This law could wipe out your retirement in the next big crash


Most Americans believe a simple thing about their retirement accounts: If you buy a stock, you own it. Your statement shows the shares. The value rises and falls. And if you don’t panic-sell, the asset is yours.

That’s the commonsense view of investing.

If Americans believe they directly own the assets in their retirement accounts, the law should reflect that expectation — before the next crisis tests it.

But the law doesn’t treat your “ownership” the way most people think. In the modern system, most investors are not the direct registered owners of most securities. They hold contractual rights tied to the investment — not the security itself.

In calm markets, that sounds like a technicality. In a severe financial crisis, it could determine whether your assets stay yours.

How we got here

Decades ago, investors could hold securities in their own names. Physical certificates were common, and ownership was straightforward.

As we explain in our new book, “The Next Big Crash: Conspiracy, Collapse, and the Men Behind History’s Biggest Heist,” that changed as powerful financial interests pushed to redesign the securities system. Big banks and Wall Street institutions worked to centralize ownership and reduce investor rights — changes that received little public attention and limited scrutiny.

Today most securities sit inside the Depository Trust Company system. DTC — through its nominee legal entity, Cede & Co. — appears as the direct registered owner of those securities, not you.

DTC is a subsidiary of the Depository Trust and Clearing Corporation, which is owned by the financial institutions that use it. DTCC is not publicly traded, so ordinary investors can’t own its shares.

RELATED: Bidenflation? Trumpflation? Try unipartyflation

DNY59 via iStock/Getty Images

The ‘security entitlement’ system

The DTC structure was only the beginning. In the 1990s, lawmakers revised Article 8 of the Uniform Commercial Code — the state-law framework that governs securities ownership nationwide. Those changes formalized what we now have: an indirect holding system built around “security entitlements,” not direct title.

In plain terms: When you hold most securities through a brokerage account, you hold a legal claim against the broker. You typically do not hold specific, segregated property registered in your name.

That distinction matters because Article 8 also sets priority rules when an intermediary fails. If a brokerage pledges securities credited to customers as collateral for financing, the lender can obtain priority over other claimants. When multiple parties assert rights to the same pool of assets, the law decides who stands first in line — and customers are not always first, even when they paid for the investments and believed they owned them.

In the next major crash, if a Wall Street firm uses customer assets to prop itself up, ordinary investors could take heavy losses. And that can be true even if the firm wasn’t allowed to use customer assets that way. Article 8 was written to protect large institutions first and investors second.

Why ‘protections’ may not protect you

Brokerage firms operate under customer-protection and segregation rules. The Securities Investor Protection Corporation offers limited coverage in certain failures.

But those safeguards don’t erase Article 8’s priority structure. SIPC coverage is also too limited to address widespread losses in a broad crisis. And even when a broker violates rules, a secured creditor’s priority claim can survive unless the creditor itself acted in bad faith or colluded.

In a cascading crisis — multiple failures, margin calls, forced liquidations, and liquidity freezes — these limitations stop looking academic. Article 8 determines whether customer assets remain with customers or flow to institutional creditors.

RELATED: Washington printed promises. Gold called the bluff.

Damian Lemanski/Bloomberg via Getty Images
What investors should understand now

For decades, policymakers sold this transformation as technical modernization. Trading volumes rose. Paperwork bottlenecks appeared. Those problems were real.

But the “solution” did more than speed settlement. It changed who holds legal title and who gets paid first when stress hits.

In ordinary times, the structure runs quietly. Investors see statements, dividends, and confirmations, and few ask how the system records ownership.

The difference becomes decisive when an intermediary fails. At that point, priority rules — not your assumptions — govern what happens next.

What must change

There’s still a path forward.

Because the Uniform Commercial Code is state law, state legislatures can strengthen investor protections and clarify priority rules. Reform doesn’t require blowing up modern markets. It requires aligning the legal structure with what ordinary Americans reasonably believe they own.

The next financial crisis will arrive sooner or later. What’s already set is the legal framework that will govern when it does.

If Americans believe they directly own the assets in their retirement accounts, the law should reflect that expectation — before the next crisis tests it.

SCARY: Economics expert explains what will happen to Americans if our national debt continues to grow


Joe Biden says a lot of crazy things, but perhaps the craziest is his claim that he’s lowered the U.S. deficit, which Stu Burguiere says “couldn’t be farther from the truth.”

Brian Riedl, senior fellow at the Manhattan Institute and an expert in budgeting, taxes, and economic policy, confirms that Biden is indeed lying.

“Last year, the deficit doubled from $1 trillion to $2 trillion – the largest share of the economy in American history, outside of wars and recession,” he tells Stu, adding that despite what Biden says, “the deficit is growing enormously.”

“The president has already added $5 trillion to 10-year deficits if you add up all the legislation he's signed. The fact that he claims he's reducing deficits is completely and mathematically absurd,” he continues.

“I assume what [Biden] is trying to do here is just compare it to peak COVID spending,” says Stu, “which of course is spending that he wholeheartedly approved and actually wanted more of.”

“The proper way to measure deficits is how they're doing compared to the baseline that was already expected by budget estimators,” Riedl says. “When the president took office, the Congressional Budget Office said the deficit will automatically fall to $ trillion and stay there for the next couple of years with the pandemic ending. Instead, [Biden] ran a $2 trillion deficit, so he's growing the deficit above the baseline, not reducing it.”

So just how bad is the situation?

According to Stu, “long-term, this gets incredibly ugly, really, really fast” and is “completely unsustainable.”

Riedl confirms this: “Yes, long-term, the numbers are totally unsustainable. If you assume current policies are extended, the budget deficit is going to go to 14% of GDP per year in a couple of decades. Historically, it's been 3% of GDP. The debt could grow to 200%-300% of the economy, depending on interest rates.”

Those are scary numbers. So what does that mean for the average American when the debt gets that big?

“It means that as much as half to two-thirds of your taxes will go into paying interest on the debt within the next couple of decades,” says Riedl, “and in fact, if interest rates keep rising, there's a scenario in which 100% of your taxes will just go into paying interest on the debt, as it becomes the biggest program in the entire budget.”

Further, granted “the path we're on, middle-class taxes will eventually double.”

“That's the danger of having debt go to 200%-300% of GDP. And that's the situation that the president is doing nothing about and in fact is pouring gasoline on the fire,” Riedl warns.


Want more from Stu?

To enjoy more of Stu's lethal wit, wisdom, and mockery, subscribe to BlazeTV — the largest multi-platform network of voices who love America, defend the Constitution, and live the American dream.

Student Loan And Big Bank Bailouts Won’t Help When The National Debt Crisis Comes

The losses will pile up, and American taxpayers will foot the bill until they no longer can.

Don’t Blame Depositors For Bank Failure, Blame Biden And SVB Management

It’s important to understand that SVB’s failure didn’t arise from risky startups doing risky startup things.
'De facto bailout of the banking system': Yellen says no bank bailouts, but Big Four reportedly set to grab $210 billion as tech elites get propped up


A California bank that long served tech elites and affluent venture investors collapsed on Friday, amounting to the greatest financial institutional failure since Washington Mutual went bankrupt in 2008.

While Biden officials have suggested that there will not be bailouts comparable to those enjoyed in the late 2000s, the Big Four banks will reportedly see a bailout by another name of roughly $210 billion, while the U.S. government makes wealthy tech workers whole again.

What is the background?

The New York Post reported that Silicon Valley Bank had $209 billion in assets as of Dec. 31, 2022, and was the 16th-biggest bank in the United States. Silicon Valley tech start-ups, venture capital firms, and corporate behemoths deposited at the bank and used its services.

The bank was adversely impacted by the downturn in technology stocks over the past year as well as by the Federal Reserve's endeavor to hike interest rates.

USA Today noted that in recent years, SVB bought billions of dollars' worth of purportedly "risk-free" bonds using depositors' cash. However, the value of these investments has significantly dropped because they now pay lower interest rates as compared to bonds issued today.

Since coastal tech elites and other California customers were hit hard by the downturn, they needed cash. Many began trying to withdraw all at once, prompting SVB to sell off its assets at a loss.

The bank was unable to raise additional capital through outside investors.

Amid liquidity concerns and share losses around $52 billion, regulators shut down the bank Friday, thereby protecting insured deposits and those remaining assets at the bank.

Centralists intervene

Treasury Secretary Janet Yellen claimed Sunday that unlike the big bank bailouts in 2008, Silicon Valley Bank and Signature Bank — a New York financial institution similarly brought to the brink of collapse last week — will not receive similar treatment in the aftermath of their breakdowns. The U.S. government will, however, reportedly be helping their affluent depositors.

Citing "systemic risk" as justification for extraordinary actions, the Treasury Department, Federal Deposit Insurance Corp., and the Federal Reserve have indicated that they will use the FDIC's insurance funds to prevent tech elites and other depositors in the failed banks from losing money, reported Axios.

"Today we are taking decisive actions to protect the U.S. economy by strengthening public confidence in our banking system. This step will ensure that the U.S. banking system continues to perform its vital roles of protecting deposits and providing access to credit to households and businesses in a manner that promotes strong and sustainable economic growth," wrote Yellen, Federal Reserve Board Chair Jerome H. Powell, and FDIC Chairman Martin Gruenberg in a joint statement.

According to the trio, depositors will have access to all of their money as of March 13. The trio noted that no losses associated with the "resolution of Silicon Valley Bank will be borne by the taxpayer," but rather will be funded by fees on the banks.

Similar action will be used to bolster Signature Bank.

Whereas depositors, characterized in this case by USA Today as businesses and wealthy tech workers, will be protected up to $250,000 each, shareholders and certain unsecured debt holders are on their own.

Extra to these actions, the Federal Reserve indicated Sunday that it will "make available additional funding to eligible depository institutions to help assure banks have the ability to meet the needs of all their depositors."

Accordingly, the Fed has introduced a new lending program called the Bank Term Funding Program, enabling banks to take out advances from the Fed for up to a year.
Ben Eisen, writing the Wall Street Journal, noted that in exchange for these advances, banks must pledge "Treasurys, mortgage-backed bonds and other debt as collateral. By allowing banks to pledge their bonds, they can meet customer withdrawals without having to sell their bonds at a loss, which is what Silicon Valley Bank did last week, sparking a run on the bank."

"The biggest draw of this facility is that banks can borrow funds equal to the par value of the collateral they pledge," wrote Eisen. "This means that the Fed won't look to the market value of the collateral, which in many cases reflect big unrealized losses due to the jump in interest rates."

"That is a boon for banks, who were sitting on some $620 billion in unrealized losses on securities at the end of last year," added Eisen.

Should the banks fail to repay their advances, the Treasury Department, with President Joe Biden's blessing, is promising $25 billion in credit protection to the Fed just in case.

'De facto bailout'

ZeroHedge reported that contrary to Yellen's suggestion, the Big Four banks are effectively getting a $210 billion bailout.

None
— (@)

The editorial board at the Wall Street Journal concurred, writing that the guarantees for wealthy California tech magnates' uninsured deposits and the Fed's loans to big banks are together "a de facto bailout of the banking system, even as regulators and Biden officials have been telling us that the economy is great and there was nothing to worry about."

The board noted that the legality of the depositor end of the alleged bailout is unclear, since "Congress set the $250,000 insured limit to protect average Americans, not venture investors in Silicon Valley."

As for the one-year advances, the "Fed is essentially guaranteeing bank assets that are taking losses because banks took duration risk that Fed policies encouraged. This too is a bailout."

"Democrats and the press corps may try to pin the problem on bankers or the Trump Administration, but these are political diversions. You can’t run the most reckless monetary and fiscal experiment in history without the bill eventually coming due," added the board.

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

The Russian central bank takes steps to stabilize the ruble as it plummets in value


The Bank of Russia is proceeding with emergency measures to stabilize its economy and to prevent the Russian ruble from losing further value.

For the first time, the Russian central bank said that it will intervene in the foreign exchange market and expand its Lombard list of securities that it will accept as collateral, Bloomberg reported.

The central bank did not mention whether or not it would raise interest rates but it did proceed with agreeing to provide Russian banks with additional liquidity. It is preparing to offer banks 1 trillion rubles — roughly $11.5 billion —in an overnight repo auction.

On Thursday, Russian President Vladimir Putin, ordered Russian forces to launch their invasion of Ukraine and strike strategic targets to demilitarize the country. Upon doing so, the ruble fell to a record low in value.

In response to Russia’s invasion of Ukraine, leaders of Western nations are implementing a wide array of sanctions to weaken the Russian economy.

Less than a day after the Russian invasion of Ukraine began, President Joe Biden announced that the United States would target Russia’s largest financial institutions, Sherbank and VTB, to prevent them from using the American financial system to conduct transactions. These sanctions are fairly comprehensive and will restrict nearly 80% of Russian banking assets.

Previously, Biden stopped short of calling for Russia’s removal from the Society of Worldwide Interbank Financial Telecommunication (SWIFT).

Biden said, “It is always an option, but right now it’s not the position the rest of Europe wishes to take.”

Kicking Russia out of SWIFT would greatly damage the Russian economy in the short term and make recovery incredibly difficult in the long term. It could prevent Russia from engaging in international transactions and would cripple their ability to export oil and gas.

On Saturday, the allied leaders of several Western countries — including the Untied States — expressed their support for preventing Russia from being able to access and utilize the SWIFT network.

The Western leaders agreed to target specific Russian banks for removal from the SWIFT system, to prevent the Russian central bank from manipulating its monetary policy, and to take aggressive steps to sanction and financially punish Russian individuals involved in the invasion of Ukraine.

By preventing Russia from using the SWIFT network, the West will effectively isolate them and inhibit them from conducting trade with some of its largest trade partners.

At the time of writing, a Russian ruble is worth about 0.012 U.S. dollars. The in-game currency for the popular children’s videogame “Roblox” – aptly named Robux – is worth about 0.0125 U.S. dollars per unit.

Why Are Democrats Hurtling The United States Towards A Stock Market Crash?

Despite recent hedge fund disasters and almost every economic indicator pointing to a potential stock crash, Biden’s administration has completely ignored a potential equities bubble.