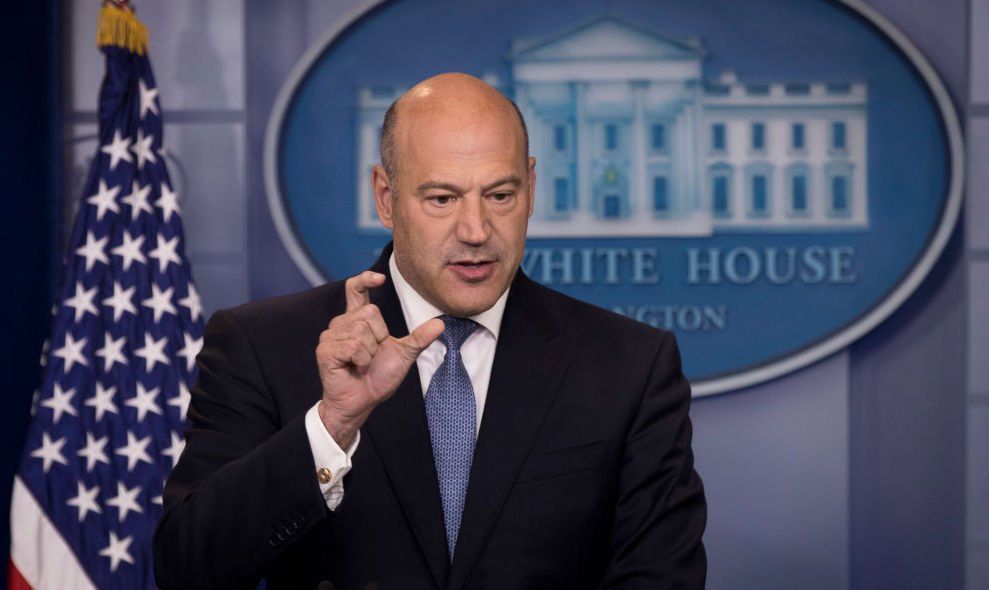It’s the economy, stupid — again
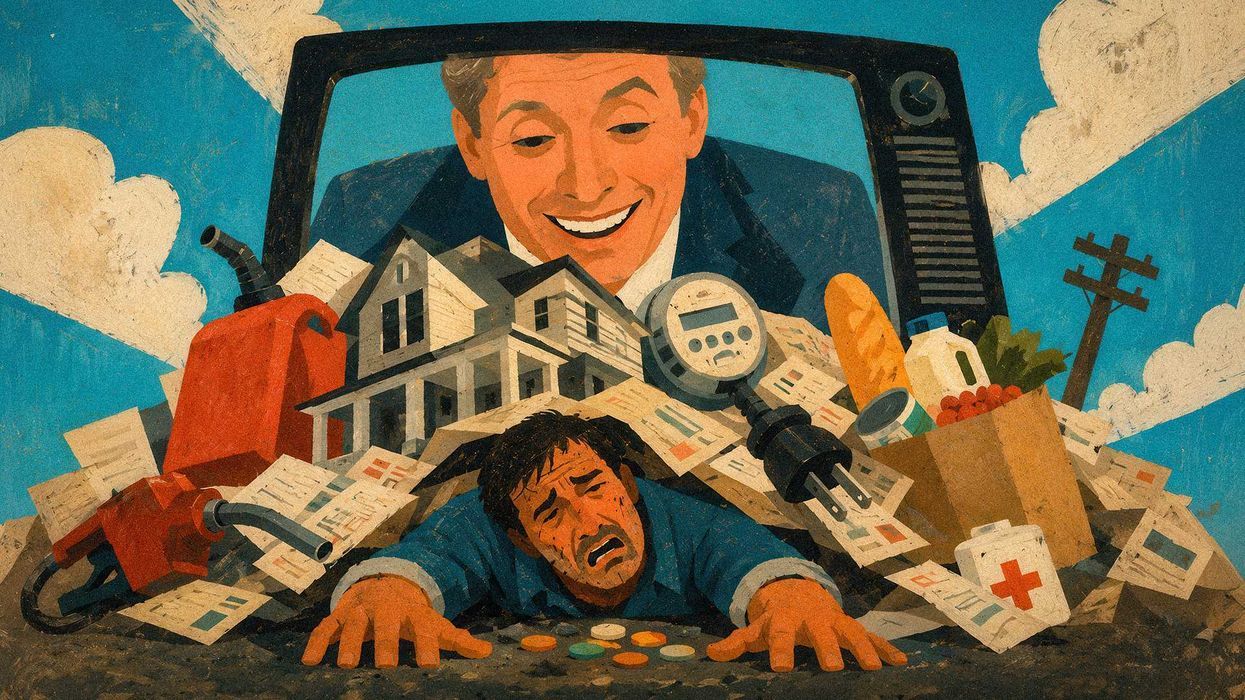


The conservative political class is committing one of the most disastrous acts of political malpractice in recent memory.

When Biden press secretary Karine Jean-Pierre chided Americans for complaining about the price of staples such as milk and eggs, she did serious damage to the Democratic Party. Many voters backed Donald Trump because they trusted him to address inflation and the broader affordability crisis. Now conservative pundits and influencers are repeating the same mistake, telling consumers that everything is fine and that only economic illiterates think groceries, gas, and housing cost too much.

Democrats lost because they cut themselves off from reality. Republicans have no reason to copy the strategy.

Elections are not won by lecturing voters that their problems are imaginary. This is Politics 101. Professional political actors adopting the strategy months before the midterms is both bizarre and dangerous.

Affordability is not a Democrat talking point or a socialist catchphrase. It is real, and it will dominate every foreseeable election. Republicans understood this when Biden occupied the White House. The problem did not disappear when Trump returned.

People can feel that the economy is not working for them. They can see the American dream drifting farther out of reach. Conservative pundits may produce charts, cite aggregate statistics, and explain that certain indicators look healthy. None of that will save the GOP any more than it saved Democrats who insisted that “Bidenomics” was working.

The party cannot dismiss this anger as a failure of messaging. Voters do not experience the economy as an abstraction. They experience it at the checkout counter, at the gas pump, when the insurance bill arrives, and when another year of saving still leaves a starter home beyond reach. Their judgment is concrete and entirely rational.

The price of some discretionary goods, such as flat-screen televisions, may have fallen. The essentials of ordinary life have not followed the same path. Food, health care, child care, education, insurance, housing, electricity, and gasoline remain punishingly expensive. Gross domestic product and a surging stock market may comfort those already winning in the economy, but they are poor measures of the daily experience of a family struggling to stay afloat.

Many of the underlying problems are nearly untouchable in a democratic system. The hard truth is that buying votes is often the optimal electoral strategy. No candidate wins by promising voters that their benefits will shrink, their home values will fall, and their taxes will rise.

Trump understands this better than anyone. He promised not to touch major entitlements, pledged to protect home values, and proposed eliminating taxes on tips. America may be on a slow collision course with fiscal disaster, but no politician wants to lose an election by volunteering to hold the bomb when it explodes.

RELATED: Stop ‘owning the libs’ and start owning institutions
Blaze Media Illustration

The American version of this problem has modern features, but the core dilemma is ancient. Large civilizations require immense resources. When rulers can no longer obtain enough through ordinary taxation, they manipulate the currency.

Roman emperors knew little of modern monetary theory, but they understood that reducing the precious-metal content of coins allowed the state to mint more of them. The apparent solution eventually helped destroy confidence in the currency and contributed to the collapse of hard money across much of Europe.

There is only so much Trump can do about structural inflation and accumulated debt. He can, however, avoid taking actions that make the problem worse.

Gasoline is the literal fuel of the economy. Higher prices punish voters at the pump and then reappear in the cost of every product that must be transported. Energy bills, food prices, and fuel costs hit households immediately and simultaneously. Voters will remember that squeeze more clearly than any lecture about macroeconomic fundamentals.

The war with Iran has taken on a disturbingly familiar shape. Its champions mocked anyone who warned that the conflict might last more than a few weeks. Now the country approaches a critical midterm election with no end in sight.

This was predictable. Once a war begins, the ability to control its scope and duration rapidly diminishes. Machiavelli put it plainly: “Wars begin when you will, but they do not end when you please.”

The same pundits who demanded war now tell voters they are stupid or selfish for noticing its economic consequences. They will inevitably blame any disastrous midterm result on the people who opposed the conflict, but the political reality is obvious.

The central issue is not that voters have developed a sophisticated position on Iran. Many probably care little about the strategic details. They care that everything costs more. Telling them they lack economic literacy has roughly the same electoral appeal as shooting a puppy on live television.

America has already spent tens of billions of dollars on the Iran war and depleted munitions stockpiles that will require years and billions more to rebuild. The Republican House also approved another $8 billion in loans for Ukraine, despite Trump’s promise to end that war immediately.

RELATED: Conservatives are blowing the easiest political win in America
Blaze Media Illustration

The United States does not have this money sitting in a vault. It must be taxed, borrowed, or created. Each method imposes a cost on Americans who receive little material benefit from these foreign conflicts.

The political system limits what Republicans can do about inflation. Ending vast expenditures on wars that do not improve the lives of voters is nevertheless the most obvious place to begin.

The road ahead is difficult, but many of the wounds are self-inflicted. The first step toward recovery is to stop repeating the behavior that caused them.

End funding for the war in Ukraine. Bring American forces home from the Persian Gulf. Stop telling voters that concern over rising prices is foolish, greedy, or manufactured by Democrats.

The GOP still has one advantage: Democrats remain deeply unpopular. Redistricting has improved the Republican electoral map, and the left continues to repel many ordinary voters. There may still be time to limit the damage or even regain momentum.

But first the war hawks must admit that they were wrong — again — and change course.

Democrats lost because they cut themselves off from reality. Republicans have no reason to copy the strategy.
What the stock market sell-off really says about the US economy


The stock market has been on a serious roller coaster ride this week after false reports that President Trump was pausing his reciprocal tariffs for 90 days began making the rounds on the news and social media.

“We were watching it bounce back, and then all of a sudden it dropped back down again,” Glenn Beck of “The Glenn Beck Program” comments. “Not sure what happened until we checked the news. It seems like all of these media organizations reported an interpretation from some social media user.”

The social media user has posted an analysis of what a Trump official, National Economic Council Director Kevin Hassett, said in an interview, which is what the media then latched on to.


“He was asked by Brian Kilmeade, ‘Would Trump consider a 90-day pause?’ And Hassett said, ‘I think the president’s going to decide what the president is going to decide,’” Stu Burguiere explains.

“There’s no pause, and so now the market’s down again,” he adds.

“What’s going on in our economy is bogus. It’s all this bogus money that the Fed keeps printing and putting into the system with 0% interest rates. It’s all funny money. The stock market is no longer tied to anything real, and everybody just bypassed that and went, ‘Wow, things are really good, things are really good,’” Glenn explains.

“No,” he continues. “It was all bogus. All of that is bogus.”

Want more from Glenn Beck?

To enjoy more of Glenn’s masterful storytelling, thought-provoking analysis, and uncanny ability to make sense of the chaos, subscribe to BlazeTV — the largest multi-platform network of voices who love America, defend the Constitution, and live the American dream.

How your wallet is paying for the government’s spending binge


The Treasury Department has released the receipts for federal spending in fiscal year 2024, revealing staggering numbers. While the $1.8 trillion deficit may seem less alarming than a $2.3 trillion shortfall, the Treasury accounted for an extra $500 billion in deficits in the opening days of fiscal year 2025 to achieve that figure. Regardless, neither the Federal Reserve nor the Treasury Department can escape the impact of these numbers. We have now reached a point where permanent stagflation seems unavoidable.

The Treasury Department’s final tab for fiscal 2024 shows a $1.83 trillion deficit, setting a near record aside from the unusual pandemic years of 2020-2021. This means the government borrowed $5 billion per day — the equivalent of the FBI’s entire annual budget a generation ago. In the third quarter of this calendar year (the final quarter of fiscal 2024), the deficit equaled 6.3% of GDP, a level only surpassed during World War II and the COVID-19 pandemic.

Republicans have failed to convey to the public that the government spending they rely on comes at a painful cost.

Despite relatively low unemployment and the absence of a world war, the government took in a record $4.918 trillion in revenue but still amassed a mammoth deficit. This gap is poised to grow in the new fiscal year, meaning that when a recession officially hits, the deficit could become colossal. Although the government collected $479 billion more in revenue than last year, it increased the deficit by spending an additional $617 billion. Imagine what the deficit might look like if revenue starts to decline.

In the past, we shrugged off such news, dismissing it as mere red ink on a spreadsheet. But that was when annual interest on the debt cost only $200 billion. Now, we’re on track to spend a record $1.133 trillion — or nearly a quarter of our tax revenue — just on interest. Debt interest is now more costly than every government expense except Social Security, contributing to the crippling inflation consumers face. We’re no longer mortgaging our grandchildren’s future; we’re destroying our own.

To cover this interest, the government must sell a record number of treasury bonds each month. With countries reducing their holdings of U.S. Treasuries and buying gold instead, treasury yields are rising unnaturally. Despite a drop in the federal funds rate, rising spending and the resulting debt service push yields higher. This shift has caused gold and treasury yields to surge simultaneously — a rare occurrence, as they typically move inversely. It’s also why the 30-year fixed mortgage rate has climbed nearly a full percent since the Federal Reserve cut rates by 50 basis points. T. Rowe Price forecasts that the 10-year Treasury yield could hit 5% over the next six months, approaching levels seen in late 2007 on the eve of the Great Recession.

When yields go up, debt servicing costs increase further, and the Fed has to print even more money to cover both the rollover debt and rapidly accumulating new debt — rising faster this year than last. Under this baseline scenario, inflation is bound to worsen. The global money supply now stands at $89.7 trillion, up by $22 trillion since COVID. After shrinking in 2022-2023, M2 is now expanding rapidly and is currently 38% higher than pre-COVID levels. Consumers are already struggling with high prices, and every market indicator signals a new round of even higher costs.

Consumers have exhausted their resources ahead of an impending financial collapse, spending $2.3 trillion in excess savings over the past three years to cope with the cost of living. Currently, cumulative excess savings are negative $216 billion, with U.S. credit card debt and interest rates at record highs.

Even without the threat of hyperinflation, these economic indicators always precede a crash. The unprecedented rallies in gold and silver are clear warnings, signaling grave danger. They indicate that the Federal Reserve, in its attempts to curb recession and inflation while printing money recklessly, has lost control, leaving us to face the consequences of both.

Republicans have failed to convey to the public that the government spending they rely on comes at a painful cost. It’s not just the $103,700 in debt that each American is responsible for in some distant future. It’s the additional tens of thousands they will pay each year to maintain their parents’ standard of living for the rest of their lives — and that’s assuming things don’t get worse.

Biden’s $2 trillion deficit proves the ‘strong economy’ is a lie


Agenda-driven economists and Democratic Party mouthpieces keep repeating one claim: The economy is strong. But financial strength can often be deceiving.

We’ve all seen that family with the big, beautiful home, fancy cars, designer clothes, and a country club membership. At first glance, they seem to be doing well, right? But if they’ve bought all of that with large amounts of debt, they aren’t financially secure. They are simply creating an illusion of wealth, and eventually, that catches up with them.

You can’t say the economy is strong, when the fiscal foundation underneath it is full of cracks, smoke, and mirrors.

That’s exactly what the U.S. government has been doing — creating the illusion of economic growth by financing it with increasing amounts of debt. From the outside, it appears as if the economy is thriving, which is why certain economists and propagandists continue to push the narrative that it’s rock-solid. However, a quick glance at the numbers tells a different story.

The national debt, now nearly $35.5 trillion, is estimated to exceed 120% of GDP. Major financial entities suggest that for stability, it should be around half that amount.

Under Joe Biden and Kamala Harris, credit rating agencies, which are often slow to reveal the severity of fiscal crises, have downgraded the national debt rating multiple times.

We are now paying more than $1 trillion per year in interest expenses, meaning the cost of financing what we’ve already “bought” exceeds what we spend on national defense. This recalls Niall Ferguson’s maxim: “Any great power that spends more on debt service than on defense will not stay great for very long.”

Adding to this growing debt burden is a massive deficit. While we have historically run large deficits relative to GDP during times of war or emergency (or so-called emergencies like COVID), the Biden-Harris administration is running wartime-level deficits — around 7%-8% of GDP, which is double the historical average — during a period without a direct war and with a supposedly strong economy.

The more than $2 trillion deficit becomes even more alarming when you consider that the government took in over $5 trillion in revenue in the latest fiscal year. This is not only a record amount (compared to $3.46 trillion just five years ago), but it also exceeds the GDP of every country on Earth except the United States and China.

What the government is doing mirrors the extravagant family mentioned earlier — creating the illusion of a strong economy by taking on massive debt. The deficits are inflating the appearance of growth at an enormous cost.

The government has also received a boost from struggling consumers, who are taking on record levels of personal debt and dipping into their savings.

You can’t say the economy is strong, when the fiscal foundation underneath it is full of cracks, smoke, and mirrors.

The economists then want to change the subject, looking at increasing housing prices and stock portfolios.

This isn’t the strong argument that’s being presented. Asset inflation started before the rise in the cost of living. While this benefits those who hold assets, it does nothing for wage earners struggling to cover basic living expenses. All it has done is widen the gap between the “haves” and the “have-nots,” and history shows that such a divide is unhealthy.

The economy isn’t working well for everyone. Where it does appear to be working, it’s happening at a massive and unsustainable cost.

What happens when the Joneses can no longer keep up with themselves? It could very well collapse the global economy. We need to confront reality instead of buying in to the illusion.

Snickers fires back at Joe Biden's claim that the company is duping customers with 'shrinkflation'


Snickers is contradicting President Joe Biden's claim that the size of its candy bars are being secretly reduced.

In his State of the Union address last Thursday, Biden accused snack companies of shrinkflation, a process whereby a manufacturer includes less product in packaging while not adjusting the price.

"Look, too many corporations raise prices to pad their profits, charging more and more for less and less. That's why we’re cracking down on corporations that engage in price-gouging and deceptive pricing, from food to health care to housing," Biden said. "In fact, the snack companies think you won’t notice if they change the size of the bag and put a hell of a lot fewer — same size bag — put fewer chips in it. No, I’m not joking. It's called shrinkflation."

Biden then specifically targeted Snickers.

"You probably all saw that commercial on Snickers bars. You get charged the same amount and you got about, I don’t know, 10% fewer Snickers in it," he claimed.

— (@)

But Mars Inc., the candy company that manufactures the Snickers bar, released a statement accusing Biden of not telling the truth.

The statement read:

We have not reduced the size of Snickers singles or share size in the U.S. Like many industries, we continue to face high inflation and spikes in material costs; however, we work to absorb these extra costs wherever possible to provide affordable treats and the best value. Final prices are always at the discretion of the retailer, but we make every effort to minimize costs to provide a full range of delicious products.

Biden is targeting shrinkflation as his newest economic enemy because his narrative about inflation — that it is consistently improving and the crisis is over — collapses under scrutiny.

On Tuesday, the Bureau of Labor Statistics reported that inflation is not improving.

Inflation, in fact, rose 0.4% in February and 3.2% over the last 12 months, the BLS announced. Meanwhile, core inflation — a measure of inflation minus food and energy — also increased 3.8% over the last year.

Both metrics reflect the pocketbook squeeze that Americans continue to feel. Yes, inflation is not at 9% like it was two years ago. But the price of goods is still increasing, no matter what the president says.

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

Democrat economist gets honest about the inflation crisis and why that's not good for Biden's narrative


Economist Gary Cohn, a Democrat, is refusing to let President Joe Biden pull the wool over Americans' eyes.

To help Biden win re-election, the Biden administration is promoting a narrative about the economy that is more bark than bite. For example, at his State of the Union address last week, Biden minimized inflation, claimed to have created "15 million new jobs," and blamed corporations for the high prices of goods, which he calls "shrinkflation."

But the truth is not the rosy picture that Biden painted, Cohn said Sunday on CBS News' "Face the Nation" — especially when it comes to inflation.

"Inflation has a compounding effect. Meaning, as you look at inflation year over year, you're adding up those numbers. You're not starting at a zero every year," Cohn explained. "If we had 6% inflation last year and now we have 4% inflation, that's 10% inflation."

Because "there's a huge cumulative effect to inflation," Cohn said that in his scenario of 10% inflation, that means a basket of groceries that once cost just $100 now costs over $125 because inflation increases "add up."

"So, when people are being told, 'Consumers, you're wrong, inflation's heading [down]—' no, they're right, it is actually more expensive?" host Margaret Brennan followed up.

"They're completely right. They're completely right," Cohn responded.

Not only is inflation cumulative, but what Biden doesn't tell you is that shrinking inflation does not mean prices of goods also decrease. Instead, prices continue to increase, but at a smaller rate. This is an important distinction, and it's where Biden's positive message about inflation gets lost in reality. Prices aren't going down, and the purchasing power of the dollar has been diminished.

For all of Biden's talk about inflation decreasing, groceries cost Americans 25% more today than in January 2020.

This is why poll after poll shows that Americans are dissatisfied with Biden's economic record. Combine inflation with high interest rates, which the Federal Reserve justifies to control inflation, and you get a bad recipe for re-election.

"People were losing purchasing power, and that's why people were angry," Cohn said of the inflation crisis. "And then take on top of that the high interest rate environment where, if you thought you might have been in a position to buy a house because you saved money, you go out to get a mortgage at 7% or 8%, you can't afford a house.

"People got very frustrated because the costs of their everyday lives got very expensive and the cost of investing in their future by buying a home got nearly impossible," he explained

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

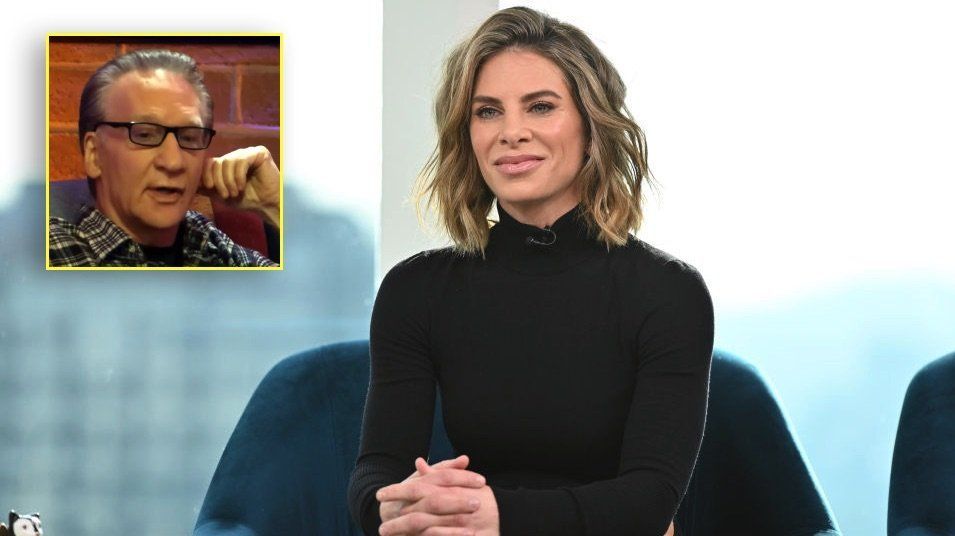
Jillian Michaels puts Bill Maher in his place for defending Biden's post-COVID economy: 'Buy some f***ing eggs!'


Fitness guru Jillian Michaels reality-checked Bill Maher in a recent episode of his own podcast about the inflation crisis and the state of the economy.

Following a lengthy conversation about the COVID-19 pandemic and health, Maher repeated what he recently read in a newspaper about the economy, though he did not specify which periodical.

"Isn't it amazing to you?" he asked Michaels. "This country came out of the pandemic way better. We won the pandemic economically."

But Michaels, a trainer best known for being a star on the reality show "The Biggest Loser," immediately called out what she believed was Maher's distorted view of reality.

"We did? God, I don't feel that way. Explain it to me. I feel like inflation is insane," Michaels responded.

"Inflation is not insane," Maher claimed.

"Bill, go buy a car. A house has tripled here," Michaels fired back. "Buy some f***ing eggs!"

Maher suggested in response that "feelings" are driving fears about inflation and the economy, arguing "the numbers" prove those emotions are incongruent with reality. However, Maher did not cite any data to back his claims.

It's true that inflation has cooled significantly from the crisis experienced nearly two years ago when inflation reached record levels. But that doesn't mean prices of goods are dropping. Rather, it means that prices are not increasing as quickly as they were.

The latest analysis from the Bureau of Labor Statistics found that inflation "increased 0.3 percent in January on a seasonally adjusted basis" to 3.1%. Core inflation — which measures all inflation minus volatile food and energy — is at 3.9%, a more telling metric. Both figures are significantly above the Federal Reserve's targeted rate of 2%.

Reality aside, Michaels' response also demonstrated that Maher, a rich celebrity, is out of touch with the economic concerns of average Americans.

— (@)

Later in the episode, Michaels explained why she moved from California to Florida.

Not only is Florida "less crazy," but Michaels described an incident during the COVID-19 pandemic in which a criminal released from jail because of the pandemic reoffended, targeting her home in Malibu.

"Long story, but third strike, guy goes to jail, gets let out during COVID," she said. "I mean, give me a f***ing break!"

Michaels — who admitted she "couldn't have been more left" before the pandemic but now sees herself as a political centrist — repeatedly bashed Gov. Gavin Newsom (D) and California's leaders in the interview. She said they are "decriminalizing everything" and "prioritizing crazy s***."

She also admonished Maher for supporting Newsom, who defended the governor's pandemic hypocrisy. Newsom, Michaels said, is a "hypocrite" who refused to follow his own "absurd" pandemic rules.

"He didn't follow his own rules," Michaels said. "If you're going to be a leader, you lead by example."

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

So was it a lie? Biden admits he regrets name of 'Inflation Reduction Act' because it doesn't reduce inflation


President Joe Biden expressed regret for the name of the Inflation Reduction Act on Thursday, admitting the law does not actually reduce inflation.

"I wish I hadn't called it that, because it has less to do with reducing inflation than it does to do with dealing with providing for alternatives that generate economic growth," Biden said in Utah, according to a White House pool report.

Biden signed the Inflation Reduction Act into law one year ago at the height of the inflation crisis.

The law was promised to help reduce inflation — as its name says — but immediately after Biden signed it, the media admitted what the bill was really about: not inflation, but climate and health care. Politico, for example, called it a "sweeping climate and health care" bill, while the Washington Post described it as a "sweeping bill to tackle climate change, lower health-care costs."

The Congressional Budget Office, moreover, estimated the bill would have no meaningful impact on inflation. The agency wrote in a letter last year:

In calendar year 2022, enacting the bill would have a negligible effect oninflation, in CBO’s assessment. In calendar year 2023, inflation wouldprobably be between 0.1 percentage point lower and 0.1 percentage pointhigher under the bill than it would be under current law, CBO estimates.

The bill only passed the Senate because Sen. Joe Manchin (D-W.Va.) agreed to vote for it. In April, he expressed buyer's remorse for doing so. But he told the Washington Examiner this week that he stands by the law.

The inflation crisis has mostly subsided, though inflation ticked up to 3.2% in July from 3% in June. The Federal Reserve, which has continued to raise benchmark interest rates to control inflation, targets an inflation rate of 2%.

Core inflation — which measures inflation of all goods minus volatile food and energy — remains at a dismal 4.7%.

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

KJP claims Americans 'feel better' about their finances thanks to Biden — then pesky facts get in the way


White House press secretary Karine Jean-Pierre was fact-checked Monday after claiming Americans are more financially confident thanks to President Joe Biden.

At the press briefing, CNN reporter Jeremy Diamond asked why the White House is boasting about "Bidenomics," citing polling that shows an overwhelming majority of Americans disapprove of Biden's handling of the economy.

"Is there a risk that this new branding could backfire?" the reporter asked.

But if Jean-Pierre's response is any indication, it's clear the White House does not believe its fantasy narrative will backfire.

"Look, 13 million jobs. Again, when you think about how Americans feel better about their personal finances, that is important," she said. "When you think about wages are going up, when you think about the really good paying, millions of good paying jobs, that union jobs that his policies are going to create, all the things are really incredibly important. So the president's going to continue to speak to that."

06/26/23: Press Briefing by Press Secretary Karine Jean-Pierre youtu.be

What was the response?

Jean-Pierre's assertion went viral on social media precisely because it shows the disconnect between reality and the Biden administration's narrative.

  • "What world is she living in? Inflation is the highest it’s been in 40 years. Nearly 80% of Americans think the country is headed in the wrong direction.A vast majority of Americans can’t find $1k in emergency funds. Biden has FAILED America," Rep. Wesley Hunt (R-Texas) responded.
  • "Gaslighting at its finest. 3/4 people believe the country is on the wrong track (74%)," Rep. Max Miller (R-Ohio) responded.
  • "Prices have increased 15.5% and real wages have decreased 3.2% since President Biden took office.Americans are getting crushed because of Biden's policies," Rep. Guy Reschenthaler (R-Penn.) pointed out.
  • "The only people in America who feel better about their personal finances are the Biden Crime Family," Rep. Bob Good (R-Va.) quipped.
  • "Stock market is down, food cost are up, rent is up, gas is up, savings are going down……. I feel so much better," another person mocked.

It's not true that Biden has created 13 million jobs. While the economy may have added that many jobs since Biden became president, the vast majority of those jobs represent people who returned to the workforce after pandemic lockdowns.

Inflation, meanwhile, is still high at 4% — twice the Federal Reserve's targeted rate, while American households are carrying more debt and less savings. Corporate bankruptcies and foreclosures are up too.

None of these are metics of a thriving economy. Indeed, only one-third of Americans approve of Biden's job on the economy while even fewer (24%) believe the economy is in good shape, a recent Associated Press-NORC poll found.

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

'That's why': Biden can't hide his annoyance when reporter confronts him about taking blame for inflation crisis


President Joe Biden declared Friday that he takes no responsibility for the inflation crisis that unfolded under his watch.

Following a speech about the economy and a glowing January jobs report, one reporter managed to ask Biden whether, regarding the inflation crisis that has plagued Americans for more than a year, the buck stops with him.

"Do you take any blame for inflation, Mr. President?" the reporter asked.

"No," Biden responded.

When the reporter pressed him for his reason, Biden replied, "Because it was already there when I got here, man."

"Remember what the economy was like when I got here? Jobs were hemorrhaging. Inflation was rising. We weren’t manufacturing a damn thing here. We were in real economic difficulty. That's why I don't," he added, clearly annoyed by the question.

\u201cBIDEN: "Do I take any blame for inflation? No." \n\nREPORTER: \u201cWhy not?\u201d \n\nBIDEN: \u201cBecause it was already there when I got here, man.\u201d \n\nInflation was 1.4% when Biden took office.\u201d
— RNC Research (@RNC Research) 1675438923

The narrative may be convenient for Biden, but it's simply not true.

When Biden took office in January 2021, inflation registered between 1.4% to 1.7%, below the Federal Reserve's target rate of 2%. Inflation began increasing in March 2021, ironically the same month that Biden signed his $1.9 trillion COVID-19 economic stimulus into law. Inflation peaked in June 2022 at 9.1%, a rate not seen in more than 40 years.

Inflation had previously not increased above 3% since 2011 when Barack Obama was president. Inflation remains, according to the latest data, above 6%.

Not only was inflation not an existing problem when Biden took office, but many economists believe that Biden's COVID stimulus overheated the economy, a fact even the New York Times admitted last year.

The stimulus-related overheating thus explains why the U.S. experienced disproportionately high inflation last year compared to other developed nations, according to economists at the San Francisco Federal Reserve.

"Since the first half of 2021, U.S. inflation has increasingly outpaced inflation in other developed countries," the economists said. "Estimates suggest that fiscal support measures designed to counteract the severity of the pandemic’s economic effect may have contributed to this divergence by raising inflation about 3 percentage points by the end of 2021."

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!