How Trump Can Fight The Fed’s Threat To Housing Affordability
 The White House can fight the negative effects of the Fed’s rate hike with policy decisions that will make a measurable difference soon.
President Trump’s call for a $5,000 “dividend” payment to all adult U.S. citizens is being widely criticized as fiscally unsound, grossly irresponsible, a cynical vote-buying scheme, and another political promise that will never come to fruition.
Trump’s plan, as he presented it in just a couple of throwaway sentences at the Republican Midterm National Convention in Dallas last week, is indeed all those things. It amounts to a Keynesian-style attempt to stimulate the economy temporarily by making people feel richer than they are, to be followed by the usual consequences of such fiscal monkeyshines: violent inflation and a subsequent grinding recession.
An unprecedented economic boom or dramatic revenue surge cannot be assumed in advance.
Trump, however, is a habitual dealmaker. What if congressional leaders were to respond to the president’s idea as a starting point for negotiations?
My suggestion: Agree with the president to pass a one-time tax cut of $5,000 for the 2027 fiscal year, paired with a permanent spending cap set at the 2019, pre-COVID-19 level and mandatory 2% additional reductions in the spending cap each year through 2040.
The tax cut would be payable immediately upon enactment and designated as refundable to all U.S. households that file a personal income tax return (whether they pay any income tax or not), thus fulfilling Trump’s promise.
Republicans would make a simple deal with the American people: $5,000 today for every adult citizen, in exchange for serious, desperately needed cuts in federal spending beginning in the next fiscal year and continuing through the next decade. Any congressional Democrats who want to do the right thing will be welcome to vote for it as well, of course.
For practical reasons, the spending cuts would need to begin with the 2028 fiscal year in October 2027, but the 2% annual spending cuts thereafter would easily offset the extra interest costs on the additional federal debt that the delay would create.
To implement the cuts, Congress would convert the federal portion of spending on Medicaid, SNAP, housing programs, higher education, and the like into block grants to the states, with the expenditures scaled down to the 2019 level. The legislation would institute 5% annual reductions in those block grants for subsequent years through 2040, essentially phasing them out of the federal fisc.
The move to block grants with annual downsizing would steadily transfer responsibility for welfare spending to the states, where it belongs. Federal redistribution programs are not explicitly permitted under the Constitution, and the Supreme Court should never have allowed Congress to establish those programs.
These welfare programs account for about 24% of the $7 trillion-plus federal budget, around $1.7 trillion. In 2019, they composed about $1 trillion. A return to that number would pay off a $1.3 trillion refundable one-year tax cut in less than two years, with a dozen years of much lower federal spending on the way.
RELATED: Free money wins elections — and that’s why America’s debt will keep growing
If a 40% cut in spending on federal welfare programs sounds draconian and cruel, remember that the 2019 spending level was far from stingy. We needed cuts then, and we need them much more urgently now, even without Trump’s dividend payments. Investigations during President Trump’s current term suggest that elimination of entitlement fraud could lead to even greater cuts than what this plan would call for.
Congress should also consider cutting defense spending to provide further spending reductions.
In short, this would be a temporary tax cut and permanent spending cuts — the very opposite of the way things are ordinarily done in Washington D.C. The key element, and the unique opportunity here, is the political goodwill and appealing trade-off the $5,000 dividend checks would provide.
The only way to reverse the spending cuts would be through legislation signed by the president or a veto override. Trump would have every reason to refuse any attempt by Congress to restore the spending, especially given his track record of trying to implement limits on entitlement programs through executive orders. The same would be true for any Republican successors.
Moreover, the transfer of welfare responsibility to the states would eliminate congressional spending junkies’ ability to use these programs as a slush fund for buying votes. In addition, the money simply will not be there, given the rising cost of Social Security and Medicare.
This plan would allow Congress fiscal breathing space to develop a plan to transition Social Security and Medicare into private taxpayer accounts and transfer future responsibilities for those programs to the states. Social Security and Medicare are just as unconstitutional as the other entitlements, with the important difference that these were funded by people’s paychecks with the direct promise of repayment, a pledge the government must keep for current and prospective retirees.
Americans would be relieved to know that major Social Security cuts are off the table.
The plan should also make permanent all of Trump's executive orders that have reduced federal regulations — and add further regulatory relief.
RELATED: Trump’s interest-rate fantasy runs into debt gravity
The large, one-year tax cut would spark an economic boom of possibly unprecedented proportions. Economic growth would cause federal revenues to rise dramatically in subsequent years, which would enable the government to begin paying down the existing federal debt.
The spending cuts would push down interest rates by greatly reducing the federal deficit and thereby raising the assurance that the federal government will be able to pay its debts, thus increasing the value of Treasury bonds and lowering interest costs.
This would reduce interest rates for all Americans, including for mortgages. That would help relieve the housing affordability problem.
The entitlement cuts would also put able-bodied people back to work and make them taxpayers instead of tax takers, raising revenues and cutting costs further. That would spur even more economic growth.
These would be impressive achievements. A political party that instituted this plan could create a permanent majority despite the inevitable mistreatment by the media and the opposition party, while returning the nation to constitutional rule. Most people dislike the current overspending, and people recognize that far too much of it goes to cheaters, grifters, and government cronies.
For the good of the American people, Trump and the congressional Republicans should prepare legislation to implement this full plan in the lame-duck session, immediately after the election, regardless of whether they win House and Senate majorities this fall. They would be giving the American people a great gift of economic prosperity and better government, and Democrats would not be able to reverse any of it, with a Republican president holding veto power.
The Federal Reserve has raised the interest rate as fears of inflation persist despite economic optimism from President Donald Trump.
On Wednesday, the Fed voted unanimously to increase interest rates by a quarter of a percentage point, the first rate-hike since 2023.
'We should have the LOWEST RATE of any country in the World.'
"Economic activity is expanding at a solid pace. While uncertainty remains elevated owing, in part, to geopolitical developments,domestic spending has been resilient. Productivity growth is strong, and capital investment is robust. Job gains have kept pace with the workforce, and the unemployment rate has changed little," a press release from the Fed said.
"Inflation remains elevated. Today's policy action will support a timelier return to the Committee's 2 percent goal. The Committee will deliver price stability."
New Fed Chairman Kevin Warsh voted to increase the rate even though Trump has repeatedly called for rate cuts to keep the U.S. economy growing.
The latest jobs report released two weeks ago showed impressive gains in August and revealed that reports from previous months had been revised upward.
In response to the jobs report, Trump posted, "Lower the interest rates because the U.S.A. is a much stronger credit than it was just a short time ago! A STRONG COUNTRY MEANS A LOWER INTEREST RATE — IT’S A BETTER CREDIT ... Very simple! We should have the LOWEST RATE of any country in the World."
He even threatened to "STOP TRADING WITH COUNTRIES WITH WHICH WE HAVE A DEFICIT" if the Fed failed to lower rates.
RELATED: 'Blow expectations out of the water': HUGE GAINS in latest jobs report
The White House did not respond to a request for comment from Blaze News.
The rate-hike is the first major Fed move under Warsh's leadership. Trump nominated Warsh to replace Chairman Jerome Powell, who officially stepped down in May after repeatedly butting heads with Trump, especially regarding interest rates.
Trump even took to calling Powell "Too Late," claiming that the then-chair's failure to lower rates was stifling the American economy. Trump blamed Powell's obstinance on "gross incompetence, total dishonesty, or both."
For his part, Warsh has been tight-lipped about his plans at the Federal Reserve, claiming back in August that he prefers to have a "good family fight" about interest rates and other decisions rather than tip his hand ahead of time.
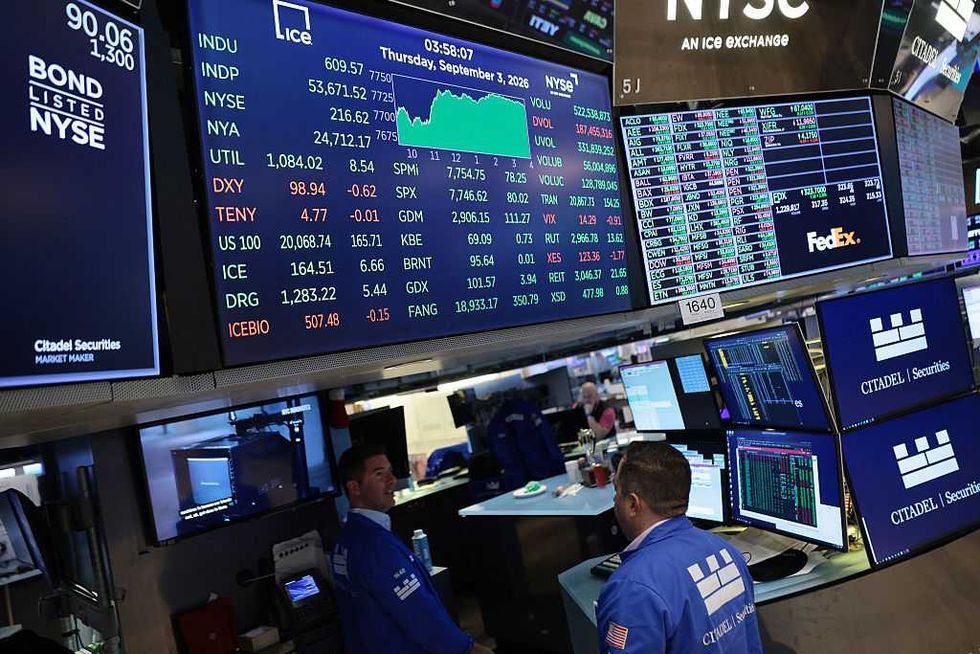
Wall Street has mainly responded favorably to the rumors about the impending rate increase. The NASDAQ and S&P opened Wednesday with gains, while the Dow Jones opened slightly down. Immediately after the hike announcement, all three markets were in the green.
Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!
You can have very low interest rates, and you can have debt-driven inflation. You just can’t have both at the same time. That is the reality President Trump refuses to recognize.
At the core of the president’s half-baked plan to resuscitate the economy is a return to the good old days of near-zero interest rates.
The Federal Reserve can set the short-term rates as low as it wants, but the bond markets will continue to rebel and reflect reality.
“We should have the lowest interest rates anywhere in the world,” Trump said last week in response to a reporter’s question in the Oval Office.
“In the old days … if we announced good numbers, interest rates went down. Now, if you announce good numbers, interest rates go up because they’re so afraid of inflation.”
It’s hard to make sense of that statement, but it reflects a grievance Trump has voiced consistently. He wants endless spending for his projects, he doesn’t want the inflation it causes, and he wants to pay near-zero interest on the resulting record debt. Don’t we all?
Perhaps in another lifetime, God will create such an innovative world. In this one, when you have protracted inflation and must sell endless Treasuries to service the debt, you cannot offer near-zero interest to buyers of that debt — especially at a rate below inflation.
We had multiple periods of near-zero interest rates this century, including during COVID. We also spent trillions of dollars we did not have during Trump’s first term and Biden’s presidency. That helped fuel the inflation surge of 2021-22. Prices have continued rising even as the inflation rate slowed, while the debt keeps exploding. Year-over-year inflation has now remained above the Fed’s 2% target for 65 consecutive months, with most months above 3%.
Far from being “artificially high,” as Trump contends, rates have been held artificially low. After the federal funds rate peaked at 5.5% during the inflation fight — a historically unremarkable level — the Fed cut rates six times beginning in 2024. The effective rate now stands at 3.63%, below the long-run average.
So what did the bond market do? The 10-year Treasury yield is roughly as high as it was when the federal funds rate peaked in 2024, and the 30-year yield is at levels not seen since 2007.
The Federal Reserve can set short-term rates as low as it wants, but the bond market will still reflect fiscal reality. There is no way around crushing debt other than cutting spending.
RELATED: The government would like to discuss your allowance
That was on vivid display late last month when Treasury Secretary Scott Bessent instituted a “twist” operation: The government bought back more long-dated Treasuries while relying more heavily on cheaper short-term bills and notes to finance the deficit and the purchases themselves. The goal was to reduce the supply of long-duration debt, support bond prices, lower long-term yields, and exploit the fact that short-term rates remain below 10- and 30-year yields.
The response from the bond market?
After a few hours of lower yields, by the next morning they were back near their pre-announcement baseline.
The 10-year yield is now around 4.75%, higher than at any point since April 2007. Back then, the effective federal funds rate was 5.25% — 162 basis points above today’s rate. The bond market is telling us that long-term rates are not high because the Fed forgot how to cut. They are high because investors demand compensation for inflation, deficits, and debt risk.
There is a simple reason the Fed can no longer wave a magic wand, return rates to near zero, and service the debt on the cheap as it did from the post-9/11 recession through COVID. On September 11, 2001, gross federal debt was about $5.77 trillion, roughly 55% of GDP. In April 2007, before the financial crisis, it was about $8.84 trillion, or 63% of GDP. Today it exceeds $40 trillion and is roughly 123% of GDP.
RELATED: Democrats want amnesia on inflation
The long-term trajectory is even worse, because faster debt growth creates a vicious cycle: Treasury needs more buyers, inflation and fiscal risk force yields higher, and more existing debt rolls over at those higher rates.
After an election fought in part against Bidenflation, nearly $4 trillion in new debt has been added since January 2025. Across Trump’s two terms, roughly $11.7 trillion of gross federal debt has accumulated. There are still more than two years left in his term, and there is no serious plan to bend the trajectory.
Naturally, all this new debt is being accumulated at higher interest rates. But the sheer magnitude of the debt also makes Trump’s dream of permanently cheap money impossible.
We all share Trump’s desire to service the debt on the cheap. He probably should have thought harder about that desire when he pressured Republicans in March 2020 to shut down the country and then pass trillions in new spending. Unfortunately for him and his delayed second term, what goes around in debt comes back around as inflation and higher interest rates.
Kevin Warsh, the primary intermediary between the Federal Reserve and Wall Street during the 2008 financial crisis, was confirmed on Tuesday to a 14-year term as Federal Reserve governor and confirmed on Wednesday as Jerome Powell's successor as chairman of the U.S. central bank.
Powell, who was first nominated to the Federal Board of Governors by former President Barack Obama and whose term as chair ends on Friday, wished Warsh well. However, he also provided his replacement with something more valuable than a nice sentiment: examples of what not to do, or at least, what to avoid doing.
Powell has, after all, dropped the ball on numerous occasions — sometimes with catastrophic consequences for the country. Here are just four examples.
Powell stated on March 4, 2021, in the second year of the pandemic, that inflation might increase but that it would likely be "transitory" and not enough for the central bank to raise record-low interest rates — a decision some suspect was geared toward pleasing then-President Joe Biden and thereby securing Powell's reappointment.
'Most of the expected GDP slowdown — from over 3% to 1.5% — was due to Powell's blunder.'
MarketWatch's Greg Robb noted that Powell's wrong-headed "transitory" view of inflation — one that would define his eight years as Fed chair — precluded the Fed from raising interest rates until 2022 while the Fed was also buying up bonds "and swelling its balance sheet."
Thanks to Powell's mistake — which economist Mohamed El-Erian, former PIMCO chief executive, said was "probably the worst inflation call in the history of the Federal Reserve" — the Fed was consistently on the back foot.
RELATED: Your bank can shut you down overnight — here’s how to protect yourself
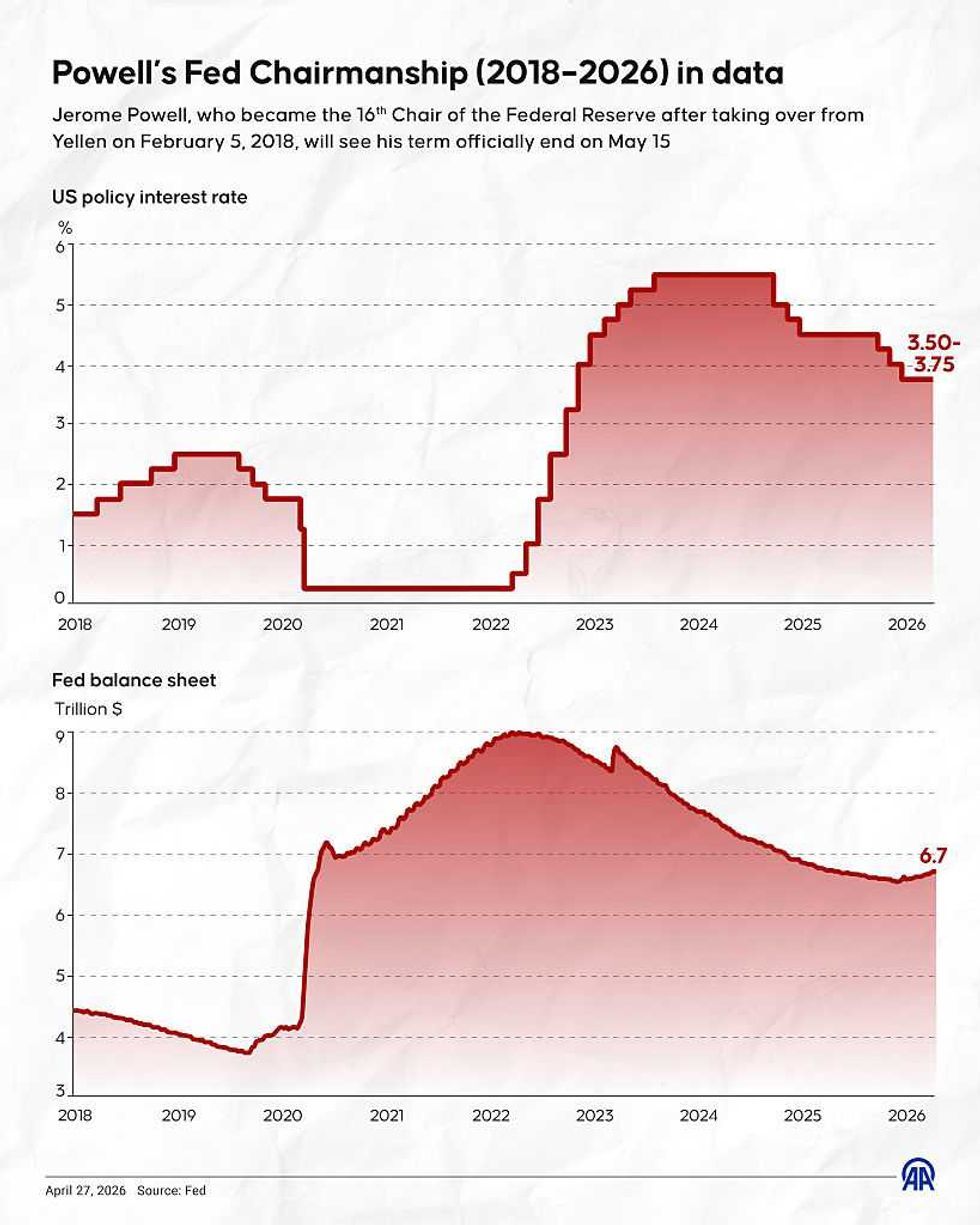
Facing the highest inflation Americans had seen in 40 years — inflation that no longer appeared to be "transitory" — Powell ended up raising interest rates 11 times between March 2022 and July 2023, when its benchmark rate reached a range of 5.25% to 5.5%.
Powell told "60 Minutes" in a Feb. 1, 2024, interview:
In hindsight, it would've been better to have tightened policy earlier. I'm happy to say that. Really, it was this. We saw what we thought was that this inflation, which seemed to be mostly limited to the goods sector and to the supply chain story. We thought that the economy was so dynamic that it would fix itself fairly quickly. And we thought that inflation would go away fairly quickly without an intervention by us. That it would be transitory.
Powell leaves office with inflation well above the Fed's 2% target for five consecutive years.
While reluctant initially to raise interest rates when Biden was in office, Powell previously demonstrated an eagerness to raise rates in 2018 when President Donald Trump was in office and the economy was booming.
"Every time we do something great, he raises the interest rates," Trump said at the time. Powell "almost looks like he's happy raising interest rates."
The repeated hikes, which Trump blamed for coinciding stock market turmoil, were supposedly prompted by concerns that the Republican president's tariffs and tax cuts, the latter of which were framed as a $1.5 trillion fiscal stimulus, might together contribute to inflation.
Powell stated that "fiscal policy is becoming more stimulative. In this environment, we anticipate that inflation ... will move up this year."
Economist Donald Luskin, chief investment officer for Trand Macrolytics LLC, recently noted that "there is no evidence that Mr. Trump’s tariffs in 2018 and 2019 led to any inflation at all."
Economist and Trump trade adviser Peter Navarro wrote last year, "Powell's audition for 'worst Fed chair' began shortly after his February 2018 appointment. Promising President Trump in the Oval Office a supportive posture to secure his nomination, Powell instead aggressively raised rates into the low-inflation, high-growth Trump economy. Powell wrongly believed Trump's tax cuts and tariffs would spark inflation — they didn't."
Powell's bet against Trump's tariffs and tax cuts proved consequential.
"As Powell's Fed hiked interest rates four times in 2018 — despite muted inflation and strong labor market gains — economic momentum slowed sharply," wrote Navarro. "According to the Fed's own September Tealbook, most of the expected GDP slowdown — from over 3% to 1.5% — was due to Powell's blunder."
"It would cost the American economy hundreds of thousands of jobs and hundreds of billions of dollars in lost economic output and tax revenues," added the trade adviser.
Powell reportedly greenlit luxury renovations to the Fed's Washington, D.C, headquarters that exceeded the original budget by roughly $700 million and is set to cost around $2.5 billion.
Controversy over the renovations — which include a rooftop terrace with gardens, VIP dining rooms, "premium" marble, and water features — came to a head in January, several months after U.S. Federal Housing Finance Agency Director William Pulte called for an investigation into Powell and his removal as Fed chair.
RELATED: Debit card company promises to pay your bill ... sometimes: 'Buy now, pay maybe'
Powell said in a Jan. 11 statement that "the Department of Justice served the Federal Reserve with grand jury subpoenas, threatening a criminal indictment related to my testimony before the Senate Banking Committee last June. That testimony concerned in part a multiyear project to renovate historic Federal Reserve office buildings."
An activist Biden-appointed judge quashed the grand jury subpoenas in March.
"Jerome Powell today is now bathed in immunity, preventing my office from investigating the Federal Reserve," Jeanine Pirro, the U.S. attorney in Washington, said in response to U.S. District Court Judge James Boasberg's rulings. "This is wrong, and it is without legal authority."
Last month, the Trump administration dropped the criminal investigation into Powell over his luxury renovation project.
While apparently off the hook, the controversy nevertheless hangs over Powell as another example of costly mismanagement.
Powell and his underlings also failed to prevent the March 2023 collapses of Silicon Valley Bank and Signature Bank — the third- and fourth-largest bank failures in American history, respectively.
Powell acknowledged weeks after the bank failures that the Fed's efforts to intervene were too little, too late.
"It does kind of suggest there's a need for ... regulatory and supervisory changes, just because supervision and regulation need to keep up with what's happening," said Powell. "My only interest is that we identify what went wrong here ... make an assessment of what are the right policies to put in place so that doesn't happen again, and then implement those policies."
One of Powell's lieutenants, then-Vice Chair Michael Barr, admitted that the "Federal Reserve supervisors failed to take forceful enough action."
A damning April 28, 2023, report on the Fed's bungled supervision and regulation of Silicon Valley Bank — the conclusions of which Powell ultimately accepted — said that:
As the United States navigates a fragile ceasefire in its conflict with Iran, the price of oil has remained volatile and high. Brent crude, the international benchmark, was trading at $104.21 per barrel at market close on Monday, nearly 57% higher than its pre-conflict price. Inflation has risen as a result and is in a territory it hasn’t been since 2023, according to an analysis by NBC News.
On Tuesday morning, the Bureau of Labor Statistics released its monthly Consumer Price Index update for April. It reported that inflation in April was 3.8%.
A vast majority of Americans don’t trust either party to fix the economy.
The bureau stated in a press release that the rise in energy costs is responsible “for over 40% of the monthly all-items increase.”
In its report on the April inflation numbers, NBC News noted that in Friday’s April jobs report, average hourly earnings rose by 3.6% over the past year. This marks the first time since 2023, during the Biden administration, that wages have not kept pace with inflation.
Despite the runaway inflation of the Biden years, Democrat congressional leaders pounced on the inflation news. House Budget Committee Ranking Member Brendan Boyle (D-Penn.) said in a statement, “From his tariff taxes to his disastrous war in Iran, President Trump is making life even harder for American families. Today’s inflation data confirms what everyone can see: Costs are out of control.”
Republicans, on the other hand, are focused on the growth in jobs and the economy in general and reminding voters of the Biden-era inflation. House Ways and Means Committee Chairman Jason Smith (R-Mo.) said, “While inflation has come down substantially since the 21% spike in prices seen when Democrats controlled all of Washington, American families are still looking for additional relief, and that is why Republicans acted to deliver the largest tax cuts in American history.”
Smith further highlighted the growth in GDP and hope that the new chairman of the Federal Reserve would be “a leader over monetary policy who understands that high interest rates have held back the true economic potential of our country.”
RELATED: The SAVE America Act won’t be enough to save the GOP from a midterm bloodbath
A consensus seems to be brewing among investment experts that unlike the broad-based inflation of the early part of the Biden presidency, this inflation could truly be transitory if energy prices come down.
“The report still showed only limited evidence of fully broad-based second-round inflation effects,” said Arielle Ingrassia, an investment specialist at Evelyn Partners, according to IFA magazine.
“That leaves the overall picture closer to an energy and transport shock than a full inflation spiral — at least for now.”
The inflation release Tuesday coincides with findings from a new CNN/SSRS poll that shows "roughly two-thirds of Americans say that Trump’s policies have worsened economic conditions in the country. And Trump’s approval rating stands at 30% on the economy, a career low,” according to CNN.
But Democrats do not fare well in this new polling either. A vast majority of Americans don’t trust either party to fix the economy.
As the nation heads into a midterm election being shaped by redistricting battles, Americans' perceived economic outlook will continue to be a determining factor for the control of both the House and Senate in November.
Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!
President Donald Trump's pick to overhaul the Federal Reserve has enjoyed support from the commander in chief's allies in the Senate, but one lawmaker just might shut down the nominee's confirmation.
Trump nominated Kevin Warsh to chair the Federal Reserve back in January after publicly feuding with current Chair Jerome Powell for failing to cut interest rates and for his multibillion-dollar renovation of the Fed building. Since then, Warsh took the first step of the confirmation process by going to Capitol Hill to testify before the Senate Banking Committee on Tuesday.
'Political interference or legal intimidation is non-negotiable.'
Warsh received glowing reviews from the seven Senate Republicans after his hearing, including from GOP Sen. Thom Tillis of North Carolina, who has butted heads with Trump in the past. Despite Tillis' endorsement of Warsh, the retiring senator drew a bold red line for the administration that could cost the confirmation.
"Kevin Warsh is a great nominee to be chairman of the Federal Reserve, and I look forward to supporting him out of committee once the DOJ drops their bogus investigation into Chairman Powell that threatens the independence of the Fed," Tillis said in a statement.
RELATED: Federal Reserve makes key decision on interest rates — and Trump won't like it

Tillis has repeatedly demanded that the administration suspend its investigation into Powell, even threatening to block nominees he supports, like Warsh. Notably, the Senate Banking Committee is composed of seven Republicans and six Democrats, meaning Tillis' vote is necessary to advance Warsh's nomination assuming the vote falls along party lines.
"The Department of Justice continues to pursue a criminal investigation into Chairman Jerome Powell based on committee testimony that no reasonable person could construe as possessing criminal intent," Tillis said following Warsh's nomination in January. "Protecting the independence of the Federal Reserve from political interference or legal intimidation is non-negotiable."
"My position has not changed: I will oppose the confirmation of any Federal Reserve nominee, including for the position of Chairman, until the DOJ’s inquiry into Chairman Powell is fully and transparently resolved."
One viable "off-ramp" that has been floated by Republican Sen. Tim Scott of South Carolina, who chairs the committee, is to create a subcommittee to investigate and oversee the Federal Reserve's over-budget construction. This would, in effect, replace the Department of Justice's criminal probe into Powell but still allow the administration and its allies to investigate the Fed.
It's unclear whether the DOJ would drop the investigation, but Tillis expressed enthusiasm about the potential resolution.
“I not only think it’s a good off-ramp, but I also think it’s good governance,” Tillis said.
Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!
 The American people themselves want to have their fiscal cake and eat it too.
 Lawmakers focused on their reelection in a few months or years care little about whether the United States faces economic stagnation decades from now.

 www.theblaze.com
 thefederalist.com