From Cradle To Krispy Kreme To Grave, Private Equity Is Making Everyone’s Life Worse
 Buying a house, raising a family, spending Saturdays at kids' sporting events – every aspect of normal life is touched by private equity.
Nearly half of American adults say health care is difficult to afford, and about one-third have skipped or postponed care because of the cost, according to KFF polling. Even insured Americans are feeling the strain: The average monthly price of health insurance rose nearly 26% in a single year, the Urban Institute recently found.
Many forces drive those costs. One has operated largely outside public view: private equity.
Private equity-owned hospitals charged more, spent no less on patient care, and kept the difference.
Last month, my organization, Campaign for Accountability, released “Overbilled and Overtreated,” a report combining hospital financial data from the National Academy for State Health Policy with the Private Equity Stakeholder Project’s ownership tracker. We compared 71 hospitals acquired by private equity firms with 71 closely matched peers.
After acquisition, private equity-owned hospitals collected $669 more in operating profit per patient. Their operating margins were 6.5 percentage points higher — roughly a 31% increase. Among privately insured and self-insured patients, where hospitals have more freedom to set prices, the gap widened to 10.4 percentage points.
Those profits did not appear to come from running hospitals more efficiently. Private equity ownership produced no statistically significant reduction in operating costs per patient. Costs did not fall. Charges rose.
Court records show what pressure for higher revenue can look like inside medical facilities.
At Steward Health, created after Cerberus Capital Management converted a nonprofit hospital chain into a for-profit company, a former nurse billing auditor alleged that a Massachusetts team systematically reclassified patient charts into more expensive billing categories. A moderate emergency room visit could be elevated to the most severe level; the team, he said, could “only upcharge.”
Three Steward physicians filed a separate lawsuit alleging that hospital staff recorded patients’ blood pressure readings as normal to avoid diagnoses that would require costly treatment.
At Select Rehabilitation, then capitalized by Caltius Capital Management, a whistleblower alleged that therapists were pushed to inflate billable minutes to meet quotas. In one example, the company allegedly billed for 50 minutes of therapy after providing five. The whistleblower also claimed that severely ill patients underwent needless therapy and that discharges were delayed to maximize revenue.
RELATED: Hospital consolidations and ‘nonprofit’ tax breaks are driving up medical costs
At Surgery Partners, owned by H.I.G. Capital Group, a physician alleged that patients were required to undergo unnecessary urine drug tests at a company-owned laboratory. The tests were billed at $3,200 to $4,600, while physicians were barred from using a $20 alternative. The company later agreed to a $41 million settlement with the Justice Department and received a $45 million federal pandemic bailout days later.
The most disturbing example involved children. USA Today reported that dentists at North American Dental Group, a private equity-backed chain, drilled healthy teeth under pressure to generate revenue. One 3-year-old received seven root canals without first receiving an X-ray. He later required surgery to repair the damage. A reviewing dentist called the treatment a form of child abuse.
Private equity firms are not shy about the strategy. Ardent Health, owned by Equity Group Investments, told investors in 2025 that roughly half its revenue growth would come from higher rates rather than greater patient volume. Surgery Partners boasted of rising “revenue per case.”
Translated from investor language, the promise is simple: Charge more for each patient and call the difference growth.
Private equity is not solely responsible for America’s health care crisis. Hospitals, insurers, drug companies, government payment systems, and professional cartels all contribute to high prices and limited competition. But private equity adds a distinctive pressure: Investors expect rapid returns, while the patients absorbing the costs often cannot shop around, delay treatment, or meaningfully challenge a bill.
RELATED: Caregivers should not have to lie to prove compassion
Policymakers should account for that pressure. Proposals include barring private equity-owned hospitals and skilled nursing facilities from participating in Medicare and requiring providers to disclose mergers, acquisitions, and changes in ownership or control. At minimum, patients and regulators should know who owns the facility sending the bill.
Stronger disclosure alone will not solve the problem. Regulators and prosecutors must also scrutinize upcoding, unnecessary treatment, discharge delays, and other practices that turn patients into revenue targets.
The evidence in our report is difficult to dismiss: Private equity-owned hospitals charged more, spent no less on patient care, and kept the difference.
That may be an attractive growth strategy for investors. For patients already postponing care because they cannot afford it, it is another bill they should never have had to pay.
Across rural America, families are learning a hard lesson. The biggest threat to their local hospital or cancer clinic no longer comes from distance, workforce shortages, or regulation. It comes from private equity.
Over the past two decades, private equity firms have quietly bought hundreds of cancer clinics, oncology practices, and community hospitals. They promise efficiency and stability. Many communities experience something else: consolidation, higher costs, fewer doctors, and the slow erosion of care. When profit targets fall short, clinics close. Patients travel hours for treatment — or go without it altogether.
The same forces that hollowed out manufacturing towns and family farms are now targeting essential health care.
This shift reflects a deeper failure: treating health care as a financial asset rather than a public obligation.
Private equity follows a familiar playbook. Firms acquire medical practices with borrowed money, cut staffing, increase billing, extract profits, and sell within a few years. That model rewards investors. It fails patients who need long-term care and towns that depend on a single hospital or cancer center.
The collapse of 21st-century oncology shows how destructive this approach can be. After private equity took control, the company expanded rapidly across the Southeast while piling on debt. Pressure to generate revenue intensified. Federal investigators later uncovered widespread abuse, including unnecessary testing and illegal billing. The company paid more than $86 million in fraud settlements to the federal government and patients before filing for bankruptcy.
Entire regions lost access to cancer care with little warning. Investors exited. Patients were left to deal with the fallout.
Rural communities suffer the most. In cities, the loss of a clinic often means longer wait times. In rural America, it can mean the end of cancer care entirely. Patients face long drives, delayed treatment, or impossible choices between health and family obligations.
The same pattern appears in rural hospitals owned by Apollo Global Management through its control of LifePoint Health. After the acquisition, hospitals took on heavy debt. Executives sold real estate to raise cash, cut staffing, reduced services, and closed cancer centers. In New Mexico, state officials opened an investigation after reports that an Apollo-owned hospital denied or delayed cancer care for low-income patients.
RELATED: The hidden hospital scam driving up drug prices, coming to a state near you
Defenders of private equity claim these firms rescue independent practices from hospital monopolies. In reality, they replace local control with corporate control.
Doctors lose authority to distant executives who never set foot in the affected communities. The language of independence disguises a transfer of power away from patients and physicians and toward investors.
Conservatives should recognize this for what it is. An elite financial class is extracting wealth from essential local institutions and leaving weaker communities behind. The same forces that hollowed out manufacturing towns and family farms are now targeting essential health care.
Cancer care should not function as a short-term investment. Rural hospitals should not exist to satisfy quarterly return targets. A system that allows this will continue to fail the people who rely on it most.
The answer is accountability, not a government takeover of medicine. Regulators must enforce antitrust laws. Policymakers should strengthen protections that preserve medical judgment from corporate interference. Communities deserve transparency about who owns their hospitals and who controls decisions about their care.
Health care depends on trust and continuity. When financialization dominates cancer care, rural Americans lose both. And once these institutions disappear, rebuilding them proves far harder than protecting them in the first place.
The federally owned Tennessee Valley Authority is the largest public utility in the country, providing electricity to Tennessee and six surrounding states. And because the president appoints its board, it’s also a political football.
Democrat administrations have stacked the TVA board with green energy zealots committed to phasing out carbon fuels in favor of wind and solar. Donald Trump has responded by firing directors who embraced that faux utopian agenda, along with those who allowed the executives to reward themselves with high seven-figure compensation packages while outsourcing jobs to noncitizens.
The blue-collar working class has become a key element in the Trump coalition. If Trump moves to privatize the TVA, it will feel like a betrayal to the very people who have had his back.
Now a new tempest is brewing: Should the TVA be privatized?
The TVA was established as a public corporation in 1933 to provide flood control, rural electrification, and economic development in the Tennessee River Valley, as well as the surrounding areas of Appalachia. For almost a century, it has delivered abundant, inexpensive, and reliable electricity.
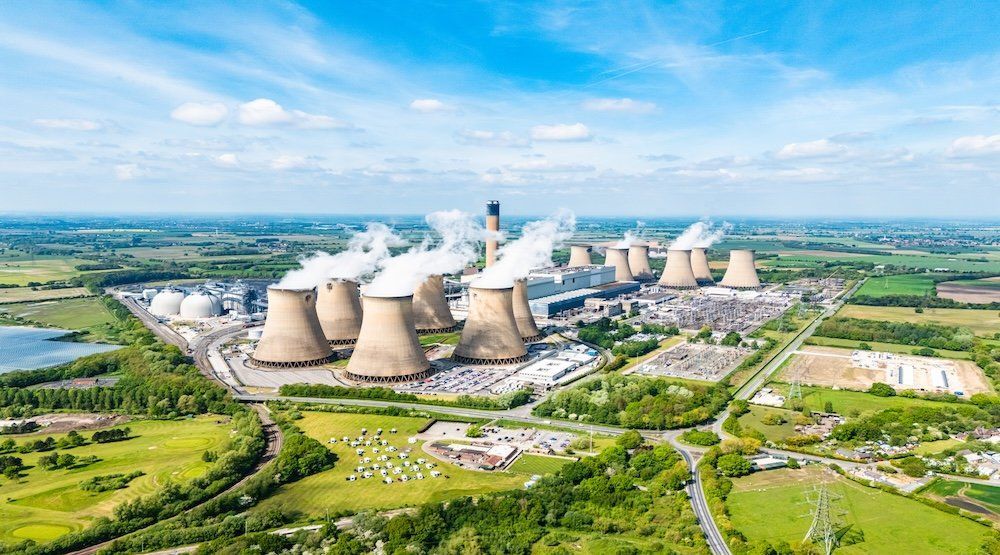
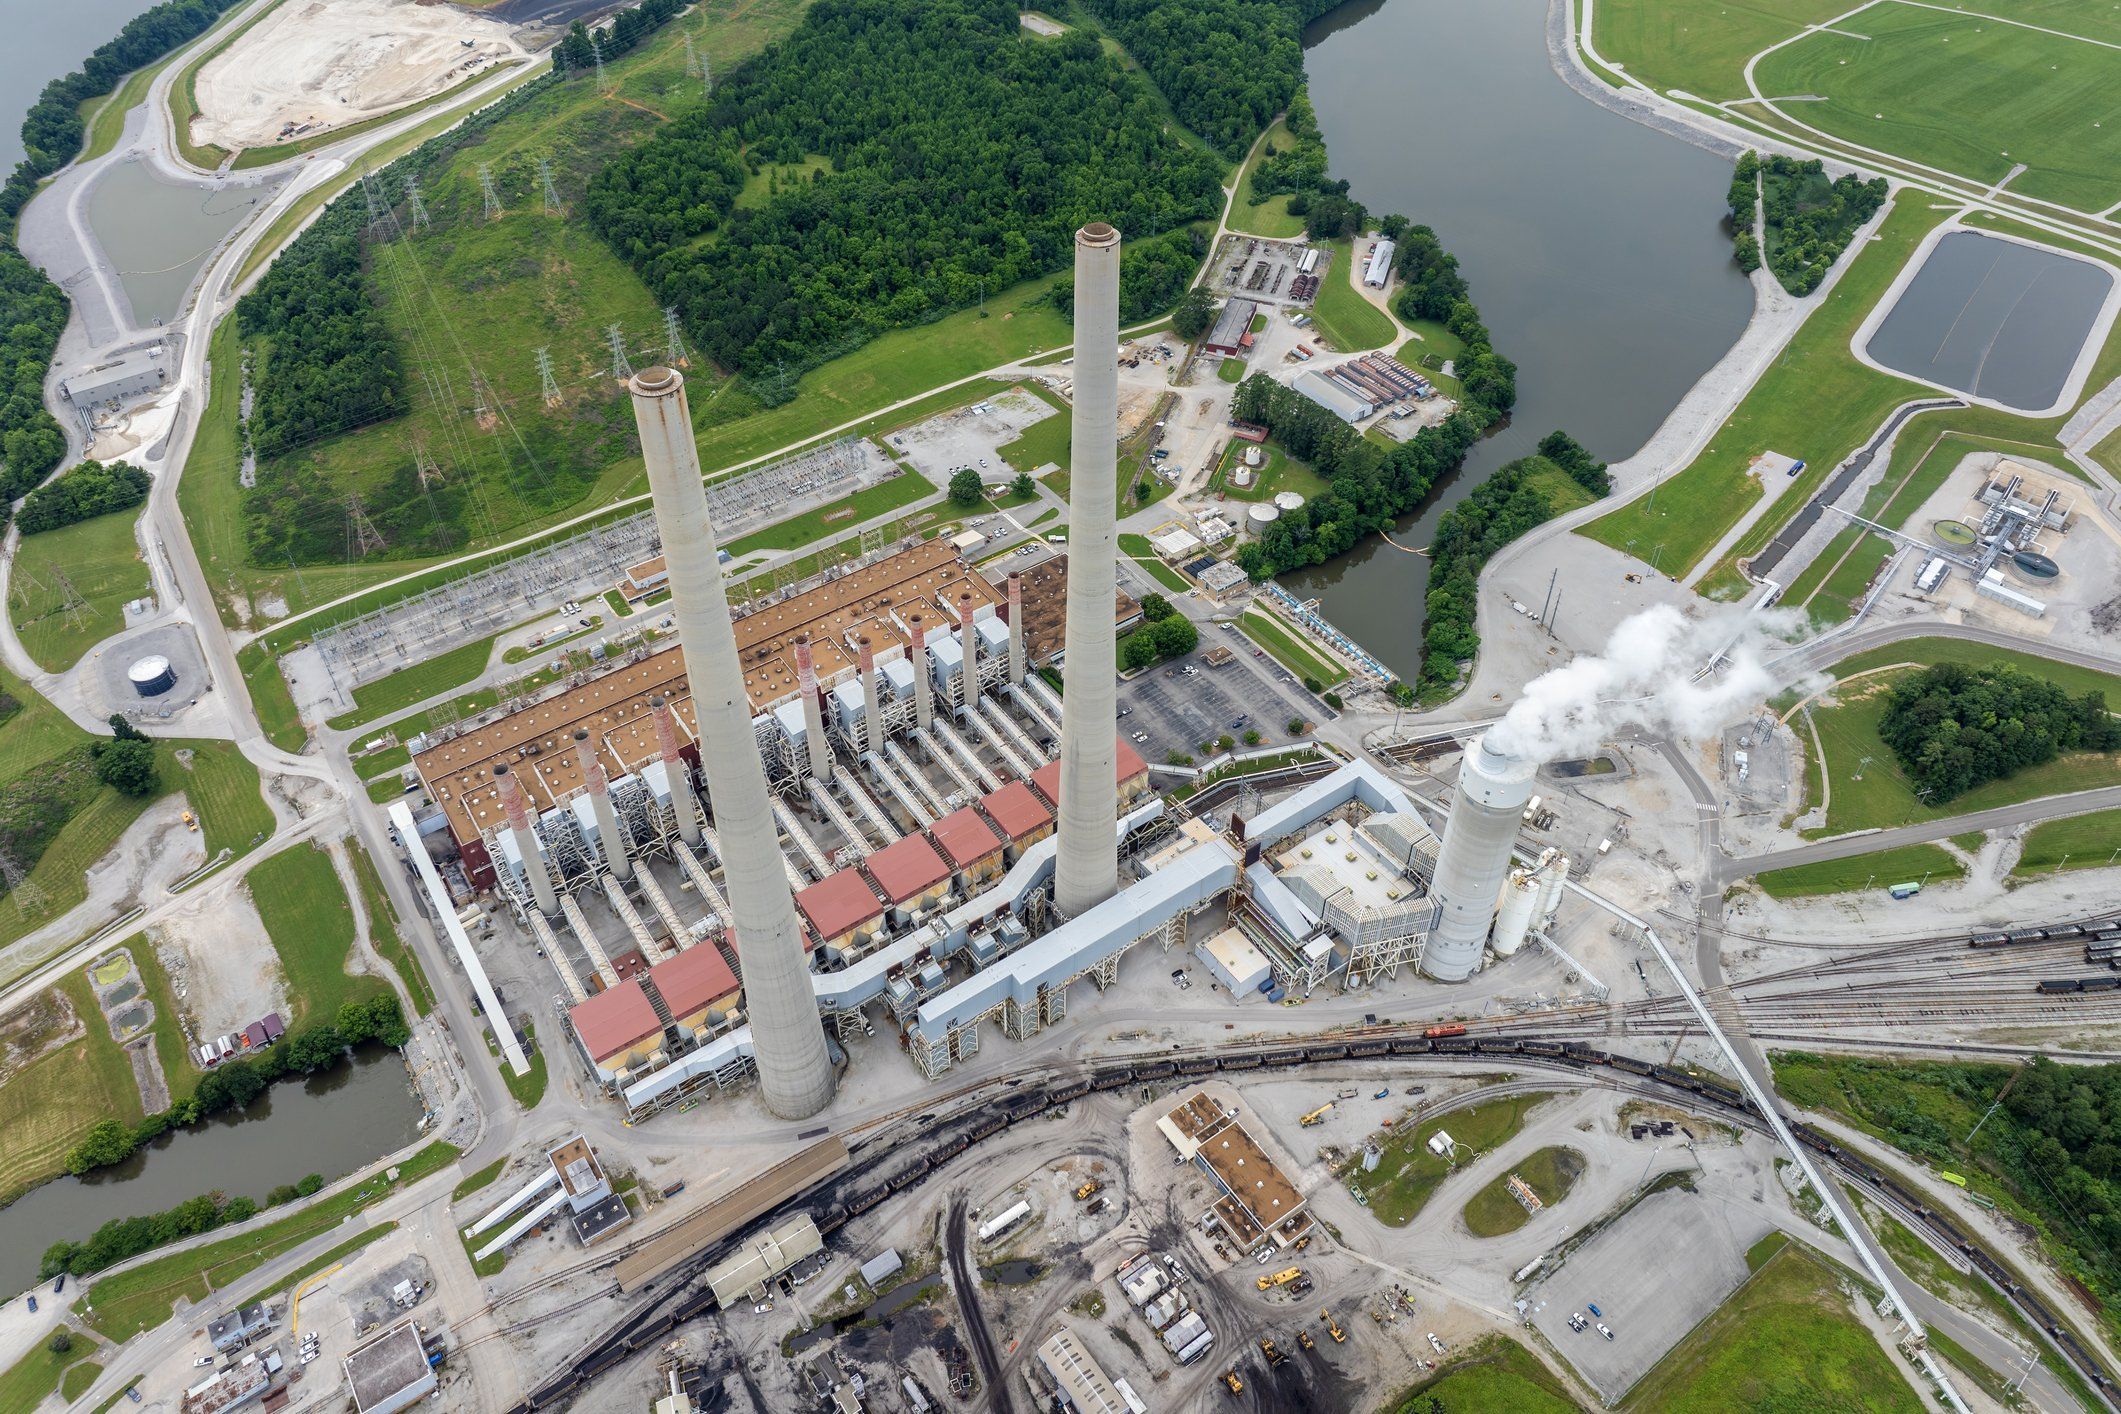
Most of its electricity comes from nuclear (42%) and natural gas (31%), while coal and hydroelectric account for about 23% combined.
Despite years of agitation from anti-carbon activists and Obama- and Biden-era appointees, the TVA’s power mix has remained overwhelmingly carbon-based — for one reason: It works.“Renewable” energy sources (primarily solar) only constitute about 4% of its total electricity production. And, as always, solar energy drops to zero at night.
The debate has focused on two extremes: Keep the TVA under federal ownership or privatize it. However, a third option offers a middle ground: Transfer ownership to the seven states that rely on it.
Moving ownership — and board appointments — to the seven primarily red states that rely on the TVA would ensure that green activists can’t destroy its ability to provide inexpensive, reliable electricity, while also maintaining the TVA’s status as a public utility.
The argument for keeping the TVA federally owned is that it has been very successful for a century now in providing electricity and flood control to much of Southern Appalachia. It also provides significant employment to the region.
Current corporate culture driven by private equity slashes employment to reduce labor expenses; relaxes quality and safety controls to meet budget-cutting goals; terminates the most experienced employees to eliminate their salaries; and outsources as many jobs as possible to non-Americans. Naturally, the fear of privatization is legitimate by those who rely on the TVA for electricity and employment.
Though the Trump administration hasn’t yet formally announced that it is considering privatization, many speculate that it is on the table. As the Atlantic reported recently:
Trump hasn’t spoken recently about privatizing the TVA. But in his first term, he proposed selling off the TVA’s power lines to a private buyer in 2018 and again in 2020. Now, he is positioned to stack the TVA’s board with new members. That, combined with his administration’s relentless push to shrink the federal government, has revived speculation about privatization — which many in Trump’s MAGA orbit have long argued should be the utility’s fate.
Most of the TVA’s 11,000-plus employees are skilled tradesmen and women who belong to unions. The International Brotherhood of Electrical Workers represents about 10,000 TVA employees. It has issued a pre-emptive warning to the Trump administration, stating:
The TVA is the primary reason the Deep South became the economic force it is today, and IBEW members have been there every step of the way. It’s an American success story that required skilled, union labor. We will fight tooth and nail attempts to turn it into a for-profit corporation whose only concern is ultra-rich shareholders.
I have had occasion throughout my career to work with companies that employ IBEW electricians, as well as companies that contract out for electrical work using the IBEW. These skilled tradesmen are overwhelmingly patriotic, America-first MAGA voters who detest the anti-carbon activists on the left. They also detest corporate America’s war on American labor.
The blue-collar working class has become a key element in the Trump coalition. If Trump moves to privatize the TVA, it will feel like a betrayal to the very people who have had his back.
Libertarian purists recoil at any level of government owning a utility. Yet privatizing the Tennessee Valley Authority as a regulated monopoly offers little difference from government ownership. Without a free-market competitor willing to build nuclear plants and hydroelectric dams, the result is the same.
Chattanooga’s Rep. Chuck Fleischmann (R), whose district includes the highest concentration of TVA employees, strongly opposes privatization. Knoxville Republican Rep. Tim Burchett, whose district houses TVA headquarters, is more open. He has said:
Any organization that pays their head $6 million a year plus bonus needs to be evaluated. For too long, the Tennessee Valley Authority has operated in the shadows with closed-door meetings and minimal transparency. I have sponsored, passed, and supported bills to fix these issues. I am a believer in capitalism and the free market. Any option that maximizes efficiency, incentivizes transparency, and keeps prices low for ratepayers should be explored.
Burchett has built a reputation fighting pork in Washington and is right to question the TVA’s waste and secrecy. But full-scale privatization isn’t the answer.
A better path would be to transfer ownership to the states. That compromise could deliver efficiency, accountability, and local control — while keeping the TVA safe from both federal meddling and Wall Street overreach.
RELATED: Tennessee Valley Authority gets a Trump-style reckoning
Well-intentioned defenders of federal ownership, from Fleischmann to the IBEW, assume that the TVA’s future will look like its past. It won’t. Democrats in Washington will never allow the TVA to remain a major provider of carbon-based energy. The most conservative region in America should not gamble its power supply on the whims of left-wing swamp creatures.
The mechanics of ownership among the seven states would require negotiation, but one model could grant Tennessee 40% ownership — reflecting its dominant use and production — with the other six states dividing the remaining 60%.
That structure would put accountability where it belongs: in the hands of state leaders answerable to the families and businesses who depend on the TVA. Local officials would bear political responsibility for keeping the lights on and the air conditioning running — not distant bureaucrats in D.C.
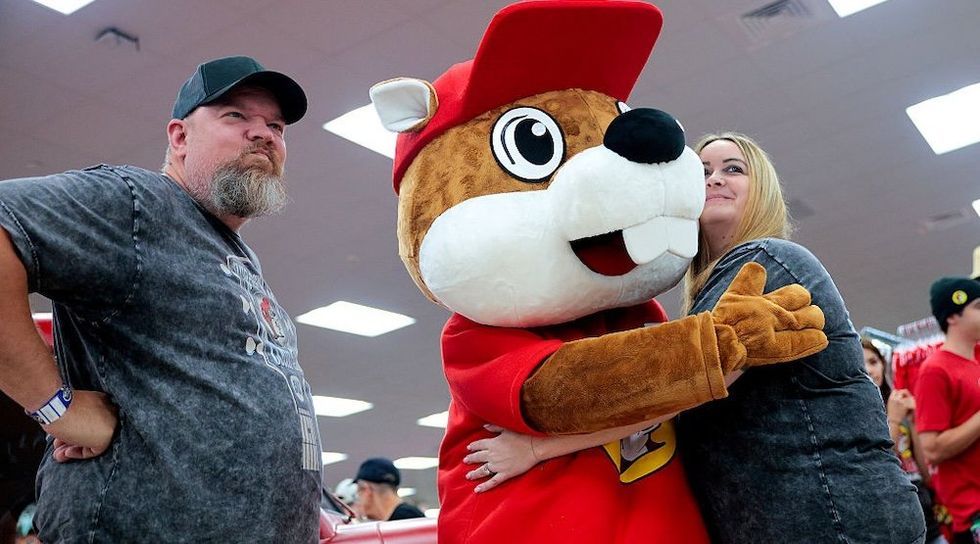
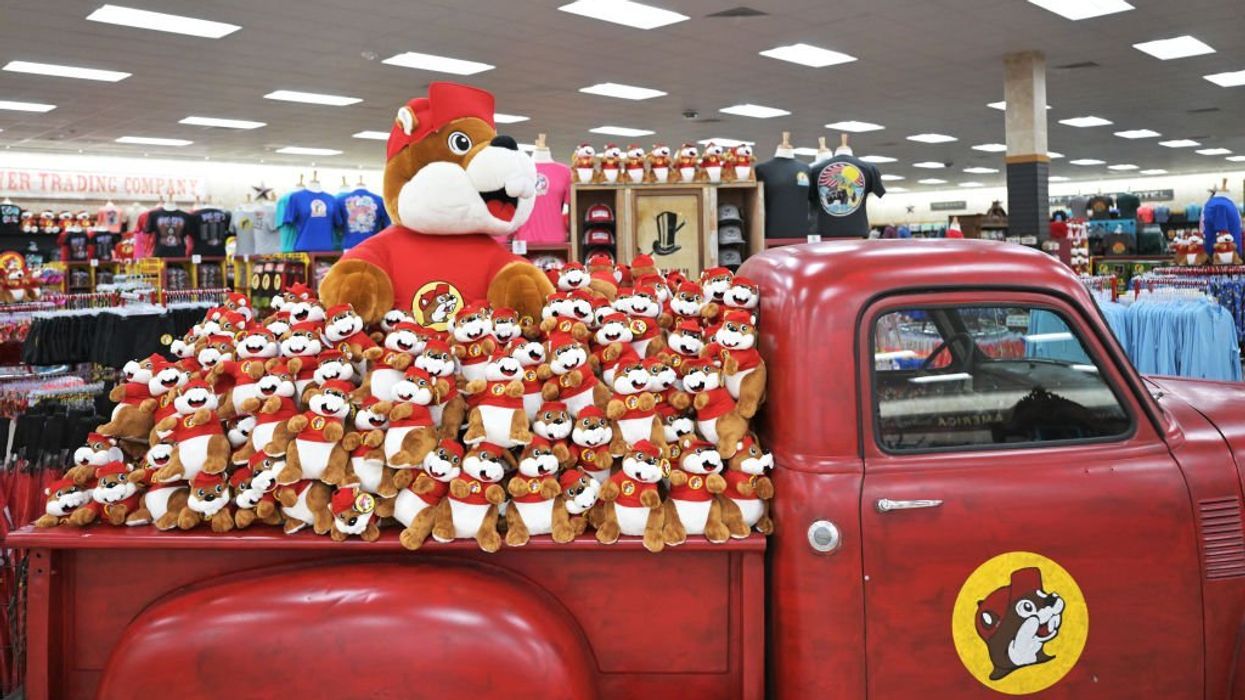
Buc-ee’s may be technically categorized as a “convenience store,” but for millions of Americans, it’s more like a roadside pilgrimage. No matter how big its new stores are, they remain packed. The chain has a fanatically loyal customer base, and it has become a destination for those not fortunate enough to have a Buc-ee's nearby.
What’s the draw? Buc-ee's has enormous restrooms that are immaculately clean, cheap gas with often more than 100 pumps, a kitschy-fun shopping experience, and exceptional food — including Texas barbecue and an in-house bakery. In addition, it’s heavily staffed with low-turnover, career employees.
I shudder to think of the destruction that would be brought upon the Buc-ee's business model if private equity decided to “fix” its operations.
Buc-ee's is thriving by rejecting numerous destructive “best practices” currently embraced by corporate America and private equity.
Fortunately for Buc-ee's, it’s still privately owned by its founders, Arch Aplin and Don Wasek, whose business acumen came from running convenience stores and working directly with customers and employees. They weren’t poisoned by an elite business school education, where modern executives learn that customers are prey and employees are a pestilence whose compensation reduces executive bonuses.
The magic formula to Buc-ee's success is built on a very simple foundation: clean restrooms and cheap gas. It first developed its cult following in Texas by being a place you could always count on for a clean restroom while driving the interstates. Good candies, food, and pastries then added to the appeal.
Nowadays, the same foundation is in place: clean restrooms and cheap gas. But once a customer walks inside to use the restroom, a wonderland of food and products awaits. The food and merchandise are not necessarily cheap, but they’re high-quality, and many customers enjoy making those purchases as part of their Buc-ee's experience. But it’s still possible to visit Buc-ee's for gas and a potty stop without paying a premium.
By contrast, Las Vegas tourism is down dramatically — in no small part because of the city's outrageous pricing. The old Vegas model of cheap buffets and affordable rooms to get people into the casinos was not unlike Buc-ee's lure of clean restrooms and cheap gas. But the Wall Street wizards now in control of Vegas have ditched the old model in favor of revenue-mining every possible moment of a visitor’s stay.
As Jeffrey Turner explained on his Substack, “The MBAs and data-crunchers at the corporate casino have installed Disneyland pricing into their models.”
Buc-ee's still understands the power of the previous business model that Las Vegas abandoned: Provide a high-quality “loss leader” — or two — to get the customers in the door, and then provide high-margin products that entice them to open their wallets.
For those who work at Buc-ee's, it’s more than a job — it’s a career. Buc-ee's doesn’t consider its staff to be “unskilled” labor who deserve near-minimum wages. Their excellent compensation results in lower turnover and better customer service. The food at Buc-ee's might be a little more expensive than at a nearby fast-food joint, but it’s of much higher quality and served by professional staff — things customers will gladly pay a premium for.
As I discussed in a recent column, revenue mining has become an all-too-common corporate business strategy these days, especially in private equity. Revenue mining exploits customers while slashing costs to the bone, shipping jobs oversees, firing veteran employees who know the business best, wrecking customer service, downgrading quality, and killing innovation. That pernicious strategy may briefly produce record short-term profits, but it also destroys customer loyalty and brand value.
I shudder to think of the destruction that would be brought upon the Buc-ee's business model if private equity decided to “fix” its operations.
RELATED: Fear the beaver: How a gas station became a cult (and why you should consider joining)
The famous Buc-ee's restrooms by themselves produce no revenue, and they occupy significant square footage. Its full-time staffers make about $40,000 annually simply to keep these restrooms clean. In other words, the restrooms are a loss leader, drawing customers in but producing no revenue. That’s anathema to private equity.
Private equity would slash the restroom maintenance, eliminate or outsource the cleaning crews, and decrease their square footage. Or maybe they’d try to charge admission to the restrooms. But they would undoubtedly kill the golden goose — the restrooms — and thus lose the golden egg that gets customers to the checkout registers.
A job sign outside a Buc-ee's in Alabama recently showed that several manager positions within a Buc-ee's pay in excess of $100,000 per year, and the store’s general manager can earn more than $200,000 per year. Wall Street or private equity would waste no time in slashing Buc-ee's employee head count and compensation, assuming it would increase the bottom line. But it wouldn’t; it would simply destroy the staffing that makes Buc-ee's success possible.
RELATED: Corporate America is eating its seed corn — and our future
Private equity would also be aghast at the “lost revenue” from offering below-market gas prices. Estimates are that Buc-ee's sells about 400,000 gallons of gas per day. Just charging 5 cents more per gallon would bring in an additional $7 million annually, all things being equal.
But all things aren’t equal.
Buc-ee's sells such a high volume of gas because its prices are lower. Buc-ee's understands that a lower gross profit per gallon with higher volume produces more gross profit than lower volume at a higher price. But more importantly, those swarms of cars fueling up on inexpensive gas are full of people who stroll inside and purchase high-margin discretionary products. It’s a simple concept that is alien to rapacious financial wizards, but one that’s well understood by retailers on the ground.
Buc-ee's success is a refutation of prevailing business wisdom. May it serve as an example to the next generation of business leaders on the importance of developing a loyal customer base with abundant staff, career wages, great customer service, high-quality products, and an enjoyable customer experience.
“Don’t eat your seed corn.” Every farmer gets it. Every American with common sense gets it. The only people who don’t? The people who run corporate America.
A farmer keeps part of this year’s crop for planting next year. He could sell it now and pocket more cash — but then there’s nothing to plant, nothing to harvest, nothing to live on later. That’s obvious to anyone who works the land.
Capitalism creates wealth. But when wealth is extracted at the expense of the product, the people, and the future — that’s not capitalism. That’s predatory ransacking.
But in today’s boardrooms, the rule is reversed. Short-term profit is all that matters. Strip the future bare, cash out, and leave the mess for someone else to clean up.
The rewards for this corporate vandalism are massive: fat bonuses, stock windfalls, golden parachutes. The damage — lost jobs, gutted industries, shoddy products — is someone else’s problem.
And the fastest way to pull it off? Slash costs to the bone. Ship jobs overseas. Push out the people who know the business best. Wreck customer service. Kill innovation. Downgrade quality until the product barely passes as the same thing you used to make.
Private equity and corporate strategists have a new trick for squeezing customers dry: “revenue mining.” That means cross-selling, upselling, jacking up prices, and hiding the real costs in creative contracts.
At first, it works. Existing customers tend to stick around — inertia keeps them from bolting right away. But each gimmick drives off a slice of loyal business. Combine that with lower service quality and cheaper products, and the exodus accelerates. Before long, the company is stuck with an overpriced product, lousy service, and no easy way to attract new customers.
I’ve watched this play out in my own life. My exterminator. My alarm company. My HVAC service. All wrecked by the same formula. The local phone number? Redirected to a call center overseas — if I can navigate the phone tree. The people I used to know? Gone. The contract? Suddenly much more expensive.
The service I get for my trouble? Less than before. And when the tech finally arrives, all he says is, “Things are much different now.” They might wring one more payment out of me, but I’m already shopping for a local outfit that treats me like a customer instead of prey.
In short, they ate their seed corn. They got one fat harvest out of me, then pushed me straight into the arms of their competition — for good.
At least my dentist is still a one-man shop who owns his own business. But even dentistry is under siege. Private equity-backed dental chains are giving dentistry a bad name, pushing unnecessary procedures just to meet revenue targets.
A USA Today investigation titled “Dentists under pressure to drill ‘healthy teeth’ for profit” uncovered one such example:
Dental Express was part of North American Dental Group, a chain backed by private-equity investors. At least a year earlier, the company had told dentists like Griesmer to meet aggressive revenue targets or risk being kicked out of the chain. Those targets ratcheted up pressure to find problems that might not even exist.
In my professional career, I have seen too many examples of the same pattern: private equity buying and destroying great businesses that had loyal customer bases. To be fair, I have also seen examples of private equity groups buying a business, embracing its product, and continuing to provide good service. I wish it weren’t the exception, though.
More often, private equity groups treat the acquisition as a mine: extract the capital through dividends and existing customers while accruing significant debt. In fact, the funds used to purchase the business are often borrowed and never even repaid.
Dig until empty, leave a crater, and move on.
An X user put it perfectly:
Some private equity is genuinely investing in the business to grow a solid business. This is good, full stop.
Some private equity buys up dying businesses, breaks them up, sells off the valuable bits and sometimes lets the worthless bits go through bankruptcy, taking advantage of bankruptcy laws to profit. This is good, actually, as it recycles the resources of dying businesses into good businesses.
The third type of private equity buys good businesses that are doing OK or even doing well. Then they sell off all the assets, load the company up on as much debt as they can, pay themselves giant dividends, and then take advantage of the same bankruptcy laws to discharge all the debt so they never have to pay it back. This is really bad.
This isn’t just happening to small companies. It’s hitting America’s industrial backbone.
I’ve written before about how Carlos Tavares, the former CEO of Stellantis (corporate parent of Chrysler, Dodge, and Jeep), awarded himself a $39 million compensation package for making short-term decisions that briefly maximized profit before revenue and sales collapsed, leaving dealers with overpriced, outdated inventory. He made off with the profits, then left behind a hollow pipeline for the dealers truly committed to Stellantis.
RELATED: Private equity’s losing streak is coming for your 401(k)
I also covered Boeing’s disastrous $43 billion stock buyback binge. The short-term boost to its share price came at the expense of critical investment in its products — and has cost the aerospace giant $35 billion since 2019. To plug the hole, Boeing had to raise another $15 billion in capital and push back the already overdue launch of the 777, citing “negligent engineering.”
That phrase used to be unthinkable in the aerospace industry. Boeing made it possible by gutting its engineering and technical staff to feed Wall Street.
The consequences keep coming. This month, United Airlines grounded much of its fleet after a failure in its proprietary “Unimatic” flight system. The airline claims it doesn’t know what caused the failure.
But I have a strong suspicion.
In recent years, United has aggressively outsourced its technical operations to contractors using foreign labor — often H-1B visa workers — at lower cost. One subcontractor, Vista Applied Solutions Group, boasts that it helps clients “increase productivity” while achieving “considerable cost savings.”
That’s great — until the system fails and planes can’t fly. United may have saved on salaries. The short-term reduction in salary expense has eaten United’s seed corn, leaving the company with a technology system that can’t keep its planes in the air.
It is imperative for those of us who defend capitalism to also repudiate those engaged in practices that give it a bad name. Capitalism creates wealth. But when wealth is extracted at the expense of the product, the people, and the future — that’s not capitalism. That’s predatory ransacking.
And it deserves our scorn.

 Why there will be a groundswell of new small businesses and how the Trump administration can help them flourish.
 Giving Americans the option of investing in private investments via their 401(k) plans poses many risks; a different proposal may be better.
 Just imagine how much it would help the middle class to enjoy access to America’s wealth engines again.

 www.theblaze.com
 www.theblaze.com