10 Ways You’re Wasting Money At The Grocery Store And What To Do Instead
 Saving money on groceries doesn't mean living on instant noodles. Becoming a smarter and more flexible cook will take you to another level beyond noodles.
Jonathan Goodman’s mnemonic words were written down and stored in safes and safety-deposit boxes. The device that generated them had never touched the internet. The cable was never plugged in, the QR code never scanned by anything connected to the wider world. Every visible precaution was observed with great care. Then, on the evening of July 29, 2026, the Canadian investor watched 18.25 Bitcoin leave his wallet over seven minutes. The sum was worth roughly 1.6 million Canadian dollars. He thought he had done everything right, but the money was now gone.
Goodman, like others, had put his trust in Coldcard, a hardware wallet for cryptocurrency. The natural instinct, when confronted with a theft like the Coldcard hack that hit him and many others, is to look for the intrusion: the broken window, the intercepted message, the insider. The Coldcard incident offered no such satisfaction. The secret was never stolen in transit; it was simply never secret enough.
What remains is not the absence of trust but its redistribution.
A hardware wallet is a small device that generates and guards the cryptographic keys controlling a Bitcoin balance. The device does not hold the coins. The coins exist as entries on a distributed ledger maintained by thousands of computers. What the device holds is the authority to move them, encoded as a string of words derived from a number that is supposed to be random. The entire architecture of private ownership rests on the proposition that the number your device chose when you pressed the button could not have been predicted by anyone else on earth. However, the Coldcard’s number could be.
In 2021, Coinkite, the Toronto company that manufactures the Coldcard, migrated its cryptographic library. The migration was routine, and the new library was reputable. However, during integration, a function call that was supposed to reach the device’s hardware random-number generator instead resolved to a software fallback, a deterministic pseudorandom-number generator built into MicroPython. A hardware generator harvests physical noise, the kind of irreducible unpredictability that makes a secret genuinely singular. A software fallback produces numbers that look disordered but are fully determined by their inputs. Feed it the same inputs and it will produce the same outputs, every time, on every machine. The function returned bytes of the correct length in the expected format. The mnemonic phrase looked random, but it was not.
On older Coldcard models, the effective search space collapsed to roughly 40 bits, meaning an attacker had to consider about a trillion candidates rather than the intended hundreds of trillions. On newer devices, secure-element entropy raised the figure, but independent analysis found that only 32 bits of genuinely secret material survived in a critical reseeding operation. A trillion sounds like a large number, but it is not when the adversary has rented a cluster of GPUs and the public blockchain serves as a free answer key against which every guess can be checked in milliseconds.
The thefts were automated. On July 30, roughly 1,083 Bitcoin moved from 1,196 addresses in 41 minutes. Subsequent waves targeted thousands more. By early August, estimates ranged from 1,596 to over 2,000 Bitcoin drained across thousands of addresses, a sum approaching $130 million. The attackers did not need to know who owned the wallets or where the devices were stored. They needed only to regenerate the small universe of secrets those devices could ever have produced, derive the corresponding addresses, compare them against the blockchain, and sign. The protocol saw valid signatures, which is the only authority it recognizes.
RELATED: A shocking storage exploit bankrupts Bitcoiners — with lessons for us all
The Coldcard had occupied a particular niche in Bitcoin’s self-image. It was the serious person’s wallet, the one recommended on the forums and podcasts that prized operational security, air-gapped signing, open-source firmware, and a philosophy of radical self-reliance. Its marketing vocabulary was a compressed manifesto: sovereignty, verification, trust minimization. Two weeks before the mass thefts, Coinkite published an essay arguing that offline status alone was insufficient and that real security required architectural separation, trusted displays, secure elements, and reproducible builds. The essay ironically enumerated the locks on the doors in a house whose foundation was already fissured.
Bitcoin was designed to eliminate the need to trust institutions. You do not need to trust a bank to honor its ledger because the ledger is maintained by mathematics and distributed consensus. However, the self-custodying individual must trust or personally verify the firmware on the device, the compiler that built the firmware, the library the compiler linked, the symbol the linker resolved, the entropy source the symbol reached, the chip that generated the noise, the build system that packaged the result, the reviewers who examined the code, and the update channel that delivered the fix. One is trusting an entire institutional apparatus compressed into a plastic rectangle the size of a playing card.
“Do not trust; verify” is the community’s canonical imperative, but verification requires a division of labor. The user verifies an address on a screen. An auditor inspects the firmware. A reproducible-build operator compares binaries. A laboratory assesses an entropy source. No single person does all of these things, and almost no one does more than the first. What remains is not the absence of trust but its redistribution, away from a chartered institution with a complaints department and toward a dispersed, informal, largely volunteer apparatus of maintainers, reviewers, and forum participants whose oversight, in this case, missed a five-year-old defect in the most consequential function the device performs.
Jonathan Goodman’s safe was not breached. His backup was not photographed. His mnemonic words were not intercepted. The words themselves were simply a member of a knowable set, a predictable output dressed in the costume of randomness. The distinction between concealment and unpredictability turned out to be critical. While the Coldcard was offline, the institution that made the key never was.
I recently came across a short article in which the female half of an early-30s DINK (dual-income, no kids) couple in Charlotte, North Carolina, outlined their finances.
They make a combined income of about $380,000 per year. They have no debts other than a $450,000 mortgage, which they expect to pay off in the next seven years. They've accumulated $1.1 million in savings, to which they add about $8,000 each month. Other than gym memberships and an occasional dinner out, they rarely splurge.
'People can’t have kids if they can’t afford a house,' they say. Really? Are renters rendered sterile? I was unaware.
"I love our life together," she says. The only thing missing? Children. They definitely want them, but have chosen to wait until they "feel more financially secure."
You read that right. An otherwise financially literate couple thinks $380,000 per year is not enough to have kids.
Prudence is one thing; this is more like paralysis. And it's fairly widespread in 2026, as evidenced by a decline in both birth rates and general happiness.
How did the standards for a good life balloon so far beyond our ancestors’ wildest imaginings? How did people come to believe they cannot start a family without things their grandparents never possessed? And how did this historically anomalous idea come to seem perfectly reasonable?
There is no single explanation, but our inflated expectations seem to track alongside what is sometimes called “feature creep.” This happens when manufacturers continually add conveniences that, in theory, improve a product but eventually raise the baseline — and the price — to a once-unheard-of level.
My sister recently bought a new car. It is amazing. It can do all sorts of things, and despite not being a luxury model, it was quite expensive. She told the salesman, an old-car enthusiast, that she wished she could simply buy a basic car without all the bells and whistles. He agreed.
That is feature creep. The floor has risen so high that heated steering wheels, assisted driving, and iPads embedded in the dashboard are becoming standard equipment. The same thing has happened to houses and apartments, which are now expected to have renovated kitchens, new bathrooms, smart lights, smart thermostats, and every other costly convenience.
As our products have become more elaborate, so have our expectations for what constitutes a good life — and for what having children requires.
People have grown accustomed to so much comfort that they have lost the ability to adapt as their parents and grandparents routinely did in the not-so-distant past.
This is usually the point when someone brings up the housing market.
“People can’t have kids if they can’t afford a house,” they say.
Really? Are renters rendered sterile? I was unaware.
The Root family must have slipped through the cracks, because we have had children while renting and somehow survived. I am obviously sympathetic to the problem of exorbitant housing costs, but I am not going to pretend that home ownership is a prerequisite for having children.
My parents had me while living in an apartment. My father’s parents had their first child in an old Army tent pitched behind the farmhouse where they were staying for the summer. And that is only the 20th century. The farther back you go, the tougher it gets.
RELATED: You will never be 'ready'
The belief that renters cannot even contemplate starting a family is closely related to a couple earning $380,000 a year feeling too financially insecure to have children. Both are also distantly related to the depressive claims of online doom-mongers that life is harder than ever, when it so obviously is not.
No one starves in the United States today. It has been a very long time since that was a normal possibility. We have become so thoroughly removed from true want that we have forgotten what the word means.
After the extraordinary material abundance of the 20th century, it is perhaps unsurprising that millions of people developed unreasonable—and ultimately unsatisfiable—expectations for what they need before they can live well or bring children into the world.
The remarkable thing is that they sincerely believe it. Deep down, they really do feel that what they have is not enough, despite having more than their grandparents could have imagined.
Those DINKs in Charlotte really do believe that an income of $380,000 a year is not enough to start a family.
“This is the way the world ends
Not with a bang but a whimper.”
Most Americans believe a simple thing about their retirement accounts: If you buy a stock, you own it. Your statement shows the shares. The value rises and falls. And if you don’t panic-sell, the asset is yours.
That’s the commonsense view of investing.
If Americans believe they directly own the assets in their retirement accounts, the law should reflect that expectation — before the next crisis tests it.
But the law doesn’t treat your “ownership” the way most people think. In the modern system, most investors are not the direct registered owners of most securities. They hold contractual rights tied to the investment — not the security itself.
In calm markets, that sounds like a technicality. In a severe financial crisis, it could determine whether your assets stay yours.
Decades ago, investors could hold securities in their own names. Physical certificates were common, and ownership was straightforward.
As we explain in our new book, “The Next Big Crash: Conspiracy, Collapse, and the Men Behind History’s Biggest Heist,” that changed as powerful financial interests pushed to redesign the securities system. Big banks and Wall Street institutions worked to centralize ownership and reduce investor rights — changes that received little public attention and limited scrutiny.
Today most securities sit inside the Depository Trust Company system. DTC — through its nominee legal entity, Cede & Co. — appears as the direct registered owner of those securities, not you.
DTC is a subsidiary of the Depository Trust and Clearing Corporation, which is owned by the financial institutions that use it. DTCC is not publicly traded, so ordinary investors can’t own its shares.
RELATED: Bidenflation? Trumpflation? Try unipartyflation
The DTC structure was only the beginning. In the 1990s, lawmakers revised Article 8 of the Uniform Commercial Code — the state-law framework that governs securities ownership nationwide. Those changes formalized what we now have: an indirect holding system built around “security entitlements,” not direct title.
In plain terms: When you hold most securities through a brokerage account, you hold a legal claim against the broker. You typically do not hold specific, segregated property registered in your name.
That distinction matters because Article 8 also sets priority rules when an intermediary fails. If a brokerage pledges securities credited to customers as collateral for financing, the lender can obtain priority over other claimants. When multiple parties assert rights to the same pool of assets, the law decides who stands first in line — and customers are not always first, even when they paid for the investments and believed they owned them.
In the next major crash, if a Wall Street firm uses customer assets to prop itself up, ordinary investors could take heavy losses. And that can be true even if the firm wasn’t allowed to use customer assets that way. Article 8 was written to protect large institutions first and investors second.
Brokerage firms operate under customer-protection and segregation rules. The Securities Investor Protection Corporation offers limited coverage in certain failures.
But those safeguards don’t erase Article 8’s priority structure. SIPC coverage is also too limited to address widespread losses in a broad crisis. And even when a broker violates rules, a secured creditor’s priority claim can survive unless the creditor itself acted in bad faith or colluded.
In a cascading crisis — multiple failures, margin calls, forced liquidations, and liquidity freezes — these limitations stop looking academic. Article 8 determines whether customer assets remain with customers or flow to institutional creditors.
RELATED: Washington printed promises. Gold called the bluff.
For decades, policymakers sold this transformation as technical modernization. Trading volumes rose. Paperwork bottlenecks appeared. Those problems were real.
But the “solution” did more than speed settlement. It changed who holds legal title and who gets paid first when stress hits.
In ordinary times, the structure runs quietly. Investors see statements, dividends, and confirmations, and few ask how the system records ownership.
The difference becomes decisive when an intermediary fails. At that point, priority rules — not your assumptions — govern what happens next.
There’s still a path forward.
Because the Uniform Commercial Code is state law, state legislatures can strengthen investor protections and clarify priority rules. Reform doesn’t require blowing up modern markets. It requires aligning the legal structure with what ordinary Americans reasonably believe they own.
The next financial crisis will arrive sooner or later. What’s already set is the legal framework that will govern when it does.
If Americans believe they directly own the assets in their retirement accounts, the law should reflect that expectation — before the next crisis tests it.
Last week, a bipartisan group of senators introduced legislation on drug prices that specifically targets pharmacy benefit managers, exactly as Big Pharma prefers. Pharmaceutical companies have spent years trying to convince the public and policymakers that PBMs are the bad guys in the prescription supply chain, shadowy middlemen inflating prices and hurting innovation. That narrative is convenient, but it is also wrong. PBMs are introducing competition, eliminating waste, and driving down prices.
Which is precisely why Big Pharma wants them out of the way.
The truth is that pharmacy benefit managers are effective. And that is exactly why drugmakers are going after them.
The pharmaceutical industry spends more money than any other sector to sway government policy. In 2024, it poured $90 million into campaign contributions and nearly $400 million into lobbying — much of it through former government officials now on the payroll. Drugmakers also shelled out a whopping $11 billion on advertising, a sum that conveniently buys more than consumer attention. It pressures media outlets to look the other way, a racket the Trump administration is finally moving to rein in.
After the black eye of the opioid crisis and the COVID-19 debacle, Big Pharma needs a scapegoat for high drug prices. It found one in a quiet, little-known player most Americans have never heard of, much less understood.
But the numbers are clear. A recent study shows pharmacy benefit managers deliver at least $145 billion in net value every year, even after costs. Compared with a system where manufacturers dictate prices, PBMs create an additional $192 billion in value across the economy. That money doesn’t vanish into corporate coffers. It flows back into businesses, households, and the wallets of working Americans.
PBMs accomplish this by negotiating directly with manufacturers and pharmacies. They aggregate buying power for millions of people. They secure rebates and discounts that most individual plans could never get on their own. In 2020, PBM-managed rebate structures created $51 billion in value for patients and plan sponsors. That is a competitive market in action.
PBMs are expected to save health plans and consumers about $1.2 trillion over the next 10 years, averaging $1,154 per person per year. And for every dollar spent on PBM services, the system saves $10 in return. By steering patients toward generics and bio-similars, PBMs helped the health system save $445 billion in 2023 alone. That is what efficiency looks like.
Perhaps more importantly, they improve health outcomes. When patients can afford their prescriptions, they are more likely to take them. That means fewer hospitalizations and fewer emergency room visits. PBM-driven programs have led to as much as a 16% increase in medication adherence and a 10% drop in inpatient admissions.
RELATED:How MAHA can really save American lives
It’s an obvious good to have healthier Americans. But it’s also good for a productive economy.
By lowering premiums and drug costs in public programs, PBMs save taxpayers money as well. This alone accounts for $47 billion in annual savings. And by accelerating patient access to new therapies early in the patent cycle, PBMs support pharmaceutical innovation instead of stifling it.
PBMs currently manage 95% of retail prescriptions and serve 91% of plan participants. That’s because they work. Businesses in the free market use services they value. And they value PBMs because they allow employers to offer more affordable coverage without sacrificing quality.
The truth is that PBMs are effective. And that is exactly why drugmakers are going after them. PBMs bring down net prices and demand accountability. That cuts into Big Pharma’s profit margins. So the industry has launched a campaign to reframe PBMs as a problem rather than a solution.
For example, a Biden-era Federal Trade Commission report that painted PBMs in a negative light should be viewed with skepticism. Even FTC Commissioner Melissa Holyoak emphasized that the report ignores the hard evidence of PBM-driven savings and warned that it was “a premature and deficient report,” adding, “Our job is not to score cheap points for transient political favor.”
“Though facile arguments that rely on ideologically loaded buzzwords such as ‘control’ or ‘power’ may stir emotions and make for entertaining social media posts and television interviews, ideological buzzwords are no substitute for rational, evidence-based research,” Holyoak said.
Sadly, some lawmakers are swallowing Big Pharma’s spin. Bills moving at both the federal and state level would gut PBMs — and hand drugmakers exactly what they want. Even a Brookings Institution analysis found that targeting PBMs won’t lower costs and would only weaken bargaining power against manufacturers.
That isn’t reform. It’s malpractice. Weakening the only players who force price discipline amounts to doing Big Pharma’s bidding at the expense of patients.
This fight isn’t about patients versus middlemen. It’s about competition versus monopoly. It’s about market discipline versus unchecked corporate power.
PBMs work because they negotiate, they drive better drug choices, and they deliver real value. When the most powerful industry in America is desperate to kill them off, you don’t need a think tank study to see what’s at stake. That fact alone tells you everything you need to know.
One of the late comedian George Carlin’s most famous rants gave us the line, "It's a big club ... and you ain't in it.” That sentiment rings especially true when it comes to the financial services industry, where wealthy investors and insiders gatekeep the most lucrative opportunities for themselves and their friends.
So what should you think when they suddenly want to let you in?
The private equity party is a bit dim right now, and that’s why they are sending out more invitations. Be careful before you RSVP.
There's no red flag bigger than when someone wants to let you in on something very exclusive — especially if it’s from people who’ve spent decades keeping you out of the club.
Case in point: the private equity industry’s latest push to open its funds to everyday retail investors.
The private equity world is one I know well, as a recovering investment banker who works with a firm to evaluate deals. My husband also worked in the sector. Like any other industry, it has both good and bad players.
Private equity involves deploying capital to buy ownership stakes in private companies, distinct from equity invested through the public markets in publicly traded companies. These firms are often actively involved with the company, as opposed to the more passive investing in public market companies. Their stakes are typically substantial, often including majority ownership.
The good players in private equity provide capital, professionalization of businesses, governance, business insights, and capital for growth. They may reward employees with an ownership stake to align incentives.
Some private equity players, however, focus on financialization — that is, playing around with the capital structure of a company and not adding a lot of value otherwise. Private equity is rife with examples of firms that have ruined businesses with too much leverage and engaged in a variety of greedy — and often, outright abhorrent — behaviors.
But this latest trend isn’t about good firms versus bad firms. It’s about the broader industry’s poor performance — and desperation.
Private equity has a problem. Too much money has flooded the space in recent years, driving up valuations and pushing down returns. Funds are struggling to find new investors to cover their high management fees. So now they’re turning to you.
They aren’t suddenly being generous. They’re just trying to survive.
According to the Financial Times, a major private market index has underperformed the S&P 500 over the past one-, three-, five-, and 10-year periods. Any outperformance was skewed toward earlier years — and even then, it came with significantly higher fees and far less liquidity.

This underperformance comes with heavy fees and a lack of liquidity for your investment. It's not a coincidence that you are seeing private equity opening up to retail now when it is struggling from deal competition, higher valuations, higher capital costs, and slower deal exits.
RELATED: Red states get it: Economic freedom beats blue-state gimmicks
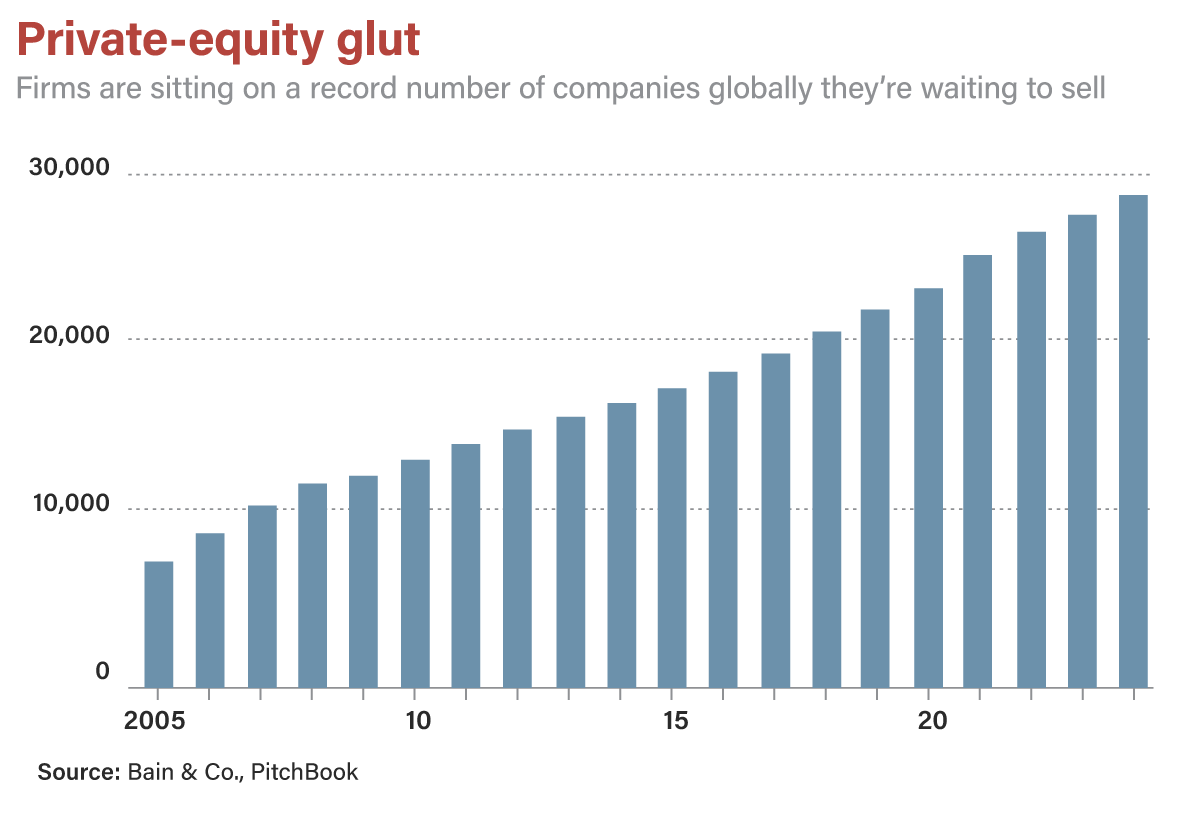
Speaking of slower exits, the Wall Street Journal noted that “private equity remains the biggest fee generator for the broader Wall Street ecosystem of banks and advisers” and that private equity firms are sitting on a record number of companies that they are waiting to exit — that is, sell and record a profit ... or a loss. Longer hold times for private equity firms mean they are not returning capital to their investors, and, in turn, the investors are not reinvesting in the latest and greatest fund.
Whether it’s the new push to allow private investments into your 401(k) or your financial planner calling you with “new, exciting alternative investment opportunities,” please be appropriately skeptical. Always probe a fund’s track record (especially over the past several years), fee structure, and whether it is a fit for your objectives and goals.
The private equity party is a bit dim right now, and that’s why they are sending out more invitations. Be careful before you RSVP.
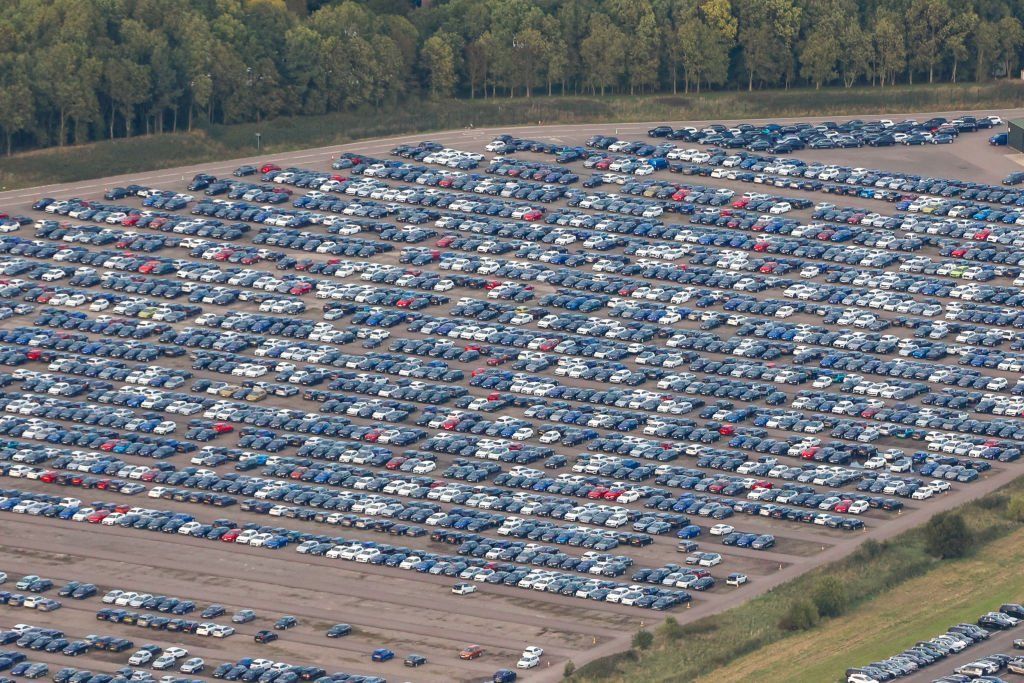
Unsold inventory has car dealers feeling the pinch — which means there's never been a better time to buy.
Before 2020, it was unusual for a new car to sit on a lot for more than 200 days. Now we're seeing cars not move for 500, 600, and even 700 days — thanks to a combination of car supplies returning to pre-COVID levels and rising prices.
As a dealer trainer for different brands and dealership groups, I've seen the problems excess inventory causes up close — and it's not pretty.
Quite a change from just a few years ago, when many dealerships took advantage of the chip shortage (and the ensuing vehicle scarcity) to charge as much as $15,000 over sticker price.
The tables have turned — and no automaker is exempt. Ford, Honda, Kia, Chevrolet, even Ferrari: You name the brand, and you'll find dealerships stuck with vehicles from 2022, 2023, and even 2024.
With 2025 models arriving, this is a problem.
As a dealer trainer for different brands and dealership groups, I've seen the problems excess inventory causes up close — and it's not pretty.
Car dealers purchase vehicles on a floor plan, essentially a revolving line of credit. This can be interest-free for the first 60 to 90 days. Ideally, you sell within that period. If you don't, rates get pretty high, and it all adds up quickly when you're talking about inventory totaling hundreds of thousands or millions of dollars.
Dealers are highly motivated to get these mobile money pits off of their books. They'll offer incentives (or "spiffs") to the sales team to get them sold. And salespeople will offer potential buyers spiffs of $500 to $1,000.
If that doesn't work, the dealership will often simply pay off the car to relieve the debt. Many times the dealer principals will drive an unsold car for a few years, then sell it at auction for a fraction of the price or even donate it to charity.
Sometimes taking a loss is the smartest business decision — every so often. But 10 or 20 losses are a different story.
Alternatively, the dealership could also use such a car as a demo vehicle or as a loaner car for the service department. Although with this option, rising insurance costs are still a burden.
So what does all this mean for you? In short: big savings.
Remember: Dealers are highly motivated to sell their inventory. Alway ask for the deal — loyalty or conquest discounts could mean between $500 to $2,500, depending on the cost of the vehicle. You can pay less than MSRP on even the most in-demand models, so look around. And don't be afraid to drive out of state to buy — it could mean saving thousands of dollars.
And if you're not picky, look for cars in unpopular colors or trims or older model years. Or consider picking up a demo car or a service loaner.
It's a buyers' market, so negotiate with confidence. And that includes dealer fees — they're not set in stone either.

 College 'name, image, and likeness' deals are seducing young athletes into making rash financial choices with long-term ramifications.
 These days, a million-dollar 401(k) doesn’t guarantee a cushy retirement.
 In May, 400,000 fewer Americans had jobs than in April. The so-called net jobs ‘added’ by Biden are actually some Americans working extra jobs.
 www.theblaze.com
 thefederalist.com
 www.theblaze.com
 www.theblaze.com