No, digital is not always best
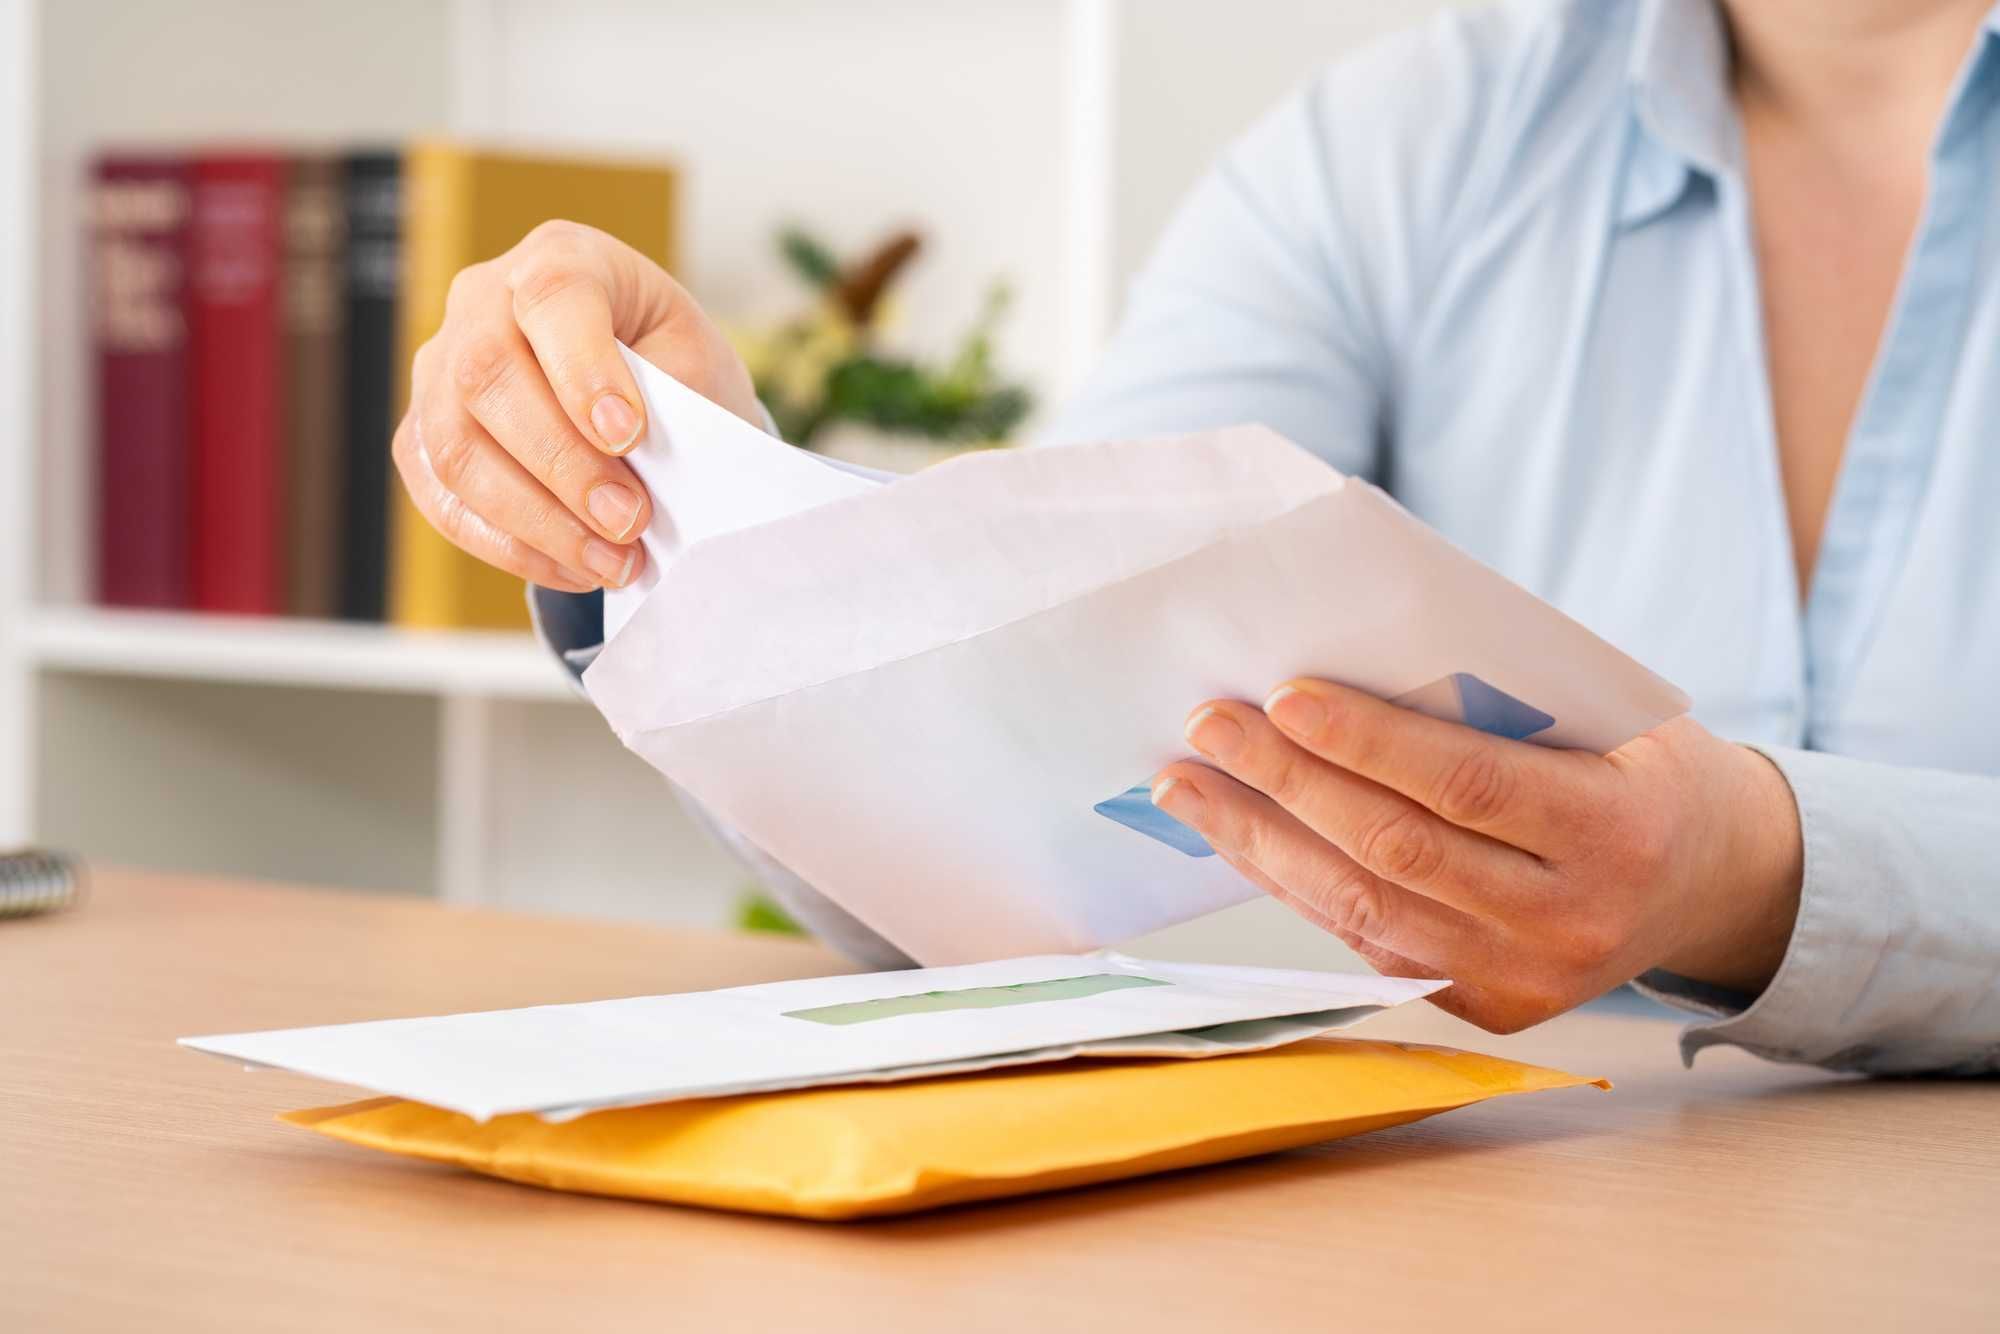
In today’s digital world, it’s easy to think that everyone loves everything digital. After all, many businesses conspicuously post a “No Cash Accepted” sign in their windows, and it’s getting increasingly harder to remember the days when no one needed a charged cell phone to get into a concert or board an airplane.
But don’t let this electronic ubiquity fool you. Lots of people still prefer paper bills, statement printouts, physical mail, and other such hard copies.
The proposed rule plays right into the hands of scammers and identity thieves.
Let’s dig in a little on this.
The U.S. Department of Labor and the Securities and Exchange Commission are each proposing a rule, “Regulation E-Delivery,” that would switch from paper to digital the default way that Americans receive certain critical communications. In other words, this new rule would mean that Americans would automatically receive communications electronically and would affirmatively have to ask to revert to paper delivery.
Let’s look at each one of these entities separately.
The DOL’s proposed rule would automatically move Americans to electronic delivery of their health plan documents, unless they actively work directly with their insurers to revert to paper delivery. This move would risk vulnerable Americans having more difficult access to — or missing altogether — critical health insurance information if they miss a notice or can't reliably access the internet.
Americans should have the right to choose how they receive critical health plan documents, like HIPAA and COBRA notices, benefits summaries, and other important disclosures. Regulation E-Delivery would flip the choice from automatic-paper to automatic-digital, resulting in major hurdles for specific populations, particularly seniors, rural residents without reliable internet, and low-income households.
The proposal would automatically move people to Regulation E-Delivery, unless they actively work with each insurer to restore paper delivery. This is the opposite of how the system should work. People should not default because they miss a notice or because — like most people — they have trouble navigating large corporate bureaucracy.
The people most comfortable with Regulation E-Delivery are the most tech-literate folks and can much more easily opt-in under the current system. Those who depend on paper often lack that same digital literacy. This effort seems like a solution in search of a problem that doesn’t exist.
Right now, people who want electronic delivery can easily choose it, and those who want paper can keep getting it without having to do anything. There's no reason to flip that on its head.
Some people argue that this proposal is a cost-saving measure, but is that really believable?
Health insurance companies have a history of pocketing savings and not passing them along to their customers. Also, has anyone done a serious analysis of the costs to consumers for missed notices or out-of-date information? This proposal leans heavily on cutting corporate paper, printing, and postage costs, without seriously weighing what that means for the people on the receiving end.
RELATED: Silicon Valley is building a god in its own image
The SEC's proposed Regulation E-Delivery would make electronic delivery the default for sensitive financial documents, reversing today's arrangement where those documents arrive on paper, unless for them electronically.
The Regulation E-Delivery hurdles would be much more complicated than a simple “opt-out” checkbox. Investors could be required to contact each financial firm separately — through multiple websites, portals, or telephone systems — to preserve or restore paper delivery across their accounts.
This mandate disadvantages folks who either are not as savvy with digital communications or who have unreliable internet/cell service. These people would be the least likely to successfully navigate the many barriers that this new rule would require to preserve paper communication.
The proposed rule plays right into the hands of scammers and identity thieves by requiring the same basic “click the link” actions that investors have been conditioned to avoid.
Some people simply prefer physical copies of certain things. Perhaps you’re the type of person who prefers a physical book — not an e-reader — to read on the beach. Or perhaps you’d rather have a printed, rather than a texted, receipt from a restaurant. Similarly, many Americans still prefer important health care and financial documents in paper form, as they can be easier to read, file, and refer to.
It also is questionable whether a paper option would even remain that long if Regulation E-Delivery goes into effect. Millions of Americans have learned the hard way that the federal government’s promise of consumer choice is not always worth the paper it’s printed on.
Remember when President Obama promised Americans that they could keep their doctors under Obamacare? Forgive us if we take the Regulation E-Delivery promise of enduring choice between paper and electronic delivery with a similar dose of skepticism.
The DOL and the SEC should reject this proposed rule and keep the current system, where Americans can keep what they have now or choose for themselves whether they want to switch to digital.
 The U.S. Department of Education recently released test results of the National Assessment of Educational Progress, showing that American high school seniors’ math and reading scores have dropped to a new historical low. According to The Wall Street Journal, “Twelfth-graders’ average math score was the worst since the current test began in 2005, and reading […]
 Rather than facing the consequences of the law they rammed through Congress, the Biden administration decided to tap taxpayers instead.
 Move over, AARP. A conservative competitor that rejects the AARP's liberal political agenda for seniors has 2.2 million members and growing.
 The federal government's onerous regulations on HSAs have limited their availability to all but the luckiest American workers.


 www.theblaze.com
 thefederalist.com
 www.theblaze.com