It just got easier to pay at Walmart, if you follow these simple steps
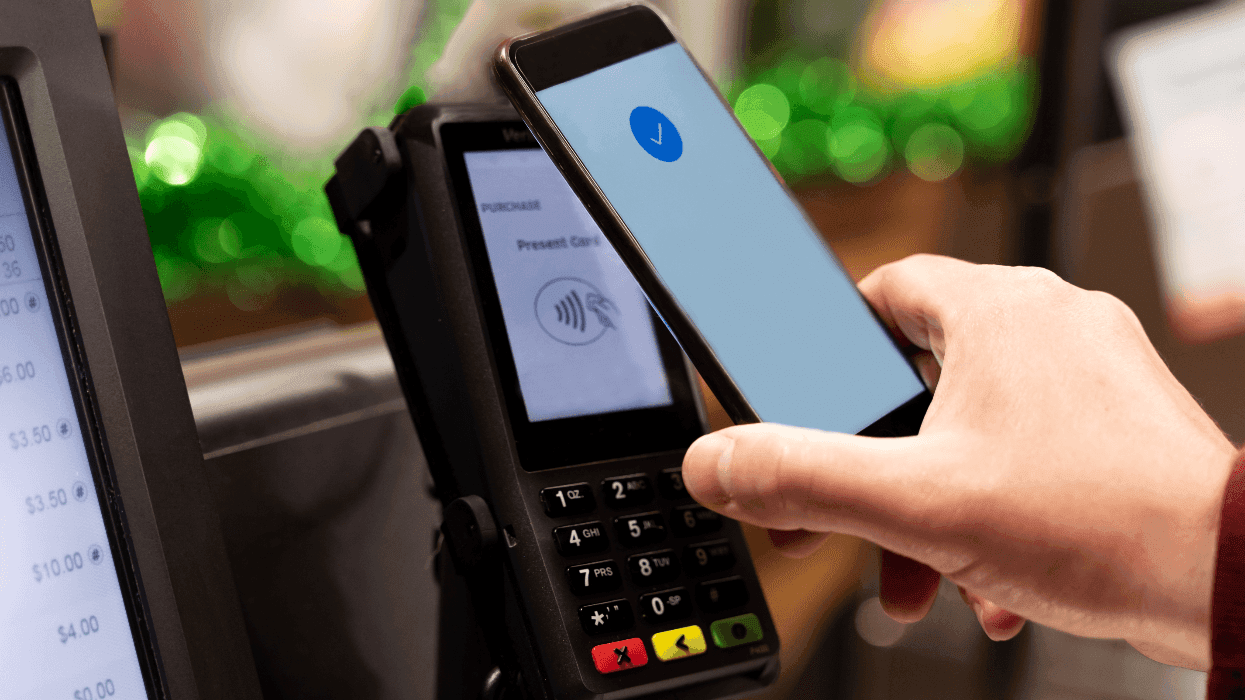


Mobile-based contactless payment services are 15 years old, starting with Google Wallet in 2011 (which later became Google Pay), followed by Apple Pay in 2014. Many stores slowly rolled out support over years of foot-dragging, while large chains like Walmart tried to push their own payment solution. However, after nearly two decades of hemming and hawing, the retail giant is finally caving in. Here’s what you need to know before the next time you try to buy something at Walmart with Apple Pay or Google Pay.

While Google was the first to bring contactless payments to mobile, the industry took notice when Apple introduced its own solution to the market. Built around the wildly successful iPhone and Apple Watch, Apple Pay quickly picked up steam. Today, it accounts for 50% of in-store transactions in the United States, while Google Pay only covers 17%. Globally, that makes up a difference of $9.5 trillion spent through Apple’s ecosystem versus $5.2 trillion on Google’s platform.

The rollout has already begun at select locations.

It wasn’t always that way, though. In the earlier days of contactless payments, the market was more like the Wild West with various companies jockeying for control. Some stores even launched their own payment services to compete.

Walmart Pay ruined the party

Walmart released Walmart Pay in 2015 as a direct in-store alternative to Apple and Google. The key selling point, at least for Walmart, was that its payment service worked with a QR code system. That meant any customer could use any phone to scan the code at the register to connect to their Walmart account and submit a payment.
RELATED: A YouTube stunt proved this Apple Pay exploit can drain your bank account in seconds. Here's the fix.

NanoStockk/Getty Images

Unfortunately, the process was clunkier than Apple Pay and Google Pay, which only required users to hover their devices over payment terminals and authenticate with a fingerprint or FaceID. Walmart Pay also gave the retail giant the power to monitor customers’ purchases and link them to their accounts — a stark difference to Apple Pay and Google Pay that hide identifying customer information and transaction data from merchants.

In other words, Walmart Pay gave the company insight into customers’ shopping habits that it couldn’t get from other platforms ... until now.

Contactless payments are coming to Walmart

After all these years of waiting, Walmart announced that it is finally giving customers the choice to use other contactless payment options. As a result, customers will soon be allowed to complete purchases with Apple Pay and Google Pay at the register in Walmart stores and Sam’s Clubs nationwide.

The rollout has already begun at select locations, and all stores will have access to these services by the end of 2026. After that, Walmart and Sam’s Club fuel stations will gain contactless support by mid-2027. This change also means that customers should have the option to use contactless payment credit cards and debit cards with EMV chips, as well.

How to make sure your phone is set up for contactless payments

Now that you can buy things with your phone at Walmart, you’ll want to make sure your device is set up before you walk into the store.

To add a card to Apple Pay, open the Wallet app on iPhone, select the plus symbol in the top right corner, and choose “Debit or Credit Card.” From there, you can place your iPhone against the card to add it automatically through the EMV chip, or type in the card details by hand. Once the card is added, you may have to verify the information with your bank or credit union through the bank’s official app or via a text or phone call. Do this, and you’re all set to use Apple Pay.
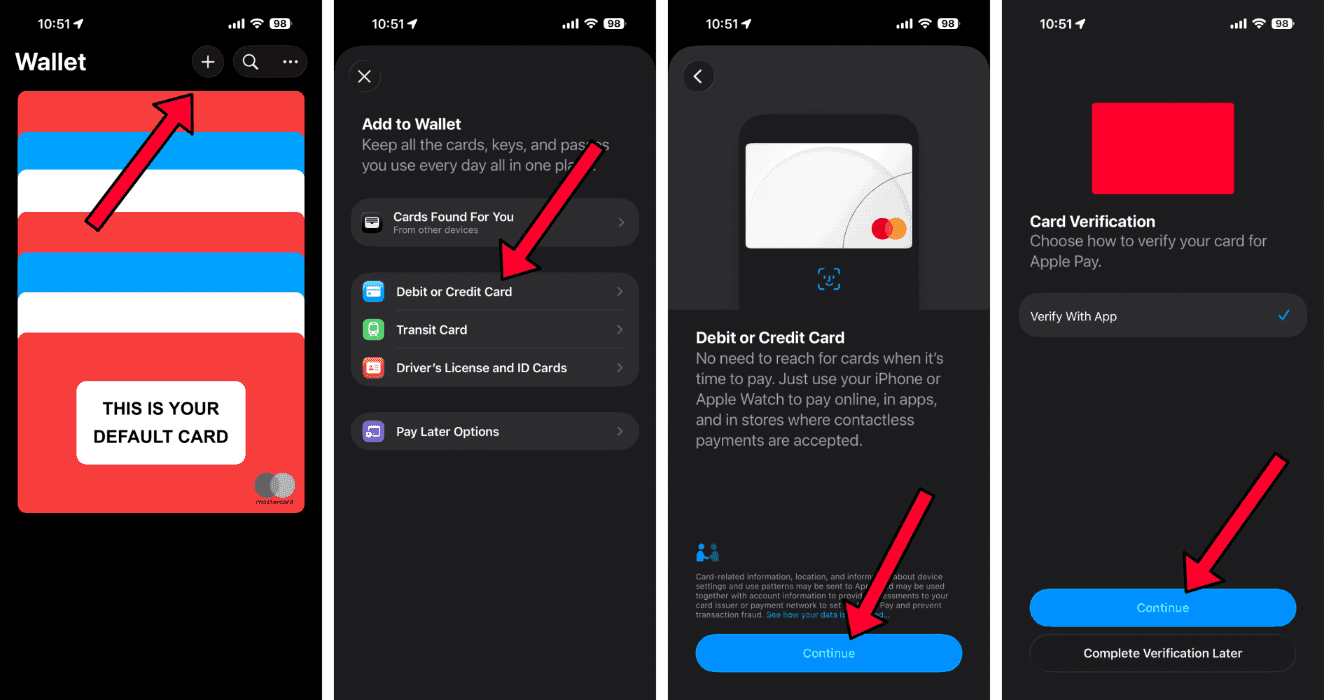
Screenshots by Zach Laidlaw/Apple Pay

On Android, open the Wallet app and tap the plus button at the bottom. On the next screen, select “Payment card,” then “new credit or debit,” and let the app take a photo of your card to add the details. You can also write them in manually, if you prefer. Verify the information with your bank or credit union, and you’re all set to use Google Pay.
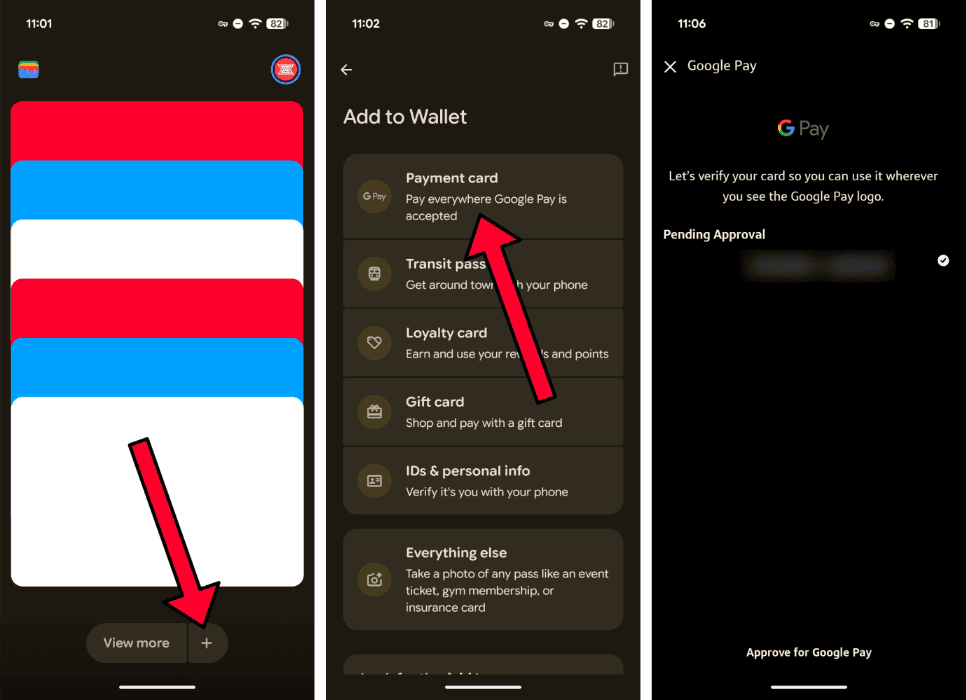
Screenshots by Zach Laidlaw/Google Pay

In the end, contactless payments on iPhone and Android are more convenient and secure than tapping your credit card at the register or trusting an alternative payment solution, like Walmart Pay.

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

10 Ways You’re Wasting Money At The Grocery Store And What To Do Instead

Saving money on groceries doesn't mean living on instant noodles. Becoming a smarter and more flexible cook will take you to another level beyond noodles.

American Parents Spend More Energy Picking A Backpack For Their Kid Than Picking His School

We do not make the child fit the backpack. We keep looking until we find the one that fits the child. Education deserves at least that much imagination.
This throwback app is competing with Big Tech — using a business model out of the 1980s


The future of commerce is not some complex algorithm; it's essentially the same as it has been since the 1980s.

That's the gambit of a hugely successful new company putting up numbers that rival tech's biggest.

Its latest valuation is a monstrous $20 billion, which is already a huge leap from its October 2025 numbers. The company has nearly doubled its valuation in those 10 months, up from $11.5 billion which secured an investment of $225 million.

That $11.5 billion valuation came less than a year after the company raised $265 million in January 2025 off of a $4.97 billion valuation.

This all means that the commerce app has quadrupled its value in about 18 months, something very rarely seen in its sector.

And that has the industry buzzing.

'We only exist to the extent that we provide our customers a lot of value.'

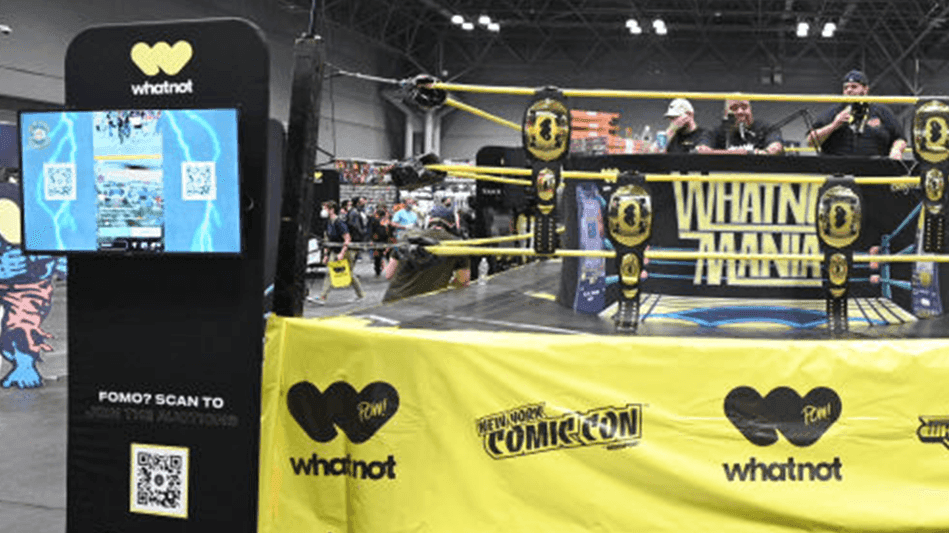
Meet Whatnot. It's based on an incredibly simple idea. Picture a cable channel with a 1-800 number, but it's a livestream on your smartphone or computer.

That simple difference is what sets the livestream auction app apart from that staple of late-20th-century television, the home shopping channel. The buy-from-home TV programs exploded into popularity with the introduction of the Home Shopping Network back in 1982.

Whatnot has sellers present their items just as they did on TV back in the day, urging viewers of the livestream to buy before the time runs out.

As the Next Web puts it: "The urgency of a live sale, the countdown, the banter, the scarcity, does work that a static product page never could."

RELATED: Dumpster-diving women claim they make $5,000 per month off discarded Louis Vuitton wallets and Michael Kors bags

Whatnot co-founder and CEO Grant LaFontaine. Eugene Gologursky/Getty Images for Fast Company

The Next Web reported that the company handled about $8 billion worth of livestream sales over the past year in North America and Europe alone, which helps justify its massive valuation to backers, markets, and industry insiders.

Looking at the backers, perhaps it should have been obvious Whatnot would enjoy a big upward trend: Andreessen Horowitz, Sequoia, Lightspeed, and Google's CapitalG are all involved.

Those investment firms are strongly associated with the venture capital scene, and indeed the only other companies making the same kinds of leaps in valuation as Whatnot are in the tech space. Companies like OpenAI, SpaceX, Nvidia, Tesla, and ByteDance are some of the comparable valuations in recent history, some of which far exceed a 4x jump.

The spike is largely driven by Whatnot's rampant consumer base, which logs an insane amount of time on the app.

RELATED: BRONCO BUSTED: I caught Ford sneaking my data — and uncovered an even bigger threat

Bryan Bedder/Getty Images for ReedPop

Co-founder and CEO Grant LaFontaine wrote in 2024 that buyers spent more than 80 minutes per day on the app that year.

Grant previously worked in product roles at YouTube and Facebook and co-founded Kit, a merchandising company that was acquired by Patreon in 2024.

LaFontaine said in May that success comes down to being willing to put in hard work while also being willing to be wrong.

"We only exist to the extent that we provide our customers a lot of value," he told Fast Company.

"If you want to build a customer-centered culture," the CEO added, "you have to actually follow through on building one and inject it everywhere you possibly can in the organization."

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

15 Effective Alternative Health Products With Great Black Friday Deals Right Now

Our family does weird health stuff that I'd like to share with all the millions of other folks interested in weird health stuff.
5 Ways I’m Prepping For Thanksgiving, Advent, And Christmas Right Now

Mothers are the festivity makers of the home and the world, and making holidays is quite a big production.

Bed Bath & Beyond Joins Countless Other Companies Ditching Bad-For-Business California

Despite these troubling economic conditions and many businesses leaving, it seems unlikely that Gov. Newsom and the Democrat majority in the legislature will change their ineffective policies.
A woman gave me flowers at Walmart; I didn't save them for my wife


The other night I went to Walmart to buy formula for my son. I’ll be honest; it wasn’t a good trip at first.

Traffic was annoying. The parking lot was fulI. But what really put me in a bad mood was the process of picking up the baby formula itself.

Although I give my wife flowers every year, I didn't give her those daisies.

It used to be available for anyone to grab right off the shelf. Now, in yet another sign of the erosion of basic social trust, it's been moved to the front of the store, where it's kept under lock and key.

Bad mood rising

This turned a quick errand into something way too complicated. Granted, getting someone to unlock the formula cabinet only cost me an extra five minutes, but in Bad Mood Time that's more like 20.

It didn't help that I now had to be escorted with the formula to the checkout line. Thanks, shoplifters.

As I impatiently waited to check out and go home, I noticed that the woman in front of me was buying flowers alongside what looked like the ingredients for a fun date night.

"Have you ever bought flowers for a man?” she asked the cashier.

The cashier responded "no."

“I buy my husband flowers every year," said the woman. "Men don’t ever get flowers until the day they die.”

First time for everything

I saw her look my way. I said, “I’ve never been bought flowers.” The man behind me said the same.

The woman then asked the cashier to add two more bouquets to her tally. She turned to us and said, "I’m buying you guys flowers. Give them to your wives or kid, but this way, at least you were given flowers before you die.”

And sure enough, as I walked out, the woman found me and gave me a bouquet of daisies.

Here's what she didn’t know. Although I give my wife flowers every year, I didn't give her those daisies.

I gave them to another woman, a woman I also think of every year right around this time.

Visiting a friend

She was a friend of mine. Thirteen years ago this month, I lost her to suicide. I was the last person ever to text her. I had been trying to help her through a recent tragedy. In the end, my help wasn't enough to prevent the outcome I feared.

She is buried near my house. I visit her every year around the anniversary of her death. I always leave her a bouquet of flowers and a little horse figurine (she loved horses).

This year, my friend will get two bouquets. I'm thankful for that woman in line at Walmart. Her simple act of generosity freed me from my selfish misery — my irritation, my impatience — by directing my attention to an old, dear friend. Not a bad lesson for Valentine's Day.

These 24 Christmas Gifts Are Way Better Than The Sponsored Junk You’ll Find On Google Shopping

Here's an assortment of gifts you'll like better than the $56 Mike Wazowski bracelet charm that Google thinks you want.
Target to stop accepting this type of payment next week


Target has announced plans to stop accepting a classic form of payment starting next week.

Target will no longer accept personal checks from customers starting on July 15.

To justify the decision, the massive nationwide retailer cited that shoppers rarely utilized the traditional payment method.

“Due to extremely low volumes, we’ll no longer accept personal checks starting July 15,” a representative for the company wrote in a statement, according to KTLA. “We have taken several measures to notify guests in advance to aid an easy and efficient checkout experience.”

The Target spokesperson attempted to calm the fears of check users by pointing out all of the forms of payment that the Minnesota-based retail behemoth does accept.

“Target is committed to creating an easy and convenient checkout experience, and that includes providing our guests with numerous ways to pay, including our new Target Circle Cards (formerly known as Target RedCard); cash; digital wallets; SNAP/EBT; buy now, pay later services; and credit and debit cards,” the spokesperson said.

Target's website notes that its stores do not accept the following payment options:

  • Foreign checks and currency: Target doesn’t accept currency or coins from foreign countries. However, depending on where the Target store is located, stores may be able to accept Canadian dollars or Mexican pesos. Target stores update exchange rates weekly.
  • Mall Certificates and Chamber Bucks: Exception - select stores accept payments using mall certificates or chamber bucks. Call your local store to find out if they are accepted.
  • Money orders and cashier's checks: Only accepted as payment on credit accounts
  • Business checks are not accepted.
  • Merchant gift cards (e.g., Disney), except Starbucks gift cards (which can be used at the in-store Starbucks registers)

The Federal Reserve has noticed that the use of personal checks has declined significantly in recent years. The Federal Reserve Payments Study – which collected data for the 2021 calendar year – discovered that checks used for payments declined at a rate of 7.2% per year since 2018, dropping to 11.2 billion in sales.

Despite the drop in the number of checks used, the value of checks increased from $1,908 in 2018 to $2,430 in 2021. The increase stems from fewer checks being written, but they were still used for higher-priced transactions such as rent and automobile purchases.

Accelerating the decline of personal checks was the COVID-19 pandemic, as more customers and businesses adopted contactless and digital payment methods.

Experts believe the use of personal checks will only continue to decline as more people utilize typical digital payments and up-and-coming cryptocurrencies.

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!