A shocking storage exploit bankrupts Bitcoiners — with lessons for us all


Coldcard, one of the better-known hardware wallets in the Bitcoin world, shipped a firmware bug that weakened the secret keys protecting customers' money. By Saturday afternoon, Galaxy Research had identified three waves of suspected theft totaling 1,367.05 Bitcoin, worth about $88.6 million, across 4,585 addresses.

That is the observed damage, not necessarily the final bill. Galaxy's method spots a particular attacker's habits on the public Bitcoin ledger. The researchers warn that another thief could change a few details and blend into ordinary wallet traffic, making additional thefts much harder to count. An address is not the same thing as a person, either, so 4,585 addresses does not mean 4,585 victims. The actual number of people robbed remains unknown.

The danger had not passed by Saturday evening. Galaxy warned that exploitation was ongoing and said it had sent roughly 600 suspected attacker holding addresses to federal investigators, compliance teams, and independent cyber investigators.

Coinkite says it must assume somebody used artificial intelligence.

Coldcard gave the same warning Sunday: "The threat remains real and ongoing".

If your Coldcard generated the seed words for your wallet on affected firmware, do not assume that installing an update makes the existing wallet safe. It doesn't. Coinkite, the company behind Coldcard, says users must install corrected firmware, create an entirely new seed, verify it, and move their Bitcoin.

If that's you, move it carefully. Panic is how a security emergency becomes a second security emergency.

That's the first lesson for us all.

What a Coldcard actually does

Bitcoin never sits inside a Coldcard. The coins remain on Bitcoin's public ledger. The device protects the private keys that authorize a transaction, while a 12- or 24-word seed phrase is the master backup from which those keys can be recreated. Whoever can reconstruct that seed can spend the money. The Coldcard documentation explains that its devices generate BIP-39 seeds and derive wallets from them.

Coldcard appealed to the sort of Bitcoin owner who takes security seriously. It is Bitcoin-only, which keeps the codebase narrower. It can sign transactions while separated from an internet-connected computer, passing a partially signed Bitcoin transaction by MicroSD card or QR code. Its firmware can be inspected, and its current models use dedicated secure-element chips to guard secrets. Those features are the core of Coinkite's security pitch, and they address real risks.

An air gap helps prevent malware on a laptop from reaching into the signing device and stealing a private key. The Coldcard can examine and sign a transaction without handing that key to the online machine. Signed transaction data comes back across the gap; the private key does not. That is how the company's offline signing workflow is designed.

The air gap did not stop this attack.

The attacker did not need to connect to the Coldcard, crack its PIN, break into a safe, intercept a MicroSD card, or trick the owner into approving a transaction. The vulnerable wallets were in trouble from the moment their seed phrases were created.

The keys looked random. They weren't random enough.

Bitcoin security depends on numbers so large and so unpredictable that guessing the right one is, for all practical purposes, impossible. A properly generated Coldcard seed was intended to have at least 128 bits of entropy. Think of entropy as the size of the field an attacker must search. At 128 bits, the field is absurdly large.

Coinkite now estimates that affected Mk2 and Mk3 seeds had roughly 40 bits of effective entropy. Later Mk4, Mk5, and Q devices mixed in additional material, but the company estimates that affected seeds from those models reached only about 72 bits. Coinkite published those preliminary figures in its technical account of the bug. Block's independent engineering analysis is even less comforting: On later devices, only 32 bits from the secure-element digest reached the software generator's state, and hashing the resulting output could not manufacture entropy that was never there.

RELATED: Your private chatbot data is at risk. Here's what to watch for
Moor Studio/Getty Images

Here is the short version. In March 2021, Coinkite changed the code used to create wallet seeds while integrating the same elliptic-curve library used by Bitcoin Core. The cryptographic library was sound. The plumbing was not. A call that was supposed to reach the Coldcard's hardware random-number generator instead resolved to MicroPython's deterministic software fallback, seeded largely with a device identifier and timing values. Coinkite says the vulnerable change reached seed generation in its 4.x firmware; Block traces the underlying code change to March 1, 2021.

The software fallback supplied the rng_get() function the build expected, with the same signature as the intended implementation. The hardware code was present in the finished firmware, so earlier reviews confirmed that it existed. They did not verify that the seed-generation path actually reached it. A preprocessor check also asked whether a setting existed, not whether the setting was enabled. Nothing in the build process caught the mismatch, and seed creation kept calling the deterministic fallback. Coinkite's explanation is unusually candid about how its review missed the failure.

That's our second lesson. Even a savvy company doesn't inherently rise to the security of the tech.

The code was available for inspection from the start. Coldcard's March 2021 announcement even promoted reproducible builds that let developers compare the published source with the firmware binary. The vulnerable seed path remained in released products for more than five years.

With the search space cut down, an attacker could generate candidate seeds offline, derive their Bitcoin addresses, and compare them with the public blockchain. A match reveals a spendable key. No contact with the victim is required. Block describes a wallet address or public key as a validation oracle for candidate seeds.

Coinkite says it must assume somebody used artificial intelligence to inspect old versions of its public firmware and find the flaw. The company also says it had recently asked a leading AI model to review the code, and that model missed the bug.

Our third lesson is that all "leading" AI models are not the same.

After the bug became public, an Aug. 2 Reddit post supplied a vivid but limited demonstration. The poster said Claude Code found the broken path after receiving only a generic instruction to check for vulnerabilities and thinking for eight minutes. The screenshot shows the model distinguishing the correct hardware TRNG path from the broken ngu.random software PRNG path. It does not show the full prompt, model version, checked-out firmware revision, internet permissions, or complete session transcript. The post supports rapid AI-assisted reproduction, not a claim that Claude Code discovered the original exploit or that the thief used it.

Bitcoin Optech separately reports that several developers reproduced the attack with help from frontier AI models. AI involvement is plausible. The attacker's identity and tools remain unknown.

'I did everything right'

The ledger gives us totals. It does not show the years people spent building those balances.

Canadian entrepreneur Jonathan Goodman says 18.25245043 Bitcoin disappeared from his wallets between 9:36 and 9:43 p.m. on July 29. His Coldcard sat in a bank safe-deposit box, he said, while his backup keys were kept in a different safe. The device had never been connected to the internet. When he opened a watch-only wallet from his cottage, he saw the withdrawals. Goodman put the loss at more than $1.6 million Canadian and said he was filing reports with police and the Ontario Securities Commission.

"Perhaps the hardest part about this is that I did everything right," he wrote.

Bitcoin to 1 Mil (@1MillionBTC2025) said 1.3 Bitcoin accumulated over seven years was gone; the post included no transaction record. Bitcoin commentator Oliver Velez said he followed "every accepted rule of Bitcoin self-custody" and still lost a material amount. These are public self-reports, not independently verified claims. They arrived amid the large pattern of theft Galaxy had already found on-chain.

One particularly grim account began on Reddit and then spread across X. A 39-year-old poster said he had spent eight years accumulating two Bitcoin as protection against inflation and hoped the money would provide a cushion before age 50. The Reddit post did not include a transaction ID, and commenters questioned its authenticity, so it should be treated as unverified. The story spread because it resembled losses that were already visible on-chain.

RELATED: Are you inhaling microplastics?
solar22/Getty Images

The rush to escape creates its own hazards. X user lunymoon13 said he moved funds toward a temporary hot wallet after hearing the warning, sent a successful test, and then discovered the remaining stack had been drained. The cause of that loss has not been established. Even with the clock running, verify the destination and backup before moving the rest.

The backlash includes people who did not lose funds. Chris Masterjohn said he had bought two Coldcards but never used them. Responding to a developer's review of the commit history, he wrote, "Will never touch the company again." The same post blamed competitive pettiness for the code change. The developer analysis documents the broken call path; it does not establish that motive.

Who is affected?

The important question is where the seed was created, not which device holds it today. Moving a weak Coldcard-generated seed into a Ledger, Trezor, software wallet, or newer Coldcard does not strengthen it. Block specifically warns that an exported seed remains vulnerable after import into another wallet.

Coinkite's latest advisory identifies Mk2 or Mk3 firmware 4.0.1 through 4.1.9 as affected. Block's engineering team includes version 4.0.0, which Coinkite publicly released on March 17, 2021, in the vulnerable range. That discrepancy should be resolved in the promised formal review. Until then, the safe course is to treat any Mk2 or Mk3 seed generated on a 4.x release before fixed version 4.2.0 as potentially affected. Also affected are Mk4 or Mk5 seeds generated before standard version 5.6.0 or Edge version 6.6.0X, and Q seeds generated before standard version 1.5.0Q or Edge version 6.6.0QX. Coinkite initially said the newer models were unaffected, then expanded the warning after further investigation. Its current advisory supersedes that early assessment.

There are two important qualifications. Coinkite says a seed created with at least 50 fair, independent, private dice rolls has at least 128 bits of outside entropy and is not endangered by this particular bug alone. A strong, unique BIP-39 passphrase also puts another barrier between an attacker and the funds. A short quotation, reused password, patterned phrase, or one clever dictionary word does not count. Even users with strong passphrases are being told to replace affected seeds as soon as practical.

The device PIN is not that passphrase. It protects access to the physical Coldcard. It does nothing against somebody who has reconstructed the seed elsewhere. Coinkite's advisory makes the same distinction.

What affected Coldcard owners should do now

The blunt answer: Move the Bitcoin out of the wallet controlled by the affected Coldcard seed. Installing new firmware does not repair that seed. A strong passphrase may buy time, but it is not a repair either. Coinkite says the money must move to an entirely new seed.

Use Coinkite's official advisory, not a link in an email, direct message, or reply. The emergency creates perfect working conditions for phishing and fake "recovery" services.

The cleanest exit is a new seed generated on a different hardware wallet with current firmware. Do not import the old Coldcard words. That carries the vulnerability into the new device. Even Coldcard's Sunday statement pointed customers toward Bitkey, Ledger, Trezor, Jade, and BitBox.

Write down and verify the new backup. Check the wallet fingerprint and receive address on the new hardware screen. Send a small test transaction. Once it arrives at the correct wallet, move the rest. Keep the old backup until the transfer is confirmed, but never enter it into a website or give it to anyone offering help.

Do not throw away the affected Coldcard. The company says the device could become important if stolen funds are recovered. That is not an announcement that recovery has happened. Keep the device secure.

Coinbase as an emergency bridge

Public threads are full of shaken owners asking whether they should park their Bitcoin on Coinbase or another exchange. If the choice is between leaving money under a seed that thieves are actively searching and using an established exchange while a replacement wallet arrives, temporary exchange custody may be the less dangerous option.

It is still a trade. In a hosted Coinbase.com account, Coinbase controls the private keys. Coinbase Wallet is a different, self-custody product, so make sure you know which one you are using. Coinbase's agreement says withdrawals can be subject to outages, downtime, and company policies, and Bitcoin held there does not have FDIC or SIPC protection.

Anyone choosing Coinbase should secure the account before sending money. Coinbase calls two physical security keys its highest-security two-factor setup. Get the Bitcoin deposit address from the official app or a manually typed Coinbase URL, verify the network and address, send a test, and then move the balance. Do not follow deposit instructions from an email, text message, phone call, or direct message.

What owners of other hardware wallets should do

Do not move Bitcoin merely because another company's hardware wallet failed. Ask where your seed came from.

If Ledger, Trezor, Jade, BitBox, or another wallet generated the seed and that seed never came from an affected Coldcard, this particular bug does not apply to it. Check for notices from your own manufacturer, use only its official firmware tools, and keep the seed backup offline. Do not type the words into a computer or website to "check" them.

If an affected Coldcard created the seed and you later imported it into another device, move the Bitcoin. Changing hardware does not add randomness to an old seed.

RELATED: Thousands of lawyers caught using AI — and it's only getting worse
DAVID MAIALETTI/POOL/AFP/Getty Images

Multi-signature owners have one more question: Could the affected Coldcard keys meet the spending threshold without the other devices? Galaxy says wallets where the answer was no were protected from this attack, but the weak Coldcard key should still be rotated. Do not build a complicated multi-signature wallet in the middle of a panic. For large balances, though, a planned setup using keys from different manufacturers prevents one broken generator from holding the entire stack hostage.

If the Bitcoin is already gone, preserve the wallet addresses, transaction IDs, amounts, dates, screenshots, device and firmware details, and records showing how you acquired the coins. Report the theft to local law enforcement and to the FBI's Internet Crime Complaint Center. The FBI says transaction hashes, receiving addresses, amounts, and timestamps are the most useful details, and it warns that services promising to recover stolen cryptocurrency for an up-front fee may be running a second scam. Recovery is uncertain, but a prompt, detailed report gives investigators something to trace.

An air gap is not magic

The published analyses describe a failure in Coldcard's secret generation, not a break in Bitcoin's ledger or signature algorithm. The product failed at the most basic point in the custody chain: making a secret that nobody else can guess.

"Don't trust, verify" sounds good on a T-shirt. In practice, verifying this bug required following a function call across libraries, build settings, and linker behavior. Almost no ordinary customer can do that, which is why customers bought the little plastic signing device in the first place.

Final lesson? Public code does not inspect itself. An air gap protected the secrets from the internet. It could not save secrets that were too predictable at birth.

Coinkite has released fixes and migration instructions. In its Sunday statement, the company said it halted shipments, destroyed its remaining Coldcard inventory manufactured with vulnerable firmware, and had begun working directly with customers. Its lawyers may coordinate with law enforcement, and a technical postmortem is coming. The statement did not say that stolen funds had been recovered or describe a reimbursement plan.

The company still owes customers a full account of how this passed review, how many people were harmed, and what it plans to do for those who trusted its product with the savings of a lifetime.

Check where your seed came from. If affected Coldcard firmware created it, move the Bitcoin to a new seed created somewhere else. If another wallet created it, do not turn one company's failure into a rushed mistake.
Ain’t no scam: Bitcoin fixes the looming AI oversight fiasco


Welcome, America, to the Thunderdome of AI oversight.

President Trump has dropped his executive order, putting the onus on the federal government’s most secretive agencies to determine whether the products of private corporations are safe for public consumption. The National Security Agency is at the heart of the plan, with the intelligence community setting classified benchmarks, vetting, and gatekeeping new AI models within a 30-day window. Private-sector institutions and stakeholders, including AI companies themselves, must sit and wait, blind, for decisions to be handed down.

It can’t be said that this decision is strongly supported by conservatives, the “based community,” or even MAGA people more narrowly. The personal, private bid by former White House AI and crypto chief David Sacks to stop the Trump train on AI resulted only in a delay and a narrowing of the oversight window. On X, Sacks had to resort to emphasizing the things the order doesn’t do that he and the accelerationist wing of the right oppose.

Is there anything we can tell these machines to do that doesn’t tend to demote us as human beings?

That means even Trump’s inner circle will keep on duking it out among themselves.

Congress is wrestling with OpenAI’s approach, which relies on (deep breath) the National Institute of Standards and Technology’s Center for AI Standards and Innovation. In short, the idea is that oversight and testing should be carried out under the aegis of established and respected bodies that bridge government and industry through public-private partnerships. This approach allows AI companies themselves, plus other stakeholders and experts outside the intelligence community, to have a participatory role in testing and oversight of new models.

Yet Congress is sharply divided, and the upcoming midterm elections could alter the balance of power. Competing bills are already in the mix on Capitol Hill, with the leading piece of draft legislation, the bipartisan American Leadership in AI Act, hinging on outcomes in the rat’s nest of congressional politics — ranging from Louisiana Republican House Speaker Mike Johnson’s unwillingness to reauthorize the House AI Task Force to rank-and-file Democrats’ unfavorable disposition toward the draft bill.

Can both houses of Congress come to an agreement on AI model development as well as testing? One that Trump won’t veto? Probably not, but with anti-AI sentiment running hotter and hotter across the populist (and opportunist) wings of both parties, principled members and ambitious members alike are all but guaranteed to shoot their shot before November.

That means Americans won’t be looking to their elected representatives for clarity on AI.

RELATED: Why dystopian AI doomers need to get religion

The doomer delusion ArtMarie via iStock/Getty Images

And Pope Leo XIV, of course, has his landmark encyclical out there, insisting — along with many other Christians — that no law or regulation or basket of rules is enough to enable anyone, even the United States government, to get the kind of grip on AI that will ensure our sacred human being is no worse for wear.

But there’s no indication that America’s Christians, much less the world’s, are poised to throw down their doctrinal and ecclesiological differences and line up shoulder to shoulder with the pope’s presentation of things — or with the pope as a singular planetary spiritual authority on all matters AI and tech.

That means neither our leading political power players nor our leading spiritual authority figures will give Americans the kind of overall guidance they increasingly seem to crave.

Perhaps, however, we should all recognize that’s actually for the best, because the essence of the problem concerning AI is its risk, not of wiping out the human race, but of emptying the human race of all power and authority except for a tiny cyborg elite, one hell-bent on remaking all God’s creation, every single one of us included, in their monomaniacal image.

Paradoxically, responding to this risk by maximizing tech hate and consolidating all tech hatred into as tiny and powerful an elite as possible dramatically increases the risk of both wiping out the human race and deepening the would-be cyborg elite’s conviction that if they don’t achieve a radical and irreversible break with all to ever come before them, then they’ll meet a fate worse than death.

Back on our feet and back in charge

Given the dangers of over-centralized AI oversight on one hand and a regulatory war of all against all on the other, now is a good time to ask whether Bitcoin can offer ordinary people a more balanced, distributed, and practical path forward.

For all the noise and blather in the fractured crypto world, the case for Bitcoin in the AI age is simple: If we are not going to dismantle these machines — and if people will keep building more powerful ones — can we direct them toward anything that preserves rather than diminishes our human dignity?

The answer is obviously yes, but the combination of massive fear over techno-dystopia and massive resistance to “organized religion” leads many to paint themselves into a paralyzing psychological corner where no answer seems plausible or effective.

That’s a shame. Bitcoin is sitting right there, an advanced, mature technology that allows people with a minimum of new information or expertise to start creating and growing markets and institutions that benefit and protect themselves and their friends, families, and parishes, without having to rely on superintelligent machines or government financial systems.

Given that superintelligent machines and government financial systems have a clear logical and practical tendency to converge, becoming one system very well suited to enforcing a single, uniform, and servile existence worldwide, it would seem fairly urgent for people to consider the benefits of taking a few steps outside their zone of comfort or self-disempowerment and start to use Bitcoin at least a little with those they care about most.

That’s why I continue to offer my book on our tech reckoning, "Human Forever," only in Bitcoin. Piling up the digital currency and waiting for Nirvana just isn’t going to cut it, whether we face a societal collapse scenario, an age of mandatory pleasure and plenty, or a mutant future that somehow combines both into one waking phantasmagoria. Using Bitcoin needs to happen well beyond the realm of books, obviously. But being a writer, well — I’m putting my money where my mouth is.

Is it enough to solve all our problems, with our machines and with one another? Obviously, again, no. But it just might fix our attention on how we can preserve human ways of life that open the way not just to solutions, but to salvation.

Caroline Ellison, Sam Bankman-Fried's partner in FTX crime, sprung early from prison


Caroline Ellison was sentenced to two years in prison last September after facing a possible 110 years.

Ellison was the CEO of Alameda Research, a crypto investment firm that was co-founded by her ex-boyfriend Sam Bankman-Fried, the centerpiece of the FTX scandal that rocked the nation.

'We do not discuss the conditions of confinement for any individual.'

Bankman-Fried was found to have been improperly funneling money to the hedge fund, and in Dec. 2022, Ellison pleaded guilty to related charges, including conspiracy to commit commodities fraud and conspiracy to commit securities fraud.

Now as reported by Business Insider, Ellison has been moved out of federal prison after serving just 11 months at the Danbury Federal Correctional Institute, a low-security prison in Danbury, Connecticut.

Ellison was reportedly transferred out of the facility on October 16 and into community confinement, a Federal Bureau of Prisons spokesperson told BI.

Spokesperson Randilee Giamusso said that Ellison remains in federal custody by way of either home confinement or through a halfway house.

"For privacy, safety, and security reasons, we do not discuss the conditions of confinement for any individual, including reasons for transfers or release plans, nor do we specify an individual's specific location while in community confinement," Giamusso told the outlet.

RELATED: Ellison says FTX used $100M of customer deposits to bribe Chinese officials, set up accounts in names of Thai prostitutes

Photographer: Yuki Iwamura/Bloomberg via Getty Images

Online records purportedly showed Ellison was set to be released in February, nine months earlier than the duration of her sentence.

Despite facing 110 years in prison for seven charges, a New York judge said he gave the 31-year-old a shorter sentence due to her "very, very substantial" cooperation with the federal case against Bankman-Fried and other executives.

"She cooperated, and he denied the whole thing," Judge Lewis Kaplan said at the time. "I've seen a lot of cooperators in 30 years here. I've never seen one quite like Ms. Ellison."

FTX allegedly took $10 billion from customer deposits, while at the same time granting Alameda Research a $65 billion credit line. This eventually resulted in an $8 billion debt taken out of customer deposits.

Ellison testified with other shocking allegations; "CBS Mornings" reported at the time that Alameda allegedly used $100 million of FTX customer deposits to bribe Chinese officials.

The bribes were an alleged attempt to gain access to crypto accounts that were frozen by the Chinese, worth upwards of $1 billion. In their attempts, FTX allegedly tried to regain the money by setting up accounts in the names of Thai prostitutes.

RELATED: Caroline Ellison sentenced to 2 years in prison over massive FTX crypto-scandal

Photographer: Yuki Iwamura/Bloomberg via Getty Images

Ellison also claimed that in order to recoup some money, Bankman-Fried considered selling shares in FTX to investors like Saudi Crown Prince Mohammed bin Salman.

Ellison reportedly told jurors that Alameda Research would lend money to Bankman-Fried and other FTX executives so they could make political donations. Bankman-Fried donated a reported $70 million to Democrats ahead of the 2022 midterms, making him the second-highest donor behind George Soros.

FTX's deep pockets allowed for big-name sponsorship deals with people like NFL legend Tom Brady and iconic television writer Larry David and even allowed for naming rights to FTX Arena in Miami.

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

'Assets of fear': BlackRock CEO Larry Fink FLIPS on crypto


BlackRock's CEO has seemingly changed his mind about the future of Bitcoin and cryptocurrency.

Investor Larry Fink famously criticized Bitcoin in 2017 when he called it an "index of money laundering" that simply showed how much demand there was in the world to launder funds.

'I do see more and more of a future of having more and more financial assets being digitized.'

Now, during a sit-down with the CEO of hedge fund Citadel, Ken Griffin, Fink said he sees cryptocurrency wallets being used to make stock moves en masse in the near future.

Fink revealed during the conference that if he could "tokenize" all ETFs and provide them in a digital wallet, users would be able to seamlessly make trades.

"You could seamlessly, without fees, ... buy bond or stocks, and I believe that is going to be the future," Fink said. "I do believe more transactions [are] going to be done digitally with authentication of ownership."

He added, "I do see more and more of a future of having more and more financial assets being digitized, sitting in a singularity of a blockchain and going from cash to stocks to bonds, back and forth, doing that seamlessly, and I do believe that is going to happen sooner, not later."

During the same event, Fink described Bitcoin as an investment made out of fear, but not in the way one might think.

RELATED: Bitcoin billionaire will serve time after British police broke down her door and arrested her in bed

Fink described Bitcoin and gold along similar lines, calling them "assets of fear" that investors scoop up when they are "frightened of the debasement of your currency."

"You own it if you have financial insecurities, or you own it if you have physical insecurities and worries. So, that's one of the foundational issues of my journey in understanding crypto more."

Fink has confused audiences over the years with his remarks on digital currency, both in his evolving stance on the asset and, of course, his — along with other major institutions — apparent inability to recognize that it is in fact being used as he prophesies it will be used in the future.

Fink's pontifications about the future of crypto, fiat, ETFs, and stocks/bonds being traded seamlessly on apps are already a reality. Countless companies allow direct deposit of paychecks to digital wallets, the same as any bank, while also providing the ability to trade stocks and cryptocurrency in-house.

RELATED: Almost HALF of Gen Z wants AI to run the government

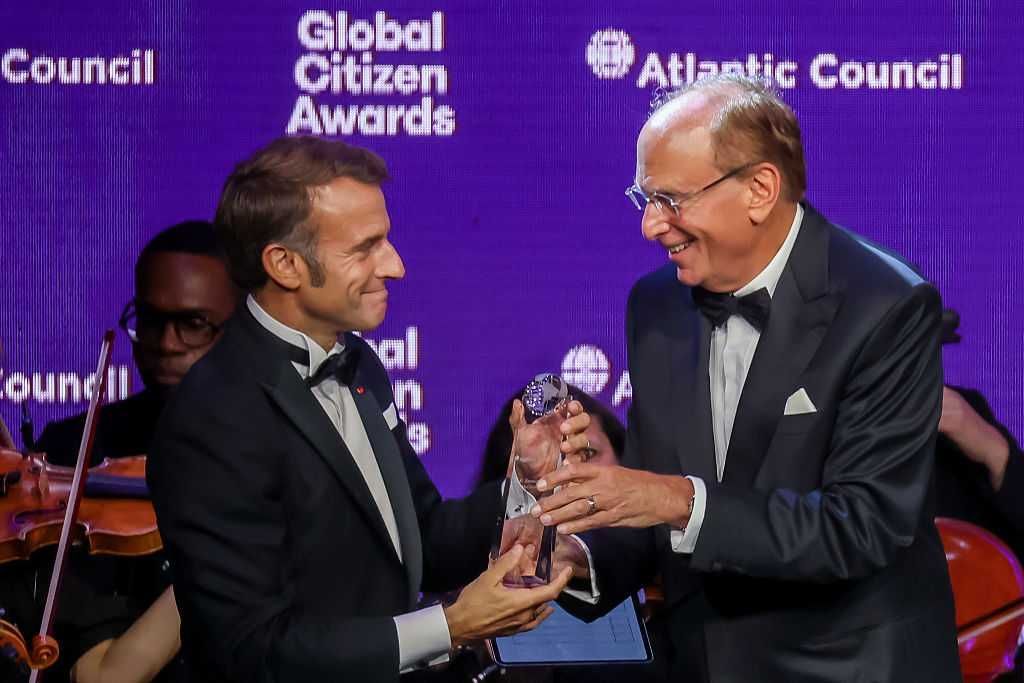
French President Emmanuel Macron, left, and Larry Fink. Photographer: Michael Nagle/Bloomberg via Getty Images
It is unclear if BlackRock's plan was to slow-walk its investors into cryptocurrency cautiously, but its CEO has certainly made gradual strides in the direction of acceptance, hallmarked by his most recent comments.

In 2024, Fink seemed to turn a new leaf when he admitted he was wrong about Bitcoin and told CNBC he thought it had become a legitimate asset.

"It is a legitimate financial instrument that allows you to maybe have uncorrelated type of returns. I believe it is an instrument that you invest in when you're more frightened, though. It is an instrument when you believe countries are debasing their currency by excess deficits, and some countries are," Fink explained.

Moreover, the CEO even referred to Bitcoin as "digital gold," which is now in step with his recent description of the asset.

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

Bitcoin billionaire will serve time after British police broke down her door and arrested her in bed


"You're under arrest. You're going to be arrested for money laundering."

These were some of the last words Zhimin Qian heard as a free woman before she was arrested for allegedly laundering billions of dollars in cryptocurrency.

'... compelling evidence of the criminal origins of the crypto assets ...'

Qian, 47, was dubbed the "Goddess of Wealth" due to a lavish lifestyle acquired through money laundering with her accomplice, Malaysian national Hok Seng Ling, also 47. Qian is Chinese.

Police investigated Qian and conducted a search of her Hampstead, London, mansion in October 2018 after she attempted to buy another house worth over $16 million. According to the Telegraph, police found laptops, cash, and even a "treasure map" to a safe-deposit box in London. The drawn map simply labeled two streets and noted a "Metropolitan Safe Deposit."

Another laptop was recovered from the deposit box in 2022, which reportedly stored billions of British pounds' worth of crypto.

Qian was not shy about her spending while on the run for six years across Europe, allegedly staying in luxury hotels and purchasing high-end properties.

By the time of her arrest in April 2024, she was reportedly worth over $7 billion in Bitcoin assets. She had previously purchased a property in North London worth millions, along with other properties in Dubai.

RELATED: Trump tech czar slams OpenAI scheme for federal 'backstop' on spending — forcing Sam Altman to backtrack

The two criminals allegedly defrauded more than 128,000 people in China between 2014 and 2017 before Qian fled the country.

Qian traveled with false documents and went to the United Kingdom, where she laundered her money through her property ventures, Metro reported, citing police.

Both appeared in Southwark Crown Court in London, where Qian was sentenced to 11 years and eight months in prison, while Ling received a sentence of four years and 11 months.

Qian and Ling allegedly had an accomplice named Jian Wen, who was previously jailed for six years and eight months after being arrested with Bitcoin wallets also worth billions.

The illegally obtained Bitcoin reportedly represents the largest ever cryptocurrency seizure of Bitcoin, and it all came from just three people.

RELATED: Bitcoin and the return of honest money

Ling pleaded guilty to entering a money laundering arrangement, while Qian admitted to money laundering and "knowing or suspecting [Ling's] actions would facilitate the acquisition or control of criminal property by another."

London Metropolitan Police said they had been working for years to investigate the crimes and said that in addition to being perhaps the largest cryptocurrency case in the world, it was also "one of the largest money laundering cases in U.K. history."

"Through a meticulous investigation and unprecedented cooperation with Chinese law enforcement, we were able to obtain compelling evidence of the criminal origins of the crypto assets the pair attempted to launder in the U.K.," said Will Lyne, head of Economic and Cybercrime Command for the London police.

He added, "My thoughts are with the thousands of victims defrauded in this scheme, and I hope this outcome acknowledges the harm these defendants inflicted and reinforces the Met's unwavering commitment to justice."

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

Bitcoin and the return of honest money


Bitcoin. Cryptocurrency. Blockchain. A decade ago, most Americans hadn’t heard those words. Even now, many don’t fully grasp what they mean. Some still dismiss Bitcoin as an internet fad — yet with one coin worth roughly $119,000, the joke is wearing thin.

The real story isn’t the price. It’s what Bitcoin represents: freedom, trust, and control over your own money. Those are conservative principles — and conservatives should embrace them.

Honest money for a dishonest age

In Denton County, Texans understand independence. We work hard, save what we can, and expect our money to keep its value. But Washington keeps printing dollars to solve political problems, and every new round of “stimulus” steals a little more of what Americans earn. That’s a big reason groceries, gas, and housing cost so much more today.

At its heart, Bitcoin isn’t about tech or speculation. It’s about trust — and keeping financial power in the hands of citizens instead of bureaucrats and corporations.

Bitcoin doesn’t play that game. Its supply is capped at 21 million coins forever. No bureaucrat or central banker can “stimulate” the economy by diluting your savings. It’s steady, transparent, and immune to the inflationary habits of modern government.

That’s not radical — it’s a return to honest value. Early Texans traded cattle, crops, and tools, and a handshake sealed the deal. Bitcoin is a digital version of that same trust: value backed by proof of work, not political decree.

Freedom in your own hands

Bitcoin is, at its core, a conservative idea. It rewards effort, limits government control, and protects personal liberty. You can own every rifle and round of ammunition in the world, but if the government freezes your bank account, you’re stuck. With Bitcoin, you control your money. Nobody can seize it.

The network itself is decentralized — millions of computers around the globe share the ledger. No single government, company, or regulator can shut it down. If one node fails, the others keep the system alive. It’s built to endure.

Lessons for a digital age

That model should guide how we build other technologies. Take artificial intelligence. Meta just poured $14 billion into one massive data center — a single point of failure. One cyberattack or natural disaster could wipe it out. America should follow Bitcoin’s example: distribute computing power, build smaller centers across the country, and bring skilled jobs to local communities like ours.

RELATED: ‘Lipstick on a pig’: How printing cash is destroying America — and crypto could be next

dem10 via iStock/Getty Images

Bitcoin also saves money. Send $1,000 through a credit card processor and you’ll lose $40 in fees. Send it through Bitcoin and it costs about four cents. That difference matters to small businesses, churches, and local campaigns. Political donations in Bitcoin should be legal nationwide — transparent, secure, and independent of the big banks that profit from the current system.

A return to honest value

At its heart, Bitcoin isn’t about tech or speculation. It’s about trust — and keeping financial power in the hands of citizens instead of bureaucrats and corporations.

Here in Denton County, we understand that kind of freedom. It’s the same spirit that settled Texas: work hard, hold what’s yours, and keep government out of your pockets.

Bitcoin isn’t the future of money. It’s the return of honest money — and conservatives should lead the charge to make it America’s next great success story.

I went to El Salvador to see if the country really gave up on Bitcoin


In late August, I had the pleasure of visiting El Salvador for the first time. I didn’t know what to expect. The bar had been set high by both conservative and liberal media, who either praised or decried President Nayib Bukele’s vigorous war on crime. Within a few hours of arrival, I saw the media reports were true. El Salvador, once a violent, gang-ridden nightmare, was now a place of peace.

Much has been written about Bukele’s crackdown — understandably so, given the success of his efforts. El Salvador’s president deserves unending praise for transforming his country. Yet, this success has overshadowed his other policies. President Bukele’s Bitcoin adoption program, for instance, is of remarkable significance.

In September 2021, El Salvador shocked the world by becoming the first country to accept Bitcoin as legal tender. Businesses were immediately required to accept the cryptocurrency. Western Bitcoin enthusiasts were overjoyed. Many Salvadorans, most of whom had previously existed in a cash economy, were skeptical.

'Paying tax liabilities denominated in Bitcoin was just, I guess, a hard no.'

After a few years, there were signs that the initiative had failed to meet expectations. In an August 2024 interview with Time, President Bukele conceded as much:

Bitcoin hasn't had the widespread adoption we hoped for. Many Salvadorans use it; the majority of large businesses in the country have it. You can go to a McDonald's, a supermarket, or a hotel and pay with Bitcoin. It hasn’t had the adoption we expected. The positive aspect is that it is voluntary; we have never forced anyone to adopt it. We offered it as an option, and those who chose to use it have benefited from the rise in Bitcoin.

But it wasn’t until the International Monetary Fund got involved that President Bukele made the difficult decision to scale back El Salvador’s Bitcoin program. As a condition for $1.4 billion in financial assistance, the IMF required El Salvador to revoke Bitcoin’s status as legal tender. Bukele accepted the IMF’s terms. In February 2025, the Salvadoran government passed an amendment to the Bitcoin law, which rendered use of the cryptocurrency voluntary and limited to the private sector.

Just like that, El Salvador’s Bitcoin experiment was done. Or was it?

Seeing for myself

When I traveled to El Salvador, I had bought into the media narrative regarding its Bitcoin adoption program — that, however interesting a program it might have been, it failed. But curiously enough, no one I spoke to down there shared that perspective.

“I mean, it's, like, pretty f**king amazing,” Jake Hamilton, an American computer programmer who splits his time between Austin and San Salvador, told me. “I can pay with lightning for oysters at a beach shack in Surf City.”

Jake’s enthusiasm for El Salvador is significant. He isn’t some casual Bitcoin fan who merely enjoys the novelty of paying for oysters in cryptocurrency. In many ways, Jake’s life — professionally, socially, and economically — revolves around Bitcoin. So when he praises El Salvador’s Bitcoin program, it means something.

His Bitcoin journey began in 2015. After completing his undergraduate studies, Jake busied himself researching philosophy graduate programs. During that period, he took a seminar titled Bitcoin and Philosophy. The instructor: Nick Land, the arcane techno-philosopher known for his accelerationist theories.

Jake didn’t know what to expect, but the seminar proved epiphanous. “He’s five minutes, 10 minutes of the first session, and I realize, like, holy s**t, the place to be doing philosophy — to be in actual philosophy of the world right now — is in Bitcoin: writing code and working in blockchain,” he explained to me.

RELATED: Right-wing investor to challenge traditional banking with national crypto bank

Photo by Bloomberg / Contributor via Getty Images
After the seminar, Jake decided to move to New York, where he attended a coding bootcamp and dedicated his time to becoming a programmer. Around 2019, he discovered Urbit, Curtis Yarvin’s niche operating system, which connected him to numerous right-of-center programmers and crypto enthusiasts. Along with a few friends from that crowd, Jake ventured to Central America and eventually landed in El Salvador, arriving at the beginning of President Bukele’s special operation.

It was a good time to be in El Salvador. Jake witnessed the restoration of order play out in real time. Yet, it was Bitcoin, not public safety, that drew him there. Jake knew a few Western lawyers in the country who practiced cryptocurrency law. They told him that something unique was taking shape in El Salvador — and that he wouldn’t want to miss it.

Although President Bukele didn’t sign the Bitcoin law until June 8, 2021, El Salvador had already developed a nascent crypto scene. Jake told me that an anonymous donor contributed $100,000 (in Bitcoin, naturally) to the beach town of El Zonte in 2019 to establish a circular crypto economy. This began attracting Bitcoin-inclined expats and tourists. Bukele’s national transformation only amplified that appeal.

Needless to say, Jake fell in love with El Salvador. When he isn’t in Austin, Texas, working on blockchain technology, he’s in El Salvador, working on blockchain technology — but also surfing, driving through the mountains, and brushing shoulders with El Salvador’s political elite. He’s become a central figure in the Salvadoran expat scene. He holds the lease on the Palestra mansion, a massive house overlooking the hills of San Salvador that often hosts parties and provides lodging for aligned travelers.

The view from the top

I visited the mansion a few times during my trip. The first time was at night following the Palestra Society’s annual conference. As I stood on the back patio, surrounded by a coterie of interesting people, I looked down at the lights of San Salvador and was struck by the peculiarity of it all. How did a small Latin American country with a GDP of $35 billion become a hub for heterodox right-wing Westerners? There are certainly several factors. But Bitcoin is a big one.

Despite Jake’s appreciation for El Salvador’s Bitcoin adoption program, he conceded that it faced challenges. “They did have to negotiate with the IMF, obviously, and the paying tax liabilities denominated in Bitcoin was just, I guess, a hard no,” he lamented. Moreover, given the low level of education and tech literacy in El Salvador — a country where the average monthly salary is roughly $400 — teaching people the finer points of self-custody proved difficult.

While El Salvador reversed its decision to accept Bitcoin as legal tender, no other country boasts as much Bitcoin integration. Others have tried, but they don’t come close. “There’s a bit of Costa Rica that’s informally called Bitcoin Jungle, where there’s like a 20-mile radius where most of the businesses take Bitcoin,” Jake said. “But there’s nothing comparable to El Salvador in the world.”

So was El Salvador’s Bitcoin adoption program a failure, as mainstream sources claim? Yes and no. On the one hand, its decision to no longer accept Bitcoin as legal tender is proof that the program didn’t entirely succeed. On the other, El Salvador is now the most Bitcoin-integrated country in the world — no small accomplishment.

Furthermore, since agreeing to the IMF’s terms, El Salvador has continued to purchase Bitcoin; hosted PLANB 2025, the largest cryptocurrency conference in Central America; passed a law allowing investment banks to hold Bitcoin; and promoted Bitcoin mining using geothermal energy from volcanoes.

It appears that Bitcoin is, in fact, alive and well in El Salvador. Abolishing its status as legal tender didn’t kill it — it merely altered the parameters. So while you cannot pay your Salvadoran taxes in Bitcoin, you can still do more with crypto there than anywhere else in the world.

Right-wing investor to challenge traditional banking with national crypto bank


A challenger to traditional banking has finally emerged, and it is coming from the right wing.

After billionaire Palmer Luckey was reported to be starting a cryptocurrency venture, it was unclear how big the scope would be and if it would work only in digital currencies.

Now that public filings have emerged, the new project was revealed to have major conservative backing while literally giving traditional banks a run for their money.

'The bank will be a national bank ... providing traditional banking products.'

Blaze News reported last week that Luckey had teamed up with Joe Lonsdale to start the new company; Lonsdale co-founded Palantir Technologies with Luckey and has his own software companies, as well. At the same time, Lonsdale's venture firm 8VC led a $225 million fundraising round for the new company to meet federal regulatory requirements.

The tech entrepreneurs were first thought to be starting a bank that would work primarily on maximizing returns for tech startups, but recent filings revealed much more is in store. According to the Financial Times, the new company has applied for a national bank charter, which would it give license to operate as a typical banking institution.

The Times also revealed a new right-wing mega-donor has joined the mix.

RELATED: Palmer Luckey-led crypto bank promises startups a capital hoard safe from scheming feds

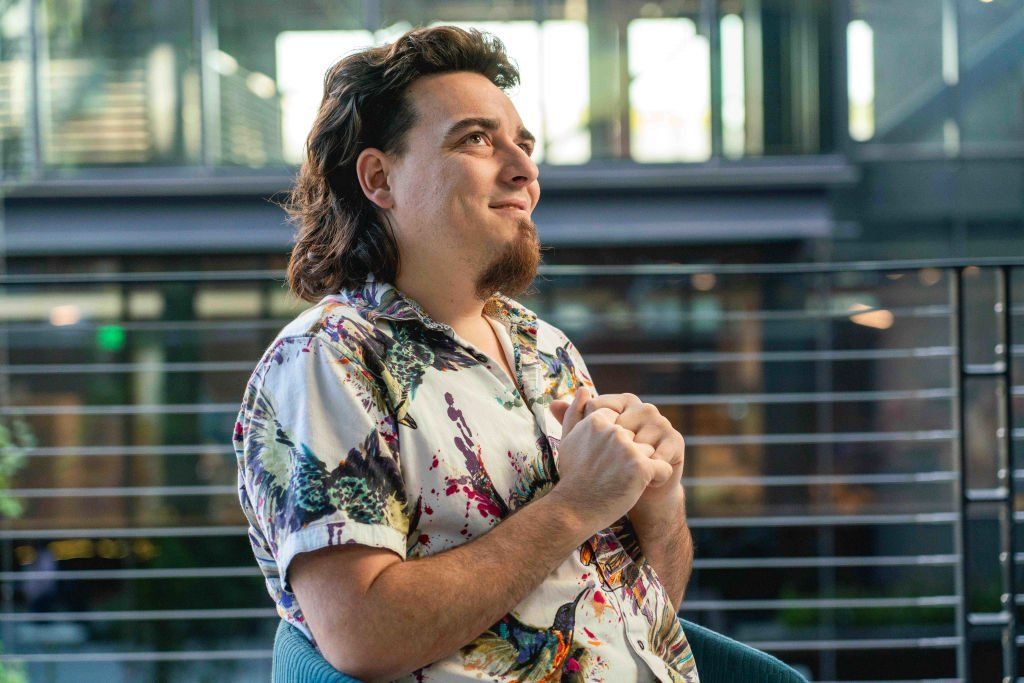
Palmer Luckey, founder of Anduril Industries, during an interview on 'The Circuit with Emily Chang' at Anduril's headquarters in Costa Mesa, California, US, on Thursday, Dec. 14, 2023. Anduril recently beat several legacy defense players in a contest for a major contract to develop an unmanned fighter jet for the US Air Force and is now valued at $8.5 billion. Photographer: Kyle Grillot/Bloomberg via Getty Images
None other than Peter Thiel and his venture capital fund, the Founders Fund, will also be backing the startup, according to two of the Times' sources.

Thiel is, of course, known for giving millions to Republican campaigns over the years, including over a million dollars to President Donald Trump for his 2016 campaign.

This new undertaking, dubbed Erebor, is yet another one of Luckey's companies named after themes found in J.R.R. Tolkien books. This one refers to the mountain in "The Hobbit," where the dragon Smaug hoards his gold. His other companies, Anduril and Palantir, are references to a character's sword and a magical seeing stone, respectively.

Filings revealed, "The bank will be a national bank ... providing traditional banking products, as well as virtual currency-related products and services, for businesses and individuals."

Adding to previous speculation, the target market was listed as businesses that are part of the American "innovation economy," including tech companies focused on virtual currencies, artificial intelligence, or defense manufacturing.

RELATED: The One Big Beautiful Bill Act hides a big, ugly AI betrayal

A Bitcoin Teller Machine in San Francisco, California, US, on Monday, Dec. 30, 2024. The Bitcoin rally sparked by US President-elect Donald Trump's election victory in early November is stalling as 2024 draws to a close. Photographer: David Paul Morris/Bloomberg via Getty Images
Erebor will work with stablecoins, cryptocurrency tied to relatively stable assets like the U.S. dollar or gold. This is done to limit the volatility of a coin without sacrificing its benefits, creating investment opportunities far in excess of simply purchasing and holding, say, Bitcoin.

For example, President Trump works with the stablecoin USD1, which is attached to the U.S. dollar.

"Longtime crypto people know it's a fine line between being targeted by government and being co-opted by government," explained Blaze Media's James Poulos. "But it's hard to strike the right balance without risking the worst of both worlds — a crypto economy that regulators tolerate but can destroy or manipulate with the wave of a hand."

Poulos added that the most stable compromise naturally involves figures that Washington relies on in other high-tech industries, "however much freedom-loving 'maxis' wish that weren't the case."

"Regardless, it doesn't matter how perfect a balance the kingpins of crypto and banking might strike if Bitcoin (to take the biggest example) falls short of its potential as a peer-to-peer currency and becomes just another place for established wealth to accrue value," Poulos concluded.

Erebor's filing said it plans on working with non-U.S. companies that are "seeking access to the U.S. banking system," according to the filing, and said it would "differentiate itself" by working with customers who are not well served by "traditional or disruptive financial institutions."

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

Conservatives can lead the charge on clean crypto rules


Many assume conservative principles belong to the past. They don’t. The debate over cryptocurrency regulation — including the House GOP’s Clarity Act — offers a chance to apply those principles to a 21st-century frontier.

Cryptocurrency and decentralized finance reflect core American values: free speech, free markets, and innovation from the ground up. Across the country, developers are building protocols that move money in microseconds, create new investment tools, and expand access to capital like never before.

With a Republican-led Congress considering landmark cryptocurrency legislation, we have a historic opportunity to apply time-tested conservative values to the cutting edge of financial innovation.

Blockchain technology provides a means to secure property rights in the digital era. The most transformative products likely haven’t even launched yet.

The potential benefits are massive. In 2024 alone, decentralized finance grew to more than $114 billion. Even more capital — billions of dollars — stands ready to enter the space through pension funds and institutional investors.

But that money won’t move without guardrails.

Institutional investors need transparency. That means audit requirements they can trust, legally accountable custodians, clear reporting on asset health, and safeguards against manipulation.

They also need legal certainty. Defined rules give investors confidence. Without them, they’ll stay away — or invest elsewhere.

That’s where Washington plays a role.

The Trump administration shifted U.S. regulatory policy toward digital assets, elevating crypto to a national priority through executive order. Now, with a Republican-led Congress weighing landmark crypto legislation, conservatives have a real opportunity.

This moment demands more than slogans. It calls for applying time-tested conservative principles — rule of law, market discipline, and individual liberty — to the future of finance.

Don’t be afraid

Some treat cryptocurrency as a threat. Fair enough — the collapse of FTX still casts a long shadow over the current debate in Congress.

Sam Bankman-Fried, a Democratic megadonor, didn’t just run a failed company. He ran a cautionary tale — a playbook for what lawmakers must never allow again.

The FTX scandal highlights two enduring conservative truths:

  1. Human nature is flawed. Left unchecked, individuals will act out of greed and self-interest. Conservatives have never pretended otherwise — and that’s why we build systems of accountability.
  2. The rule of law matters. Pre-established standards prevent chaos. Waiting for disaster or making policy on the fly only magnifies the damage.

FTX didn’t collapse because of cryptocurrency. It failed because no one held Bankman-Fried accountable. He amassed influence through backroom politics and ran a tangled network of private firms without meaningful oversight. The result: billions vaporized and public trust shattered.

Thoughtful legislation can prevent the next meltdown — not by stifling innovation, but by setting clear, enforceable rules rooted in transparency, responsibility, and the rule of law.

A remedy with room to improve

The bill now before Congress offers a rare chance to get crypto regulation right.

It tackles the custodial vulnerabilities exposed by the FTX collapse and establishes a framework that allows digital asset projects to integrate into the broader financial system. Just as important, it does so under a unified set of rules.

The bill follows conservative logic. It exempts infrastructure providers — such as blockchain validators and payment processors — from regulatory burdens that don’t apply. These actors don’t make governance decisions, and the law should reflect that.

It also classifies participants based on their actions, rather than the extent of their political influence.

But the bill still needs one critical fix.

Lawmakers need to include decentralized autonomous organizations as eligible cryptocurrency issuers. These DAOs, the opposite of central banks, operate through user-led governance. Crypto users vote on the rules of the system they help create.

DAOs have become common in decentralized finance. Yet the current bill overlooks them. That omission could block the very groups driving innovation from entering the regulated space.

RELATED: Trump’s Bitcoin masterstroke puts America ahead in digital assets

Photo by Anna Moneymaker/Getty Images

If a project follows the rules, discloses information, and acts responsibly, it should qualify, regardless of how it governs itself. Whether the issuer is a DAO, a startup, or a traditional bank, one standard should apply.

That’s the conservative way: equal rules, fair enforcement, and space for innovation to thrive.

What if we get it wrong?

Leaving the bill unamended carries real risks:

  • Overreaching compliance rules could smother the best of American innovation — now and in the future.
  • Narrow legal definitions might force decentralized finance into the hands of a few massive exchanges, recreating the same “too big to fail” system that burned taxpayers in 2008.
  • Ongoing regulatory ambiguity could drive developers and infrastructure providers offshore, into the arms of authoritarian regimes eager to benefit from America’s hesitation.

The biggest danger? Watching capital and talent flee to countries that welcome decentralized commerce while the United States — its origin point — falls behind.

Decentralized finance leaders aren’t calling for lawlessness. They want smart policy.

Joe Sticco, co-founder of Cryptex and a White House Crypto Summit participant, put it this way: “In DeFi, it’s not about evading rules — it’s about building better ones.”

Sticco believes today’s innovators want a seat at the table. “We believe open financial systems can coexist with responsible oversight,” he told me. “We have to show up, we have to explain the tech, and we have to help shape the rules.”

Congress still has time to get this right. But the window is closing.

The path forward

Republicans now hold both chambers of Congress. That means the window to act is wide open.

This isn’t about growing government. It’s about setting the rules so innovation can thrive, fraud gets stopped, and people are held accountable. Here's what that looks like:

  • Clear rules that apply fairly to both traditional companies and decentralized projects;
  • Basic protections like audits, secure custody of funds, and anti-fraud measures;
  • Freedom for developers to build new tools without unfair roadblocks;
  • And clear standards for when crypto projects are considered stable enough to ease up on oversight.

With these fixes, the Clarity Act can do what no other crypto bill has: protect investors, promote innovation, and keep America in the lead.

We can build the future of finance right here — on American terms, with American values. But we have to act now.

Why are Republicans helping Dick Durbin gut Trump’s crypto bill?


Fifteen years ago, Sen. Dick Durbin (D-Ill.) slipped an amendment into law that handed a $90 billion windfall to mega-retailers like Walmart and Target — while forcing everyday Americans to foot the bill.

Now he’s trying to do it again. This time, he’s recruited Republican help.

President Trump has made his priorities clear. He wants America to dominate in financial tech — not hand the future to China.

As a former chairman of the House Financial Services Subcommittee on Capital Markets and Government Sponsored Enterprises — and as a proud Trump ally — I’m alarmed that Sen. Roger Marshall (R-Kan.) has teamed up with Durbin to hijack one of the most important bills of the year: the Genius Act.

This legislation, backed by President Trump, would establish the first federal framework for stablecoins — digital dollars backed by U.S. currency and issued by trusted financial institutions. It’s the cornerstone of America’s entry into 21st-century digital payments and a key to ensuring that we — not China — lead the future of global finance.

President Trump and Vice President JD Vance have made the bill a top priority. “We’re optimistic that the Senate is able to move quickly on passing a clean Genius Act and for the House to follow up and do the same,” Vance told attendees at the Bitcoin 2025 Conference in Nashville.

But that momentum will vanish if Marshall and Durbin succeed in attaching their so-called Credit Card Competition Act. This isn’t reform — it’s the Durbin Amendment 2.0, and we’ve already seen how that story ends.

In 2010, despite widespread opposition, Durbin passed his original amendment, shifting the cost of payment processing from big-box retailers onto credit card companies. He promised that consumers would benefit when retailers passed along those savings.

They didn’t.

A Federal Reserve-backed study later found that only 1% of merchants passed savings on to customers. Meanwhile, 22% raised prices. Card companies — forced to absorb the new costs — cut back on free checking accounts and slashed debit card rewards programs. The number of cardholders earning rewards dropped 30%.

Main Street lost. Big box stores cashed in. Even the left-leaning Progressive Policy Institute now admits the amendment failed and has urged Congress to “rethink” the policy.

The Credit Card Competition Act would repeat the mistake, but with credit cards. It would force every credit card to operate on at least two payment networks, letting mega-retailers route transactions through the cheapest — and often least secure — option. They’d pocket the savings. Consumers wouldn’t see a dime.

RELATED: Trump’s Bitcoin masterstroke puts America ahead in digital assets

Photo by IAN MAULE/AFP via Getty Images

Under the current system, consumers choose the networks by picking the cards they want to carry. Merchants choose which cards to accept. That’s the free market. The CCCA would dismantle that system and take away the rewards — cash back, airline miles, travel perks — that millions of Americans rely on.

Amazon, Walmart, and Target would benefit. Rural consumers, community banks, and small businesses would lose.

If this poison-pill amendment gets attached to the Genius Act, the bill’s broad bipartisan support will vanish. Sen. Thom Tillis (R-N.C.) has already warned he’ll withdraw support if Durbin 2.0 gets jammed into the final package.

Congress must not let backroom deals or crony carve-outs derail this legislation. The Genius Act should be an easy win for consumers, tech innovation, and U.S. leadership in digital finance.

President Trump has made his priorities clear. He wants America to dominate in financial technology — not hand the future to China. His administration supports clear, commonsense rules that unlock innovation, protect consumers, and safeguard the dollar’s global status.

The Genius Act achieves all of that — if lawmakers pass it clean.

Republicans can’t claim to support Trump’s economic agenda while carrying water for woke corporations and their favorite Democrat senator. They need to decide: Stand with Main Street or sell out to K Street. Back American innovation or stick with the same tired crony playbook.

The country doesn’t need another Durbin amendment. It needs leadership.