The champagne communists who sold Millennials a bill of goods


A generation was promised a simple path to the American dream: Earn a four-year degree, get a good job, buy a house, start a family. For many Millennials, the diploma arrived. The rest of the bargain did not.

Now student loan payments compete with rent, mortgages, and the cost of raising children. Graduates work in jobs that never required the credentials they borrowed money to obtain. Meanwhile, socialism has reached its highest positive rating since Gallup began tracking it in 2010. Who sold Millennials the original promise?

You were lied to by leftist universities that gladly took your money and left you in ruin.

Gallup’s September report found that 43% of Americans viewed socialism positively, up from 39% in 2025. Among adults ages 18 to 34, the figure was 57%. It is an extraordinary development. If government-backed higher education helped saddle a generation with debt, why would more government look like the solution?

The financial burden is real. The Federal Reserve Bank of New York reported $1.65 trillion in outstanding student loans in the second quarter of 2026. In a separate Federal Reserve survey, 23% of adults with student loans reported recent difficulty making payments. Even a manageable loan bill is money a borrower cannot put toward a down payment or a family.

But why did so many people borrow so much for credentials whose value varies so widely? Because Americans were repeatedly told a four-year degree was the necessary ticket to adulthood.

Parents heard it. Guidance counselors repeated it. Politicians promised greater access. Universities gladly collected the tuition, helped along by a federal lending system that made borrowing easier today and paying the bill a problem for tomorrow.

And some of the professors who taught students to distrust capitalism were only too happy to work within this arrangement. Universities expanded administrative operations while students took on mounting obligations. The people selling degrees should have been the first to explain what those degrees could actually buy.

The gamble persists for younger graduates. Federal Reserve research using 2023 data on graduates ages 22 to 27 found an underemployment rate of 9.7% for nursing majors, compared with 56.5% for liberal arts and 67.2% for criminal justice. Underemployment here means holding a job that typically does not require a college degree. These graduates are working, but many are not using the expensive credential they were told they needed.

RELATED:CS Lewis knew how clever people teach themselves to be fools
John Chillingworth/Picture Post/Hulton Archive/Getty Images

What did the colleges tell their applicants about those odds? If an 18-year-old is asked to borrow tens of thousands of dollars, the institution ought to disclose the likely costs, earnings, and risks. A degree is an investment only if the buyer has a realistic picture of the return. Universities should face the same scrutiny over misleading promises that we expect of any business.

Students also deserved a serious account of the alternatives: trade schools, apprenticeships, community colleges, military service, and employment without a four-year degree. These are legitimate paths to adulthood, not consolation prizes for people supposedly unfit for college.

There is a cultural problem, too. On too many campuses, students are trained to interpret society through oppression, power, and inequality. Let them study those arguments. But also make them confront the best defenses of markets, private property, entrepreneurship, and the limits of government. A university should teach students to examine competing ideas, not recruit them to a fashionable orthodoxy.

RELATED:Warning: This college course may be bad for your brain
Andi Purnomo/Getty Images

Professors who preach against capitalist exploitation might begin by examining the financial incentives of their own institutions. Some feed students a steady diet of anti-market rhetoric while they borrow heavily for degrees with uncertain returns. That is champagne communism for the faculty and a monthly payment for the graduate.

The irony is hard to miss. A generation taught to question capitalism and burdened by debt from a government-supported lending system may now look to government for relief. But another subsidy does not require universities to tell the truth about what they sell. Nor does it hold anyone accountable for promises that proved empty.

Accountability begins with honest disclosures in university advertising and recruitment. I am working on that problem through the Intellectual Nutrition Label project. If a school makes demonstrably deceptive promises, lawyers and class-action lawsuits may have a role. Institutions that charge families so much should not be exempt from answering for what they represent.

The lesson for Millennials is all too clear. You were lied to by leftist universities that gladly took your money and left you in ruin. It isn’t too late to see the leftist worldview for what it is: the road to serfdom. It’s time to hold the universities that pushed these lies accountable.
Democrats can't erase the price shock of the Biden years


House Minority Leader Hakeem Jeffries (D-N.Y.) says Republicans have "done nothing to make life more affordable for the American people" and instead have "made life more expensive." That’s a remarkable accusation from a party that presided over a historic jump in consumer prices and continues to defend policies that add to the bills families pay.

With the November midterms approaching, Democrats want voters to blame Donald Trump for the cost of groceries, rent, power, and gasoline. They should first account for the prices Americans inherited when Trump returned to office — and for the costs imposed by Democrat-led states.

Americans did not forget what groceries and rent cost four years ago. Democrats should not expect them to forget who held power when those prices took off.

Start with inflation. The Federal Reserve aims for 2% annual inflation over time. Even when inflation slows, prices generally keep rising. A smaller annual increase does not reverse the larger increases that came before it.

According to the consumer price index, overall prices climbed about 21% during Joe Biden's presidency. They rose roughly another 5% between January 2025 and August 2026, the latest available monthly data. Inflation has not stopped: The August report put the 12-month rate at 3.4%. But the distinction between the rate of inflation and the price level explains why families still feel the squeeze from the Biden years.

Household essentials tell the story. The Bureau of Labor Statistics recorded increases of more than 20% in grocery prices and residential rents during Biden's term. Electricity costs rose by roughly 30%. Slower subsequent increases leave those earlier jumps in place.

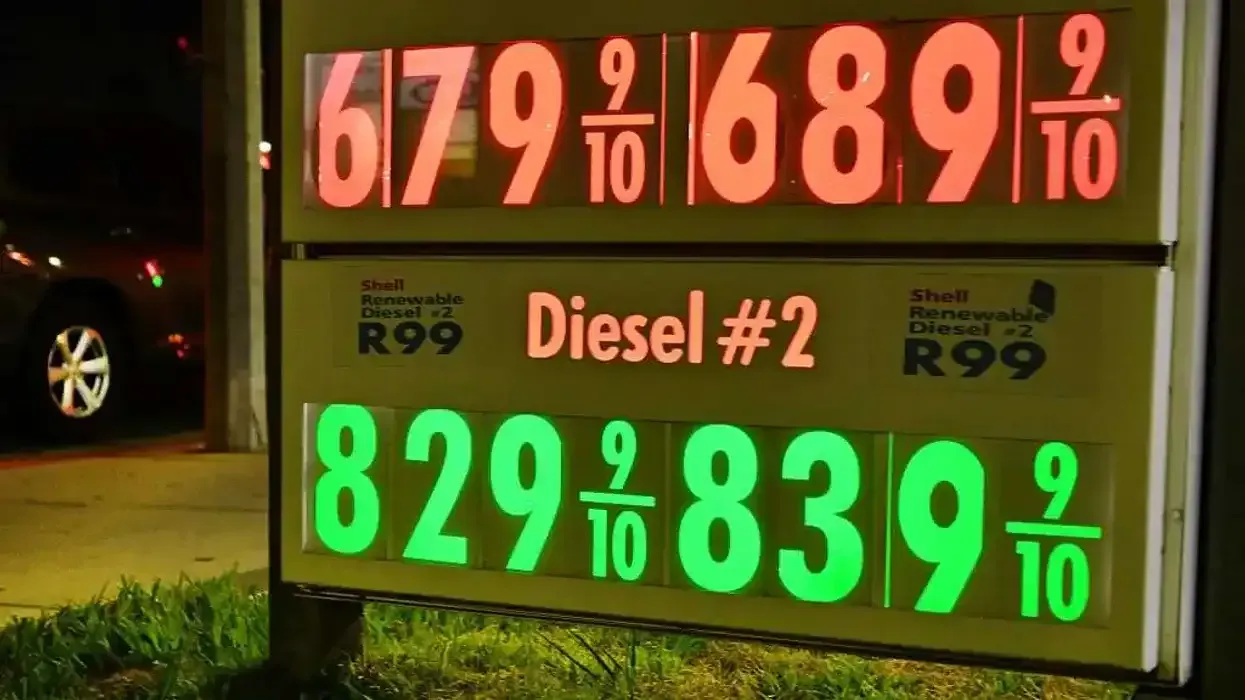
At the pump, the weekly national average hit $5.01 a gallon in June 2022, during Biden's term. It peaked at $4.50 so far in Trump's second term, amid disruptions to oil supplies due to the Iran war. Nominal term averages have run $3.46 under Biden and $3.43 so far under Trump, according to federal energy data.

Still, the household costs Democrats now denounce were already elevated when Biden left office. The party cannot credibly campaign as though American families began paying those bills in January 2025.

State policy makes the contradiction sharper. The Federation for American Immigration Reform, which favors stricter immigration enforcement, estimated in 2023 that illegal immigration imposed a net fiscal cost of $150.7 billion a year on federal, state and local taxpayers. The report raises a question Democrat officials cannot dismiss: Who pays for education, health care, and other public services as migration increases?

RELATED: The diesel panic cure could make the disease worse

Frederic J. BROWN/AFP/Getty Images

Housing supplies another pressure point. A September 2026 Brookings study estimated that the post-pandemic immigration surge raised rents in receiving metropolitan areas by 1.4% to 1.6%. Policymakers who expand immigration without making room for more housing should expect renters to notice.

Electricity offers an even clearer test of state choices. An analysis publicized by the American Energy Alliance found that rates rose 32.4% from 2014 to 2024 in states that backed the Democrat presidential nominee in 2020 and 2024, compared with 18.5% in Republican-voting states. States with mandatory renewable portfolio standards also saw larger increases than those without them. Voters should ask what those mandates cost.

When House lawmakers passed legislation requiring state utility regulators to consider shielding ratepayers from new data-center infrastructure costs, Senate Democrats blocked its advance. Families watching their power bills climb deserved a better result.

Taxes provide another point of comparison. Visual Capitalist's analysis estimated that a New Jersey resident would pay about $1.36 million in federal, state, and local taxes over a lifetime, equal to 48.2% of estimated earnings. Eight of the 10 highest-tax states in that ranking had Democrat governing trifectas in 2026. The concentration is striking.

RELATED: The kindness con: Fraudsters exploit America’s safety net

Aleksei-veprev/Getty Images

New Jersey, my home state, levies the nation's highest top corporate income tax rate, 11.5%. Burlington has announced plans to shift its headquarters to Philadelphia, and Samsung has announced a headquarters move to Texas. ExxonMobil moved its legal domicile to Texas. Lawmakers should consider what those departures say about the state's tax and regulatory climate.

The state's employment figures offer another warning. New Jersey's initial estimate of 25,600 jobs lost in July was subsequently revised to 21,900. Officials have reason to examine the burdens they put on employers.

Americans have also seen welcome gains. The Census Bureau reported that real median household income reached a record $87,460 in 2025, up 2.6% from 2024, while the official poverty rate fell to 10.2%. Median income for black households rose 4.8%.

Democrats are free to make their case that Republican policies have made life more expensive. Voters should require them to answer for their own record: the price surge under Biden, the tax burdens in Democrat-led states, the cost of energy mandates, and the fiscal consequences of immigration policy.

Americans did not forget what groceries and rent cost four years ago. Democrats should not expect them to forget who held power when those prices took off.

After SCOTUS Setback, Trump Renews Bid To Remove Federal Reserve’s Lisa Cook

'As President, it is my job to ensure the laws are faithfully executed, including by firing subordinates who cannot be trusted to tell the truth and follow the law.'

How Trump Can Fight The Fed’s Threat To Housing Affordability

The White House can fight the negative effects of the Fed’s rate hike with policy decisions that will make a measurable difference soon.
New Fed chair bucks Trump, hikes interest rate as inflation fears persist


The Federal Reserve has raised the interest rate as fears of inflation persist despite economic optimism from President Donald Trump.

On Wednesday, the Fed voted unanimously to increase interest rates by a quarter of a percentage point, the first rate-hike since 2023.

'We should have the LOWEST RATE of any country in the World.'

"Economic activity is expanding at a solid pace. While uncertainty remains elevated owing, in part, to geopolitical developments,domestic spending has been resilient. Productivity growth is strong, and capital investment is robust. Job gains have kept pace with the workforce, and the unemployment rate has changed little," a press release from the Fed said.

"Inflation remains elevated. Today's policy action will support a timelier return to the Committee's 2 percent goal. The Committee will deliver price stability."

New Fed Chairman Kevin Warsh voted to increase the rate even though Trump has repeatedly called for rate cuts to keep the U.S. economy growing.

The latest jobs report released two weeks ago showed impressive gains in August and revealed that reports from previous months had been revised upward.

In response to the jobs report, Trump posted, "Lower the interest rates because the U.S.A. is a much stronger credit than it was just a short time ago! A STRONG COUNTRY MEANS A LOWER INTEREST RATE — IT’S A BETTER CREDIT ... Very simple! We should have the LOWEST RATE of any country in the World."

He even threatened to "STOP TRADING WITH COUNTRIES WITH WHICH WE HAVE A DEFICIT" if the Fed failed to lower rates.

RELATED: 'Blow expectations out of the water': HUGE GAINS in latest jobs report

Michael M. Santiago/Getty Images

The White House did not respond to a request for comment from Blaze News.

The rate-hike is the first major Fed move under Warsh's leadership. Trump nominated Warsh to replace Chairman Jerome Powell, who officially stepped down in May after repeatedly butting heads with Trump, especially regarding interest rates.

Trump even took to calling Powell "Too Late," claiming that the then-chair's failure to lower rates was stifling the American economy. Trump blamed Powell's obstinance on "gross incompetence, total dishonesty, or both."

For his part, Warsh has been tight-lipped about his plans at the Federal Reserve, claiming back in August that he prefers to have a "good family fight" about interest rates and other decisions rather than tip his hand ahead of time.

Wall Street has mainly responded favorably to the rumors about the impending rate increase. The NASDAQ and S&P opened Wednesday with gains, while the Dow Jones opened slightly down. Immediately after the hike announcement, all three markets were in the green.

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

Trump’s interest-rate fantasy runs into debt gravity


You can have very low interest rates, and you can have debt-driven inflation. You just can’t have both at the same time. That is the reality President Trump refuses to recognize.

At the core of the president’s half-baked plan to resuscitate the economy is a return to the good old days of near-zero interest rates.

The Federal Reserve can set the short-term rates as low as it wants, but the bond markets will continue to rebel and reflect reality.

“We should have the lowest interest rates anywhere in the world,” Trump said last week in response to a reporter’s question in the Oval Office.

“In the old days … if we announced good numbers, interest rates went down. Now, if you announce good numbers, interest rates go up because they’re so afraid of inflation.”

It’s hard to make sense of that statement, but it reflects a grievance Trump has voiced consistently. He wants endless spending for his projects, he doesn’t want the inflation it causes, and he wants to pay near-zero interest on the resulting record debt. Don’t we all?

Perhaps in another lifetime, God will create such an innovative world. In this one, when you have protracted inflation and must sell endless Treasuries to service the debt, you cannot offer near-zero interest to buyers of that debt — especially at a rate below inflation.

We had multiple periods of near-zero interest rates this century, including during COVID. We also spent trillions of dollars we did not have during Trump’s first term and Biden’s presidency. That helped fuel the inflation surge of 2021-22. Prices have continued rising even as the inflation rate slowed, while the debt keeps exploding. Year-over-year inflation has now remained above the Fed’s 2% target for 65 consecutive months, with most months above 3%.

Far from being “artificially high,” as Trump contends, rates have been held artificially low. After the federal funds rate peaked at 5.5% during the inflation fight — a historically unremarkable level — the Fed cut rates six times beginning in 2024. The effective rate now stands at 3.63%, below the long-run average.

So what did the bond market do? The 10-year Treasury yield is roughly as high as it was when the federal funds rate peaked in 2024, and the 30-year yield is at levels not seen since 2007.

The Federal Reserve can set short-term rates as low as it wants, but the bond market will still reflect fiscal reality. There is no way around crushing debt other than cutting spending.

RELATED: The government would like to discuss your allowance

Love Employee/iStock/Getty Images

That was on vivid display late last month when Treasury Secretary Scott Bessent instituted a “twist” operation: The government bought back more long-dated Treasuries while relying more heavily on cheaper short-term bills and notes to finance the deficit and the purchases themselves. The goal was to reduce the supply of long-duration debt, support bond prices, lower long-term yields, and exploit the fact that short-term rates remain below 10- and 30-year yields.

The response from the bond market?

After a few hours of lower yields, by the next morning they were back near their pre-announcement baseline.

The 10-year yield is now around 4.75%, higher than at any point since April 2007. Back then, the effective federal funds rate was 5.25% — 162 basis points above today’s rate. The bond market is telling us that long-term rates are not high because the Fed forgot how to cut. They are high because investors demand compensation for inflation, deficits, and debt risk.

There is a simple reason the Fed can no longer wave a magic wand, return rates to near zero, and service the debt on the cheap as it did from the post-9/11 recession through COVID. On September 11, 2001, gross federal debt was about $5.77 trillion, roughly 55% of GDP. In April 2007, before the financial crisis, it was about $8.84 trillion, or 63% of GDP. Today it exceeds $40 trillion and is roughly 123% of GDP.

RELATED: Democrats want amnesia on inflation

wildpixel/iStock/Getty Images

The long-term trajectory is even worse, because faster debt growth creates a vicious cycle: Treasury needs more buyers, inflation and fiscal risk force yields higher, and more existing debt rolls over at those higher rates.

After an election fought in part against Bidenflation, nearly $4 trillion in new debt has been added since January 2025. Across Trump’s two terms, roughly $11.7 trillion of gross federal debt has accumulated. There are still more than two years left in his term, and there is no serious plan to bend the trajectory.

Naturally, all this new debt is being accumulated at higher interest rates. But the sheer magnitude of the debt also makes Trump’s dream of permanently cheap money impossible.

We all share Trump’s desire to service the debt on the cheap. He probably should have thought harder about that desire when he pressured Republicans in March 2020 to shut down the country and then pass trillions in new spending. Unfortunately for him and his delayed second term, what goes around in debt comes back around as inflation and higher interest rates.

Fed Deep State Undercuts Kevin Warsh, Who Wins Some Surprise Support

The new chairman of the Federal Reserve, Kevin Warsh, is facing his own version of the same problem that the president who appointed him encountered—an entrenched and highly partisan bureaucracy that fiercely resists change while taking itself very seriously.

The post Fed Deep State Undercuts Kevin Warsh, Who Wins Some Surprise Support appeared first on .

New Fed chair's first major interest-rate decision doesn't rock the boat — and Trump may not be happy about it


The first major decision at the Federal Reserve under new Chairman Kevin Warsh has come and gone, but little has changed.

On Wednesday, the Fed announced that the interest rate would hold at between 3.5% and 3.75%, despite calls from Dallas Fed President Lorie Logan and others for a "modest" increase.

'We will deliver price stability.'

The decision was released at 2 p.m. ET, revealing that Warsh and eight other committee members had voted in favor of a fifth straight hold on rates, while three opposed.

Shortly after the announcement, Warsh spoke publicly.

"The economy is showing impressive resilience," Warsh said. "Even with recent shocks, the trends are positive and reveal solid growth. Job gains have kept pace with the workforce, and the unemployment rate has changed little."

Warsh also admitted that "inflation remains elevated relative to the committee's 2% goal," but promised: "We will deliver price stability."

The White House did not immediately respond to a request for comment from Blaze News.

RELATED: Jerome Powell is out — for good reason. Here are 4 of his top blunders.

Anna Moneymaker/Getty Images

President Donald Trump has pushed for years for the Fed to lower interest rates. "Interest Rates too high!" he posted on Truth Social back in May.

On Monday, Trump said of Warsh: "Kevin’s fantastic, but he’s got a board, and the board members are very political. He wants to do the right thing. I know what he wants to do. But you need the consent of some people that have perhaps bad intentions. Rates should be lowered."

Trump nominated Warsh to be Fed chair back in January, and he was confirmed in May. Warsh replaced longtime Chair Jerome Powell, who repeatedly butted heads with Trump over interest rates.

Trump nicknamed Powell "Too Late" and called him a "DISASTER" because of his reluctance to lower interest rates.

"Jerome 'Too Late' Powell wants to stay at the Fed because he can’t get a job anywhere else — Nobody wants him," Trump wrote in April.

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!

Glenn Beck: The housing crisis will spiral out of control unless we do this NOW


Why does buying a home feel more out of reach than ever? According to Blaze Media co-founder Glenn Beck, the answer isn’t corporate greed, mysterious market manipulation, or some hidden conspiracy theory. It’s basic economics and government policy.

Citing new research from the Federal Reserve Bank of Dallas and data from the National Association of Home Builders, Beck argues that America’s housing affordability crisis stems from a collision of rising demand and artificially constrained supply.

“Thirty percent of the increase in U.S. home prices from '21 to '24 along with 20% of the rise in rent prices comes from just bringing in seven, 10, 15 million people and just adding them in,” Glenn explains.

“Today, our home, the typical American house, runs closer to five times what a family earns in a year,” he adds.


Back in March, economists at the Federal Reserve Bank in Dallas ran the numbers on what seven million illegal border crossings under the Biden administration did to the local housing market.

In Dallas, it put “roughly 30% of the total run-up in home prices and about 20% of the run-up in rents.”

“Every 1% increase in unauthorized workers relative to the local workforce pushed the home price up 2.2%. And rents up 1.4%. So you want to know why we’re having a hard time buying houses?” he asks, answering, “It’s because our local governments along with the federal and state government are completely out of control with regulation, and our federal government just opened up the borders.”

“Now, why isn’t that being explained to the American people?” he asks.

“It’s not the builders. It’s not the people selling the houses. It’s the government that is the problem,” he says.

And while the Biden administration spent four years adding millions of people to the demand side, local and federal governments made it "slower and more expensive to add anything to the supply side."

“There’s no mystery here. There’s no shadowy cartel. There’s no Jew behind the corner. It’s a bathtub with the tap wide open and a towel that is stuffed in the drain,” Glenn explains.

“Which means the fix should be just as simple. And there are three fixes,” he says.

“One, don’t add people to the country faster than you can add roofs to it. ... Two, make it legal to build a cheap house. ... Three, stop borrowing money you didn’t have because the deficit sets the interest rate and the interest rate sets the mortgage,” he continues.

“I don’t know why we don’t do this.”

Want more from Glenn Beck?

To enjoy more of Glenn’s masterful storytelling, thought-provoking analysis, and uncanny ability to make sense of the chaos, subscribe to BlazeTV — the largest multi-platform network of voices who love America, defend the Constitution, and live the American dream.

No slaughter for the CIA's DEI office — yet


President Trump won the 2024 election promising to gut Biden-era DEI across the federal government, calling it "illegal and immoral." The CIA and the Office of the Director of National Intelligence tried to do exactly that — moving to fire 19 career officers who had spent their time on diversity, equity, and inclusion assignments instead of actual intelligence work.

Two Democrat-appointed judges said not so fast.

'As long as the employee subject to termination chooses to pursue reassignment, the agencies must attempt to reassign her.'

The 4th U.S. Circuit Court of Appeals ruled 2-1 Thursday that the CIA and ODNI have to let the 19 DEI-linked officers appeal their firings and, in some cases, apply for reassignment before they can be shown the door, the Washington Times reported.

The panel found the agencies skipped procedural steps required for a reduction in force — a technicality that's now kept the firings frozen for well over a year, according to Bloomberg Government.

Writing for the majority, Biden-appointee Judge Nicole Berner — joined by Obama-appointee Judge Stephanie Thacker — ruled the officers had enough of a claim to their jobs to sue in the first place.

Berner wrote: "As long as the employee subject to termination chooses to pursue reassignment, the agencies must attempt to reassign her."

RELATED: 'BIG WIN': Trump calls SCOTUS 'Slaughter' ruling the greatest increase of presidential power in 100 years

Graeme Sloan/Bloomberg/Getty Images

In a blistering dissent, Judge Paul Niemeyer, a George H.W. Bush appointee, argued that Congress gave intelligence directors "unfettered discretion" to fire employees precisely so courts couldn't micromanage personnel decisions at agencies handling national security.

He called the injunction unlawful and urged the Supreme Court to step in, calling it a serious separation-of-powers problem: judges telling the CIA how to run its own house.

The ruling lands days after the Supreme Court handed Trump a win affirming his broad authority to fire employees, with a separate case providing a narrow carve-out for officials like Federal Reserve board members.

Like Blaze News? Bypass the censors, sign up for our newsletters, and get stories like this direct to your inbox. Sign up here!